The Big Short (2015) - FrontPoint Partners confronts Morgan Stanley Risk Assessors and S&P
Extractor
AI-assisted summary of The Big Short (2015) - FrontPoint Partners confronts Morgan Stanley Risk Assessors and S&P — original source. Check the original for full context.
Source published:
Key ideas
- Subprime mortgage delinquencies are surging across the country, yet subprime bond prices are anomalously increasing rather than declining. (0:14)
- Deutsche Bank issued a margin call requiring FrontPoint Partners to post an additional $1.9 million in collateral by market close. (0:14)
- Morgan Stanley risk assessors pressured FrontPoint to liquidate their short positions, arguing that committing years of insurance payments toward a housing collapse is not prudent. (0:14)
- An S&P executive admitted that the agency rubber-stamps AAA ratings on subprime securities because issuing banks would otherwise take their business to Moody's. (2:17)
Detailed notes
## Background This clip was published on YouTube by the channel Extractor on March 7, 2017. Drawing from the 2015 film The Big Short, the page description highlights FrontPoint Partners' clashes with risk managers over housing Armageddon trades and their fiery accusation that credit rating agencies operate as commercial "rating shops" selling AAA stamps for fees.
## TL;DR As nationwide mortgage defaults surge, FrontPoint Partners faces baffling price increases on subprime mortgage bonds alongside an immediate $1.9 million margin call from Deutsche Bank. Internal Morgan Stanley risk assessors pressure the desk to liquidate their short positions, prompting Mark Baum to instruct his team to dismiss the risk managers entirely. Baum and his associates then march over to Standard & Poor's to confront executive Georgia Hale over why toxic bonds still retain pristine AAA marks. Pressed on whether the agency ever denies investment banks their desired ratings, Hale openly admits that refusing to grant top grades would simply drive lucrative underwriting fees down the block to Moody's.
## Atmosphere & style The scene crackles with rising panic, intense cynicism, and biting dark comedy. It begins in a claustrophobic trading desk environment fraught with disbelief and institutional friction before pivoting into a tense, surreal interrogation at Standard & Poor's. Mark Baum's righteous moral outrage clashes sharply with corporate complacency and calculated self-interest, creating an unnerving realization of systemic corruption.
## Bulletin - [00:14](https://www.youtube.com/watch?v=mwdo17GT6sg&t=14s) Subprime mortgage delinquencies are surging across the country, yet subprime bond prices are anomalously increasing rather than declining. - [00:14](https://www.youtube.com/watch?v=mwdo17GT6sg&t=14s) Deutsche Bank issued a margin call requiring FrontPoint Partners to post an additional $1.9 million in collateral by market close. - [00:14](https://www.youtube.com/watch?v=mwdo17GT6sg&t=14s) Morgan Stanley risk assessors pressured FrontPoint to liquidate their short positions, arguing that committing years of insurance payments toward a housing collapse is not prudent. - [02:17](https://www.youtube.com/watch?v=mwdo17GT6sg&t=137s) An S&P executive admitted that the agency rubber-stamps AAA ratings on subprime securities because issuing banks would otherwise take their business to Moody's.
## Key takeaways - [00:14](https://www.youtube.com/watch?v=mwdo17GT6sg&t=14s) FrontPoint Partners observes a sharp disconnect between soaring nationwide mortgage defaults and rising subprime mortgage bond prices. - [00:14](https://www.youtube.com/watch?v=mwdo17GT6sg&t=14s) Deutsche Bank demands FrontPoint supply $1.9 million in margin by the close of the trading day to support its credit default swap positions. - [00:14](https://www.youtube.com/watch?v=mwdo17GT6sg&t=14s) Despite worsening subprime loan performance, credit rating agencies Moody's and Standard & Poor's continue to maintain AAA ratings on mortgage bonds and CDOs. - [00:14](https://www.youtube.com/watch?v=mwdo17GT6sg&t=14s) Mark Baum attributes the rating agencies' inaction to their status as publicly traded corporations, arguing they prioritize stock prices and corporate earnings over objective risk assessment. - [00:14](https://www.youtube.com/watch?v=mwdo17GT6sg&t=14s) Morgan Stanley risk managers intervene at FrontPoint, attempting to convince Kathy Tao to force the liquidation of the fund's short trades. - [00:14](https://www.youtube.com/watch?v=mwdo17GT6sg&t=14s) Mark Baum rejects the risk assessors' oversight entirely, ordering Vinnie Daniel to tell the Morgan Stanley executives to fuck off. - [02:17](https://www.youtube.com/watch?v=mwdo17GT6sg&t=137s) During a meeting with FrontPoint, S&P executive Georgia Hale defends the agency's inaction by claiming delinquency rates remain within predictive mathematical models. - [02:17](https://www.youtube.com/watch?v=mwdo17GT6sg&t=137s) FrontPoint challenges S&P on whether its analysts actually review raw loan-level data, highlighting that lenders have granted mortgages without proper vetting. - [02:17](https://www.youtube.com/watch?v=mwdo17GT6sg&t=137s) Mark presses Georgia on whether S&P has ever refused to grant an issuing investment bank the exact percentage of AAA ratings it requested. - [02:17](https://www.youtube.com/watch?v=mwdo17GT6sg&t=137s) Georgia confirms a structural conflict of interest: S&P awards requested ratings because issuing banks will take their lucrative business to Moody's if S&P refuses. - [02:17](https://www.youtube.com/watch?v=mwdo17GT6sg&t=137s) Mark argues that credit rating agencies should accept earning less revenue rather than compromise their standards and sell inflated ratings for fees. - [02:17](https://www.youtube.com/watch?v=mwdo17GT6sg&t=137s) Georgia pushes back on FrontPoint's moral posturing, pointing out that Mark's fund holds massive credit default swap positions and stands to gain financially from the downgrades they demand.
## Detailed walkthrough ### [00:14](https://www.youtube.com/watch?v=mwdo17GT6sg&t=14s) Margin Calls and Morgan Stanley Risk Assessors
The FrontPoint Partners trading desk descends into chaos as the team struggles to comprehend the disconnect between market reality and bond pricing. Mortgage defaults across the country have spiked dramatically, yet subprime mortgage bond prices are bizarrely rising instead of crashing. On the phone, Deutsche Bank is aggressively demanding an additional $1.9 million in collateral by market close to cover FrontPoint's short positions. Mark Baum demands an explanation as the team vents their disbelief that bonds backed by deteriorating subprime loans are somehow being marked as more valuable. When Mark asks whether credit rating agencies like Moody's and Standard & Poor's have begun downgrading the collateralized debt obligations (CDOs) or mortgage bonds, the team confirms that nothing has changed—the tranches remain stamped with pristine AAA ratings. Mark angrily rails against the agencies, convinced their public corporate status has reduced them to prioritizing their own bottom line and stock prices over objective risk analysis.
Matters worsen when the team informs Mark that Morgan Stanley risk assessors have descended on their office. The risk managers have pulled in Kathy Tao to pressure FrontPoint into liquidating their credit default swaps, arguing that locking up capital to fund years of premiums in anticipation of a housing crash is completely irresponsible. When Mark asks what Kathy has said, the desk reports that she hasn’t yielded yet, only asking whether this trade is merely another one of Mark's ideological crusades. Refusing to back down, Mark gives Vinnie Daniel explicit marching orders on how to handle the bank's oversight. Mark instructs him: “Okay. I want you to walk back in there and, very calmly and very politely, tell the risk assessors to fuck off.” Mark then arranges to rendezvous with the team at Standard & Poor’s offices to confront an agency executive named Georgia, while Vinnie enters the conference room and delivers Mark's directive verbatim to the assembled Morgan Stanley executives.
- **Collateral demand:** Deutsche Bank required an additional $1.9 million in margin by the close of trading. - **Rating agency inaction:** Despite soaring mortgage delinquencies, S&P and Moody's maintained AAA ratings on subprime mortgage bonds and CDOs. - **Internal pushback:** Morgan Stanley risk assessors argued that committing six years of insurance premiums toward a housing market collapse was an imprudent investment strategy.
```mermaid flowchart TD accTitle: Housing Market Disconnect and FrontPoint Conflict accDescr: Diagram showing how subprime mortgage defaults lead to margin calls and conflicts with Morgan Stanley risk assessors and S&P ratings.
subgraph MarketDivergence["Market Reality vs. Bond Pricing"] A["Subprime Mortgage Defaults Spike"] --> B["Subprime Bond Prices Mysteriously Rise"] B --> C["Deutsche Bank Demands $1.9M Collateral"] B --> D["Credit Rating Agencies Keep AAA Status"] end
subgraph InternalConflict["FrontPoint Resistance"] C --> E["Morgan Stanley Risk Assessors Pressure Kathy Tao"] E --> F["Demand FrontPoint Sell Off Short Positions"] F --> G["Mark Baum Orders Team to Dismiss Assessors"] G --> H["Confrontation with Standard & Poor's"] end ```
---
[02:17](https://www.youtube.com/watch?v=mwdo17GT6sg&t=137s) Confronting S&P and the Conflict of Interest
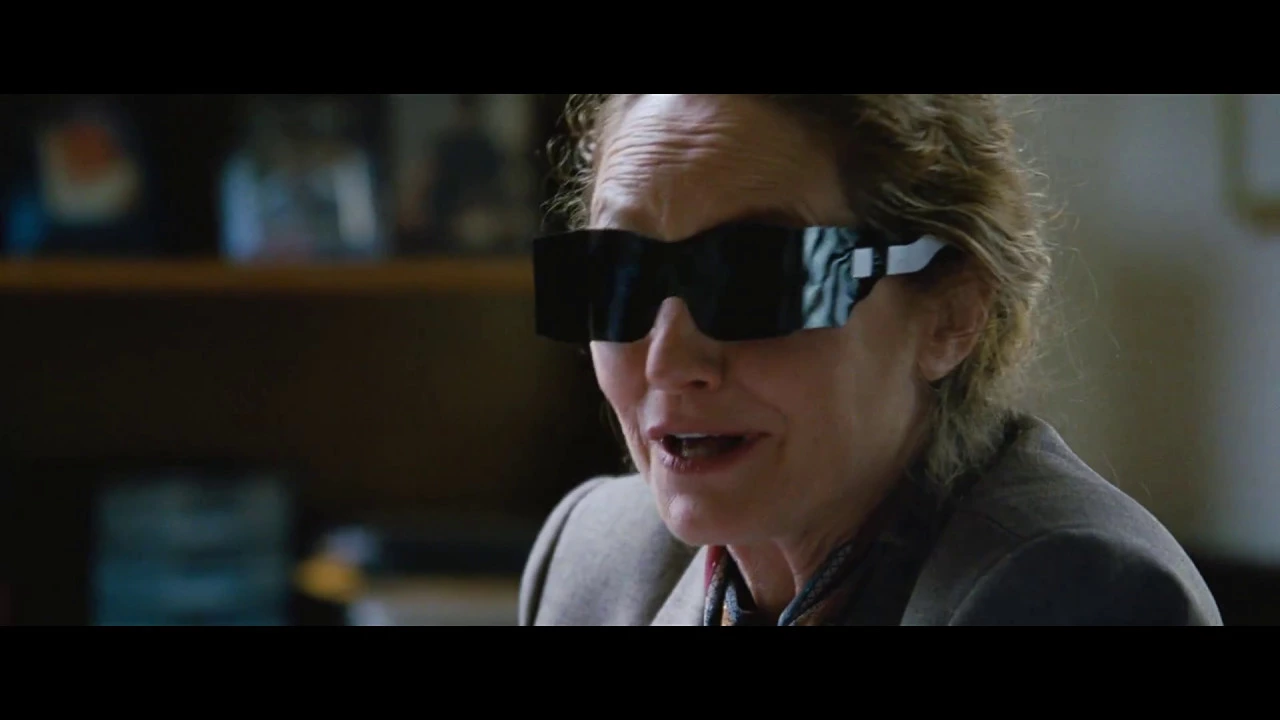
Arriving at Standard & Poor’s, Mark Baum and his associates sit down with S&P executive Georgia Hale, who is disoriented and wearing oversized dark sunglasses after having her eyes dilated during a morning eye appointment. FrontPoint immediately challenges her on why the agency has failed to downgrade subprime residential mortgage-backed securities when the underlying loans are demonstrably failing. Georgia dismisses their concerns, arguing that while delinquency rates have caused market anxiety, they remain strictly within S&P’s predictive mathematical models. When the FrontPoint team presses her on whether analysts have actually scrutinized the raw tape and loan-level data—pointing out that lenders have been handing out mortgages to anyone with a credit score and a pulse—she defensively asks what they imagine S&P staff do all day.
Mark refuses to be deflected and zeroes in on whether S&P has ever pushed back against Wall Street's investment banks. He demands to know if she can cite a single instance in the prior year where S&P reviewed the underlying loan tape and refused to give the issuing banks the exact AAA percentage they requested. Georgia initially insists that S&P is under no legal obligation to disclose its internal deliberations, but under Mark's relentless interrogation, she finally concedes the commercial reality behind their ratings. Georgia bluntly explains the structural conflict of interest driving the system: “If we don't give them the ratings, they'll go to Moody's right down the block. If we don't work with them, they will go to our competitors.”
The admission confirms Mark's worst suspicions: Standard & Poor's is operating not as an impartial auditor, but as a ratings shop selling high-grade stamps to preserve its client fees. When Mark tells her that if they can afford to make less money they should simply make less, Georgia retorts that she is bound by executive hierarchy and does not make company policy. She turns the moral argument back on FrontPoint, questioning their self-interest and directly asking Mark how many credit default swaps his fund owns. While Georgia points out that FrontPoint stands to profit immensely from the downgrades they are demanding, Mark stands his ground on the underlying truth of the crisis, prompting her to dismiss his crusade as pure hypocrisy.
- **Model justification:** S&P maintained that rising subprime delinquency figures fell entirely within their existing risk and pricing models. - **Competitive pressure:** S&P analysts rubber-stamped AAA ratings for investment banks out of fear that clients would take their bond-structuring fees down the block to Moody's. - **The moral impasse:** Georgia challenged FrontPoint's motives by asking, “How many credit default swaps do you own?”, concluding that Mark's short positions made him a hypocrite even if his financial assessment proved accurate.
## Notable quotes > [02:17](https://www.youtube.com/watch?v=mwdo17GT6sg&t=137s) If we don't give them the ratings, they'll go to Moody's right down the block. If we don't work with them, they will go to our competitors. — Georgia Hale
## Mentioned FrontPoint Partners, Morgan Stanley, Deutsche Bank, Mark Baum, Moody's, Standard & Poor's, Kathy Tao, Vinnie Daniel, Georgia Hale
## Video description "...apparently, uh, tying up six years of insurance payments in hopes of housing Armageddon is not a prudent investing." "...Okay. I want you to walk back in there and, very calmly and very politely, tell the risk assessors to **** off."
"You are selling ratings for fees...Rating Shop." "If you can afford to make less, make less."
[Source](https://www.youtube.com/watch?v=mwdo17GT6sg)