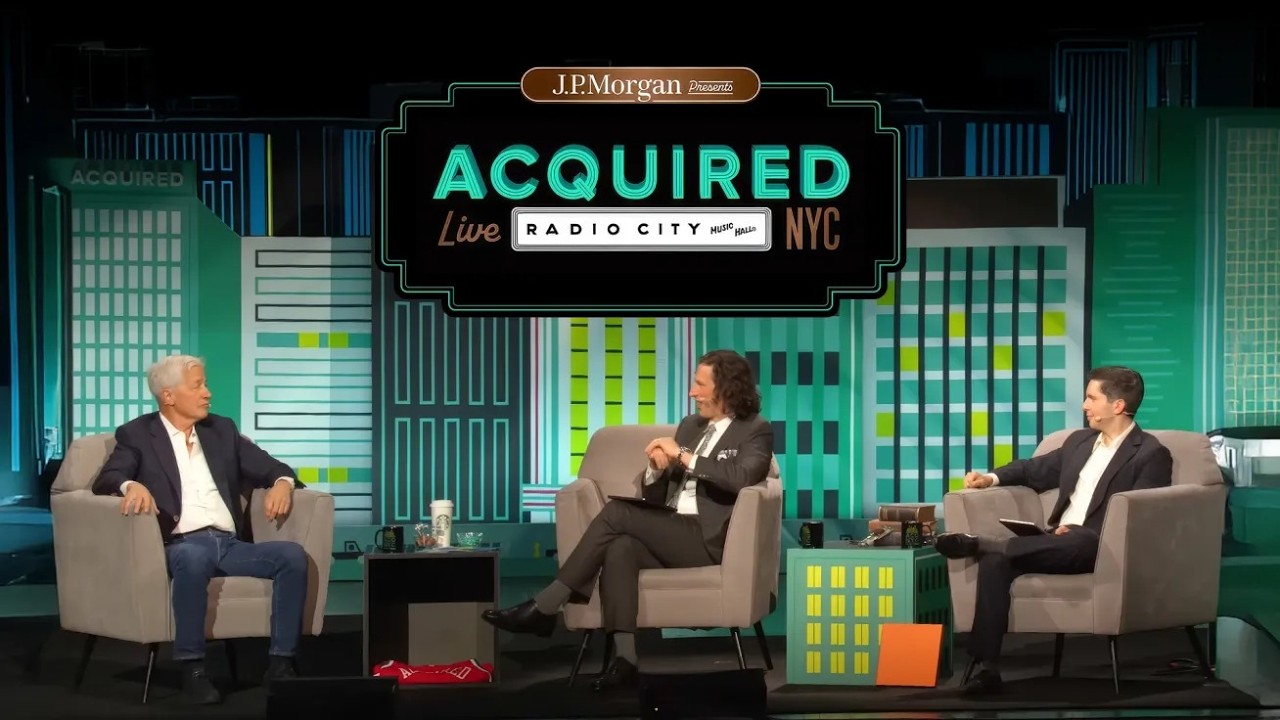
Dimon Targets Cyber Warfare as Top Systemic Threat to Financial Systems
Acquired
While modern banking regulators obsess over interest rate risk and private credit bubbles, the ultimate danger to global economic stability is state-sponsored cyber warfare targeting vulnerable national infrastructure grids.
## Background
Published on November 5, 2025, on YouTube by the channel Acquired, this video presents the full recording of their first "concert film" recorded live at Radio City Music Hall. The show features a star-studded lineup of business and media icons, including Jamie Dimon, Andrew Ross Sorkin, Meredith Kopit Levien, and Barry Diller, alongside several high-profile cameos from the Acquired universe.
## TL;DR
The live event tracks the evolution of major American corporate empires through deeply personal interviews with their central protagonists. JPMorgan Chase CEO Jamie Dimon shares an extensive 20-year retrospective on surviving high-profile firings, rebuilding Bank One, managing systemic risk, and navigating historical financial crises like the 2008 meltdown. New York Times CEO Meredith Kopit Levien outlines the newspaper's dramatic digital transformation into a multi-faceted subscription bundle, while legendary media executive Barry Diller reflects on his 60-year career spanning old Hollywood, the creation of Fox, and pioneering digital interactivity with IAC and QVC.
## Atmosphere & style
The performance carries an electric, theatrical suspense that mirrors a high-stakes Broadway production, opening with a roar of crowd energy, shifting spotlights, and the hosts' signature theme music. It feels like an intimate yet monumental late-night talk show where corporate titans drop their standard public relations guards to engage in candid, humorous, and deeply reflective storytelling. The conversations balance heavy, patriotic discussions about navigating existential financial and technological threats with lighthearted, nostalgic banter, leaving the audience with a profound sense of institutional history and celebration marking the podcast's 10-year anniversary.
## Key takeaways
- [01:01](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=61s) The hosts open their milestone live show at Radio City Music Hall, reflecting on their journey from a small listener event with a failing PA system at a San Francisco WeWork to filling an iconic 6,000-seat New York venue.
- [05:44](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=344s) Jamie Dimon discusses his abrupt 1998 firing from Citigroup by Sandy Weill, which stemmed from structural disagreements on wanting to streamline the massive financial conglomerate.
- [10:08](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=608s) Following his exit from Citigroup, Dimon spent 18 months evaluating options—including a highly successful meeting with Jeff Bezos about becoming president of Amazon—before ultimately choosing to return to banking at Bank One.
- [15:48](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=948s) Dimon inherited severe operational chaos, a fractured board, and massive unhedged corporate credit risk at Bank One, which he resolved by radically transforming the corporate culture and personally auditing every loan.
- [21:36](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1296s) JPMorgan Chase's long-term survival and resilience are anchored in Dimon's 'Fortress Balance Sheet' philosophy, prioritizing high margins, deep liquidity, conservative accounting, and preparing for worst-case 'fat tail' risk scenarios over short-term profit maximization.
- [25:22](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1522s) The strategic 2004 merger of equals between Bank One and JPMorgan Chase was engineered with ironclad governance clauses to protect Dimon's path to becoming unified CEO within 18 months.
- [28:56](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1736s) JPMorgan avoided the worst of the 2008 financial crisis by pulling back from subprime mortgages in late 2006 and maintaining a fraction of the leverage ratios carried by its peer investment banks.
- [32:33](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1953s) Dimon details the emergency weekend acquisition of Bear Stearns for $2 a share, noting that while it solidified the bank's long-term reputation, subsequent government lawsuits over legacy Bear Stearns assets led him to a strategy of 'strategic surrender' to protect his firm.
- [38:28](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2308s) The acquisition of Washington Mutual expanded JPMorgan's retail footprint into high-growth states at a massive $30 billion discount to book value, allowing the bank to fully absorb expected mortgage write-offs.
- [41:05](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2465s) Dimon outlines modern systemic risks, heavily criticizing regulatory 'held to maturity' accounting tricks and pinpointing state-sponsored cyber warfare as his ultimate anxiety, while downplaying immediate bubble fears in private credit.
- [44:11](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2651s) The 2023 regional banking crisis that claimed SVB and First Republic was fueled by highly 'concentrated deposits' and modern herd behavior within venture networks, rather than just basic uninsured deposit risk.
- [47:58](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2878s) JPMorgan separates itself from competitors by operating efficiently like a traditional community bank, maintaining a superior efficiency ratio through continuous investment across economic cycles.
- [01:01:13](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3673s) The New York Times engineered a dramatic digital turnaround from the brink of collapse in 2008 to closing in on 12 million subscribers by recreating the classic multi-faceted Sunday newspaper bundle for the digital era.
- [01:09:06](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4146s) The Times utilizes AI strictly as a force multiplier for document parsing and automated voice, while fiercely defending content copyright through litigation against tech giants who fail to pay fair value for human journalism.
- [01:29:33](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5373s) Barry Diller traces his foundational understanding of the entertainment business to spending three years systematically reading the entire physical file room from A to Z at the William Morris Agency.
- [01:31:52](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5512s) During his tenure at ABC and Paramount, Diller pioneered the 'Movie of the Week' concept and shifted the studio model toward internal material development with massive hits like Saturday Night Fever.
- [01:42:01](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6121s) Diller praises his former partner Rupert Murdoch as an extraordinary entrepreneurial gambler, but notes that corporate managers must never 'bet the company' if a failure can drag down a healthy core business.
- [01:25:20](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5120s) Leaving traditional Hollywood behind at age 49, Diller's exposure to real-time interactive commerce data at QVC gave him a crucial head start to build IAC and its portfolio of over 150 digital brands.
- [01:25:20](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5120s) The entertainment hegemony has fundamentally shifted from traditional Hollywood studios to Silicon Valley tech giants, with Netflix winning the media sector by establishing a service-centric, subscriber-bundle model.
- [01:56:32](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6992s) The live event closes by celebrating the 10-year anniversary of the Acquired podcast, evolving from a niche technology show into a premier corporate history and strategy stage.
## Detailed walkthrough
### [00:02](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2s) The Suspense and Mystery of Broadway
The show has completely sold out without the hosts ever telling anyone what is happening, which leaves them joking about hoping the audience isn't disappointed. Reflecting on whether they should have at least released a detail or named one guest, they embrace the theatrical suspense of New York, comparing it to Broadway. As they figure out which train to take—concluding it is the B train—they comment on how New York truly feels like the center of everything. They share a laugh over a famous New Yorker cartoon depicting a New Yorker's view of American geography: the island of Manhattan, the Hudson River, and then nothing but California directly on the other side. With a little bit of time before the show, they decide to indulge in a classic New York experience and grab a hot dog.
### [01:01](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=61s) Stepping onto the Grandest Stage
Walking around Central Park, grabbing bagels, and eating hot dogs is described as a favorite routine when visiting New York. Looking back at their origins, the hosts reminisce about the very first listener live event they ever hosted, which took place at a Geekwire conference in Seattle. They then recall an early event at a WeWork in San Francisco's Tenderloin district for about 100 people, where the PA system completely failed halfway through the recording, forcing someone to run to Best Buy to purchase a replacement system. Marveling at how far they have come, they are introduced to a roaring crowd at Radio City Music Hall to the tune of their theme song, "Who Got the Truth?"
### [02:19](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=139s) A Sudden Shift in Tone
Standing on the massive stage, the hosts initially feel that their standard podcast setup is a bit of a waste of the legendary Radio City Music Hall. Deciding they need to "level it up a little bit," they call on Mike Taylor to help change the energy in the room. The music kicks in heavier, the lights shift, and the crowd erupts into applause as the full production value of the venue is unleashed.
- The hosts wear sharp clothing to mark the historic venue, extending a special thanks to Hermes for helping them show up in style.
- The audience consists of listeners who traveled from various states and completely different continents.
### [03:59](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=239s) A Two-Act Night for New York
The hosts explain that they thought long and hard about how to put on the best possible show for the greatest stage in the greatest city in the world. Their plan for the night is structured into two distinct acts featuring conversations with three of New York's most iconic corporate leaders. Act one features a massive conversation with an important American company never before covered on the podcast, told alongside the protagonist himself. Act two features a brand-new format specifically designed to leverage the unique scale of Radio City Music Hall.
### [04:50](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=290s) Welcoming the Leader of an $800 Billion Giant
The first conversation features a figure described as the only active CEO in America today who transcends corporate leadership to be looked upon as a true leader for the entire country. His company is worth roughly $800 billion, making it not only the most valuable company in New York, but the most valuable company east of the Mississippi River. With that introduction, the chairman and CEO of JPMorgan Chase, Jamie Dimon, walks out onto the stage.
### [05:44](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=344s) The 1998 Citigroup Shock
The hosts frame the interview as a 20-year retrospective tracking how Dimon transformed JPMorgan Chase from a standard bank into the most systemically important financial institution in the world. They begin the historical journey in 1998, a time when Dimon and his mentor, Sandy Weill, had spent 13 years building a massive modern financial conglomerate. Everyone on Wall Street expected Dimon to be named CEO of Citigroup in short order, but instead, he was abruptly fired and forced to restart his career from scratch. Dimon congratulates the hosts on building *Acquired*, calling it "a great intelligent addition to what we need to learn in society," before explaining that his model differed slightly from Weill's. Dimon wanted to "skinny it down" and shed the parts that weren't strategically central to the bank, a small disagreement about the company's future that ultimately led to his ousting.
### [07:44](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=464s) Fired on a Sunday Afternoon
Dimon recounts the exact emotional texture of the day he was fired. He was in the middle of hosting a recruitment event for 100 college students in his New York City apartment when he was called into a sudden 4:00 PM management meeting on a Sunday. Sandy Weill and John Reed sat him down to announce three management changes, the third of which was asking for his resignation. Knowing the board votes were cast, the press releases were written, and the decision was fully finalized, Dimon accepted it gracefully, wished the management team the best, and went home to break the news to his family.
- Dimon's youngest daughter asked if they would have to "sleep on the streets."
- His middle daughter, obsessed with higher education, anxiously asked, "Can I still go to college?"
- His oldest daughter immediately asked, "Great. Since you don't need it, can I have your cell phone?"
- That night, 50 members of his former management team brought whiskey over to his apartment, creating an atmosphere Dimon describes as "like being at your own wake."
### [10:08](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=608s) The 18-Month Intermission and an Alternative Universe
Following his high-profile firing, Dimon spent roughly 18 months "wandering in the woods" and figuring out his next move. Because his exit agreements took time to sign and the separation was "kind of mean," he took a long vacation before setting up an office in the Seagram building and treating his job hunt like a 9-to-5 role, regularly eating lunch downstairs at the Four Seasons. He explored numerous avenues, including starting his own merchant bank or retiring to teach, but notes he was only 42 years old at the time and wanted to build. In an alternate timeline, Dimon actually went to visit Jeff Bezos, who was hunting for a company president for Amazon. The two hit it off exceptionally well, prompting Dimon to joke that he imagined an alternate universe where he would "never wear a suit again" and live on a houseboat.
### [11:24](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=684s) Turning Down Wall Street for Bank One
Dimon turned down multiple glamorous jobs to run large global investment banks, including an offer from Hank Greenberg to join AIG. He jokes that going from Sandy Weill straight to Greenberg would mean he "had to have his head examined." He also turned down an offer to run Home Depot from founders Ken Langone, Bernie Marcus, and Arthur Blank; during his very first dinner with them in Atlanta, Dimon had to confess that as a lifelong New Yorker, he had never actually stepped foot inside a Home Depot store. Ultimately, a headhunter called him about Bank One. While the bank was troubled and required uprooting his family from New York to Chicago, banking was his natural habitat.
- At the time, Citigroup was a massive $200 billion bank, while Bank One was significantly smaller with roughly a $20 billion market cap.
- Dimon refused to cry over spilled milk, stating "in life you make things what they are."
- To show shareholders he was "100% lock, stock, and barrel" committed to the long-term health of the firm, Dimon famously bought $60 million of Bank One stock using half his net worth right before taking the job.
### [15:05](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=905s) Cleaning Up a Financial Mess
Upon arriving at Bank One, Dimon inherited an incredibly fractured institution. He recalls a brutal analyst report written by Mike Mayo that claimed "even Hercules couldn't fix it." The bank was a messy amalgamation of Bank One, First Chicago, and the National Bank of Detroit, none of which had ever been properly integrated. The company was plagued by multiple conflicting statement systems, processing systems, payment systems, and SAP networks. They were actively losing client accounts, bleeding brands, closing branches, and dealing with massive operational inefficiencies across the board. Facing a fractured management team, Dimon rolled up his sleeves to begin the grueling work of restructuring.
<FollowUp label="Want to hear the next part of Jamie Dimon's turnaround story?" query="Provide part 2 of the transcript walkthrough covering Jamie Dimon's strategy at Bank One."/>
[15:48](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=948s) Inheriting Chaos at Bank One
Upon stepping into Bank One, Jamie Dimon found himself dealing with a highly dysfunctional corporate landscape. The board was fractured into literal tribes from various previous acquisitions, consisting of 21 directors where "11 hated the other 10." Dimon had researched the bank thoroughly beforehand and knew about the internal warfare, but accepted the challenge because "in life you get handed these things and it's not perfect."
Upon taking the job, Dimon met with six of the directors, shook their hands, and gave them a blunt promise: he would tell "the truth, the whole truth, none of the truth—the good, the bad, the ugly," and focus entirely on building a great company rather than playing games. Once the directors left, Dimon found himself completely lost on the executive floor. He knocked on the HR head's door to demand an office and an assistant. Rejecting the traditional corner chairman's office, he chose a space right in the middle of the floor so he could actively see people and stick his head out to communicate.
His first interaction with the management team set an immediate new tone. Meeting them in a conference room featuring plush white carpets, Dimon walked in carrying a cup of coffee. The team told him, "Jamie, we don't drink coffee here for obvious reasons," to which Dimon looked at them, looked at his cup, and flatly responded, "You do now."
- **State of the Bank:** The company's internal systems were terrible, it was actively losing money, and the credit card business—the unit Dimon knew the least about—had completely collapsed.
- **Leadership Philosophy:** Dimon emphasizes that modern professionals mistakenly wait to be handed a flawless situation rather than rolling up their sleeves to fix assets that possess underlying value.
[17:52](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1072s) Rewriting the Culture of Risk
When analyzing what made JPMorgan Chase successful later on, Dimon points directly to a fundamental management understanding of risk. Risk consciousness does not mean avoiding risk altogether; rather, it requires "properly pricing it and understanding the potential outcomes." At Bank One, Dimon quickly discovered that the institution carried more US corporate credit risk than Citibank did, but was masking it through "unbelievably aggressive" accounting that overvalued unprofitable loans.
Panicking slightly at the discovery, Dimon personally audited every single loan on the books, marked them down, increased the bank's reserves, and transparently reported the issue to the board. To turn the ship around, he hired Linda Bamman to oversee credit, granting her full authority to sell and hedge up to $10 billion in loans. This aggressive restructuring reduced Bank One's balance sheet by roughly $50 billion just ahead of an impending recession.
- **Corporate Survivability:** Because of these early maneuvers, the bank weathered the subsequent economic downturn relatively well, with its only major casualty being United Airlines, which went bankrupt and was briefly owned by the bank.
- **The "Don't Blow Up" Philosophy:** Dimon's core operating thesis centers on surviving the worst-case scenario. While other financial institutions willingly edge closer to danger to maximize short-term profits, Dimon prioritizes long-term existence.
[19:41](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1181s) Lessons from Market History
Dimon's absolute refusal to risk a company-ending catastrophe was shaped early by his father, who was a stockbroker. Dimon bought his first stock at age 14 in 1972, observing firsthand how a roaring market could violently reverse. He recalls that the market hit 1,000 in 1968, but by 1974 it had plummeted 45%, causing Wall Street limousines to vanish and popular restaurants to shutter.
This deep respect for market volatility was reinforced by surviving a succession of crashes across the decades: the 1980 and 1982 recessions, the 1987 crash where the market dropped 25% in a single day, and the 1990 real estate crisis that brought giants like JPMorgan, Citi, Chase, and Chemical to their knees. Dimon notes that history always rhymes, pointing to the 1929 market crash where excessive leverage and a universal belief that things couldn't go down ultimately caused a 90% peak-to-trough collapse. "Shit happens," Dimon observes, arguing that rather than trying to perfectly guess when a crisis will strike, a firm must simply ensure it can handle the hit.
- **Historical Banking Valuations:** During the 1990 real estate crisis, major institutions like Chase and Chemical were taken to their knees by losses, lowering their entire corporate valuations to around $1 billion, while Citi dropped to about $3 billion.
- **The Delusion of Sophrication:** When Dimon instituted a "worst-ever" stress test at JPMorgan based on historic 17% credit spread movements, colleagues argued it would never happen again because the market was too sophisticated. In 2008, spreads blew past that to hit 20%, and the bond market froze entirely.
[21:36](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1296s) The Fortress Balance Sheet
To manage the "fat tails"—extreme, low-probability risk events—Dimon relies on his signature operating strategy: the Fortress Balance Sheet. This requires running a company with high margins, deep liquidity, conservative capital structures, and extremely conservative accounting. Dimon openly criticizes modern accounting standards, stating that you can "drive a truck through accounting rules" because they allow companies to upfront questionable future profits while classifying necessary future investments as current expenses.
In banking, building a strong company means being highly selective about the character of your clients and ensuring compensation structures do not incentivize stupid or unethical behavior. Dimon acknowledges that this conservative posture sometimes makes his institutions slightly less profitable than his competitors during booming "good years." Up until 2007, rival banks were jacking up returns by leveraging themselves to deliver a 30% return on equity, but most of those institutions subsequently went bankrupt while JPMorgan survived intact.
> "Confidence. If you lose money as a financial company, I always knew this too... people lose trust and that causes runs on banks."
[25:22](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1522s) The Strategic Merger of Equals
After Dimon ran Bank One from Chicago for four years, the company engineered a massive 2004 merger with JPMorgan Chase. Described at the time as a "merger of equals," Bank One shareholders received 42% of the combined company. Dimon jokes about his irritation when people state he has been running JPMorgan only since the merger, pointing out that he was already running 40% of the combined entity's ultimate footprint from day one.
The transaction featured an incredibly unique, ironclad governance clause designed to protect Dimon's path to leadership. To prevent Dimon from automatically becoming the unified CEO 18 months post-merger, a massive 75% supermajority of the split board—which consisted of eight Bank One directors and eight JPMorgan directors—would have to vote him out. The deal was so intensely scrutinized that JPMorgan was sued for paying too much to acquire Dimon, while Dimon was simultaneously sued by his own side for not taking a high enough premium.
- **Corporate Valuations at Play:** Years prior to the deal, Bank One was valued at roughly $25 billion while JPMorgan Chase sat around $80 billion to $90 billion. Over four years of Dimon's leadership, Bank One's stock doubled, bringing them squarely into target range for a strategic combination.
- **The Brand Asset:** While the JPMorgan name carried an elite, "Tiffany" brand status, Dimon explicitly did not factor the brand's aesthetic value into his baseline deal calculations, focusing purely on cold business logic.
- **Synergistic Overlaps:** Both firms possessed massive consumer branches and underperforming credit card operations that required scaling, while Bank One's corporate client base served as the perfect pipeline for JPMorgan's premier investment banking services.
[28:56](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1736s) Pulling Back Before the 2008 Crash
By 2006, Dimon was officially serving as Chairman and CEO of the combined JPMorgan Chase. While Wall Street was gripped by a booming, "go-go baby" euphoria reminiscent of the 1980s, Dimon noticed structural cracks forming in late 2006, specifically within quant portfolios and subprime mortgages. Recognizing the danger, he moved decisively against the prevailing incentives of the era and pulled JPMorgan back from subprime exposure, while aggressively stockpiling massive reserves of liquidity.
Dimon attributes the severity of the subsequent 2008 crash to a massive regulatory and accounting loophole. Under legacy Basel I rules, major investment banks were permitted to expand their leverage from a historic 12-to-1 ratio up to an astronomical 35-to-1 ratio. Wall Street became dangerously saturated with highly leveraged bridge loans and collateralized mortgage obligations (CMOs). When the mortgage market inevitably cracked, these over-leveraged houses collapsed under their own weight, whereas JPMorgan remained standing due to its lower leverage and fortress-like liquidity reserves.
- **The Bridge Loan Bubble:** In 2007, the collective Wall Street bridge loan book reached a staggering $450 billion. By comparison, in 2026, the entire market's bridge book sits at a highly conservative $40 billion.
- **Leverage Metrics:** JPMorgan approached the financial crisis maintaining roughly one-third of the leverage ratios carried by its peer investment banks.
[30:58](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1858s) Overhauling Incentives and the Danger of Leverage
Jamie Dimon stresses that ethical boundaries must never be compromised for financial incentives, stating that bankers should always treat clients how they themselves would want to be treated. Upon taking the helm, he systematically dismantled high-risk compensation structures and side deals that were standard across Wall Street. He explains that senior investment bankers were previously being paid based on specific private, short-term transactions lasting three to five years. At JPMorgan Chase, this practice was ended to eliminate "winks," "nods," and misalignment with the firm's broader risk management goals.
Dimon details how excessive leverage coupled with the wrong compensation plan inherently incentivizes reckless behavior. In securitization and mortgage books, a trader with 30 times leverage who is entitled to 20% of the profits will inevitably push leverage to 40 times just to add 25% to their personal bonus. To neutralize this threat, Dimon eliminated these 20% profit pools and capped the extreme leverage, even though the structural changes caused some employees to leave the company for competitors who still maintained the old reward structures.
- **Client Principle:** Dimon's guiding philosophy remains: "Don't do the wrong thing to the client."
- **Leverage Math:** Moving from 30x to 40x leverage could structurally increase a banker's bonus by roughly 25%.
- **Cultural Shift:** Eliminated isolated profit pools to prevent senior bankers from prioritizing personal deal metrics over company-wide safety.
[32:33](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1953s) The Bear Stearns Emergency and the $2-a-Share Acquisition
The timeline fast-forwards to the evening of Thursday, March 13, 2008. While celebrating his birthday with his family at AVA on 47th Street—his parents' favorite restaurant—Dimon received an emergency phone call from Bear Stearns CEO Alan Schwarz. Bear Stearns' stock had closed at $57 that day (down from $150 a few months prior), and Schwarz stated, "Jamie, I need $30 billion tonight before Asia opens." Dimon, shocked by the request, advised Schwarz to contact Treasury Secretary Hank Paulson and New York Fed President Tim Geithner. Dimon immediately left his dinner, returned to the office, and rallied a team of roughly 100 employees who rushed back to work in the middle of the night.
Because neither JPMorgan nor the Federal Reserve could legally or technically lend $30 billion directly to Bear Stearns, they structured an unconventional arrangement. The Fed lent the capital to JPMorgan, which then utilized Bear Stearns' own assets as collateral to create a critical one-day liquidity bridge. Over the ensuing weekend, thousands of JPMorgan employees conducted intense, around-the-clock due diligence. They audited every loan, asset, derivative, derivative contract, lawsuit, and HR policy before acquiring the failing investment bank for $2 a share. Dimon recalls that while Hank Paulson questioned why they were paying anything at all, Dimon knew he needed a positive shareholder vote and wanted to mitigate the impending wave of inevitable lawsuits from furious Bear Stearns investors.
- **The Price Collapse:** Bear Stearns stock plummeted from $150 to $57, and ultimately to a acquisition price of $2 per share within days.
- **The Weekend Rush:** Thousands of JPMorgan employees performed comprehensive due diligence on Bear Stearns' entire balance sheet in less than 72 hours.
- **Underlying Value:** JPMorgan paid $1 billion for a firm recently valued at $20 billion, effectively getting Bear Stearns' corporate headquarters (valued at $1 billion on the balance sheet) for zero.
[35:02](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2102s) Government Lawsuits and the Erosion of Trust
The financial aftermath of the Bear Stearns rescue proved deeply painful for JPMorgan. Despite historical estimates that the long-term cost of unwinding Bear Stearns was between $15 billion and $20 billion, Dimon clarifies that the immediate pain came from a $12 billion asset write-off. The situation worsened when the federal government subsequently sued JPMorgan over bad mortgages that Bear Stearns had originated years before the acquisition. Offended by the litigation, Dimon notes that one administration's handshake deal often means nothing to the next. The litigation ultimately forced JPMorgan to pay a massive $5 billion settlement for Bear Stearns' legacy mortgage malfeasance.
This experience led Dimon to famously declare that he would never trust the government in the same way again. He recalls a dramatic meeting where he went to settle the mortgage dispute with Attorney General Eric Holder. Accompanied by his lead director, Dimon completely disarmed Holder—who expected an aggressive corporate defense—by stating, "Eric, I am here to surrender." Knowing that a federal criminal indictment could instantly sink his company, Dimon chose to surrender rather than jeopardize his firm or the country. He points out that 80% of what the government was demanding actually stemmed from bad behavior at Bear Stearns and Washington Mutual (WaMu), not JPMorgan Chase. Despite the bitter lesson, Dimon admits that his core patriotism means he would still answer the call if the country faced a systemic emergency, though he would jokingly structure a merger agreement requiring a "75% vote of Congress not to sue."
- **The Litigation Cost:** The government forced JPMorgan to pay $5 billion exclusively for legacy mortgages written by Bear Stearns.
- **The "Surrender" Strategy:** Dimon chose strategic surrender over fighting a federal indictment that carried systemic existential risk for the bank.
- **Reputational Upside:** The conversation notes that despite the immediate paperwork losses, anchoring the system during that weekend built an unparalleled institutional reputation that underpins the bank's modern multi-hundred-billion-dollar valuation.
[38:28](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2308s) The Strategic Acquisition of Washington Mutual
Six months after the collapse of Bear Stearns, Washington Mutual went under, prompting another acquisition by JPMorgan Chase. Unlike the chaotic and legally punishing Bear Stearns deal, WaMu proved to be an outstanding, highly strategic acquisition. Seized and bought just one week after Lehman Brothers went bankrupt—a time when most corporate boards were entirely paralyzed by systemic fear—the acquisition expanded JPMorgan's retail footprint into lucrative, high-growth states like California, Nevada, Georgia, and Florida via 2,300 branch locations.
JPMorgan bought WaMu at a massive $30 billion discount to its tangible book value. Because they strategically left WaMu's corporate debt behind, that $30 billion discount perfectly offset the roughly $30 billion in mortgage losses that JPMorgan’s risk teams expected to write off. To guarantee a wide margin of safety, Dimon executed an unprecedented move by immediately raising $11 billion in fresh equity capital from the public market within 48 hours of the deal. Though the bank did not explicitly need the cash, Dimon's deep fiscal conservatism dictated that JPMorgan's balance sheet should look just as strong after absorbing WaMu as it did before.
- **Branch Footprint:** The acquisition added 2,300 retail branches in vital states where JPMorgan lacked a strong presence.
- **Financial Architecture:** Bought at a $30 billion discount to tangible book value, matching the expected asset write-downs.
- **Capital Raise:** Secured $11 billion in new equity during the absolute peak of global market panic based on long-term shareholder trust.
- **Integration Speed:** JPMorgan completed the monumental task of consolidating all of WaMu's IT, branch, and payment systems in just nine months.
[41:05](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2465s) Modern Financial Risks: From Accounting Tricks to Cyber Warfare
Dimon notes that while modern banks and regulators are vastly more conservative than they were in 2008, the financial sector remains perpetually vulnerable to aggressive accounting and unhedged risks. He severely criticizes the regulatory accounting convention known as "held to maturity" (HTM), which permits banks to hide heavy interest rate losses by not marking sovereign treasuries to market. History shows that new, unseasoned financial products are almost always the catalysts for systemic blowouts, citing historic market failures ranging from the equities crash of 1929, to early option and equity derivative crises, up through Long-Term Capital Management (LTCM) and quantitative trading disruptions.
When questioned whether the booming $2 trillion private credit market represents the next systemic bubble, Dimon remains skeptical. While noting its rapid growth contains pockets of inexperienced operators, he highlights that the product is highly favored by clients and lacks the fragile, hyper-leveraged structures that defined the subprime mortgage crisis, which featured a $9 trillion market footprint and over $1 trillion in direct losses. Instead, Dimon reveals that his primary anxieties center on inflated asset prices—noting that the current S&P 500 P/E ratio of 23 leaves a long way to fall compared to a historically safer P/E of 15—and the existential threat of cyber warfare. JPMorgan spends a staggering $800 million annually on cyber defense, but Dimon warns that national infrastructure grids, water supplies, and military networks remain dangerously under-protected against sophisticated state-sponsored cyber attacks from nations like China and Russia.
- **Market Micro-Structure:** Subprime mortgages represented a $9 trillion market with $1 trillion in real losses, whereas private credit sits at a less systemic $2 trillion.
- **Valuation Risk:** Characterized current equity markets as high-risk, citing compressed credit spreads and an elevated market P/E ratio of 23.
- **Cyber Defense Budget:** JPMorgan allocates roughly $800 million per year specifically to safeguard its digital perimeter and collaborate with federal intelligence agencies.
[44:11](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2651s) The 2023 Regional Banking Crisis and Concentrated Deposits
Turning to the regional banking panic of 2023, Dimon analyzes the sudden failures of Silicon Valley Bank (SVB) and First Republic Bank. He clarifies a widespread economic misconception, noting that the true killer of these institutions was not merely "uninsured deposits," but rather "concentrated deposits." In the case of SVB and First Republic, a tightly knit network of a few hundred to a thousand venture capital firms panicked simultaneously, instructing their entire portfolios of startup clients to pull their capital out immediately.
This modern herd behavior resulted in a catastrophic, unprecedented run, causing Silicon Valley Bank to lose an astonishing $100 billion of its $200 billion deposit base in a single business day. Dimon points out that these structural vulnerabilities were exacerbated by poor internal management: neither bank maintained adequate liquidity, neither had properly pre-posted collateral at the Federal Reserve's discount window, and both carried severe, unhedged interest rate exposures that were masked from plain sight by held-to-maturity accounting metrics.
- **The Deposit Run:** SVB lost 50% of its total deposits ($100 billion out of $200 billion) in a single day due to venture-capital-driven concentration.
- **Operational Failures:** Both regional banks failed to post collateral at the Fed beforehand, leaving them unable to access emergency liquidity when the run began.
- **Accounting Distortion:** Held-to-maturity rules allowed banks to hide devastating paper losses on safe assets like US Treasuries, masking structural erosion in tangible book value.
[45:44](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2744s) The Fall of Silicon Valley Bank and First Republic
Jamie Dimon describes how quickly a bank's financial health can slide into "judgment land" when marking assets to market, noting how a book value of 100 can suddenly plunge to 50, 40, or 30 cents on the dollar. He points out that the regulators inadvertently set a trap for these institutions by predicting that interest rates would remain low forever. Believing this, banks loaded up on 3% mortgages. When interest rates spiked to 5%, those same mortgages rapidly lost their value, trading at 50 or 60 cents on the dollar. Dimon clarifies that both Silicon Valley Bank (SVB) and First Republic Bank took on too much interest rate exposure—a fact known to both their respective managements and the regulators—and that it was entirely fixable. JPMorgan Chase had been competing in the tech space and watched SVB closely, later using the aftermath of its collapse to learn how to better serve the venture capital ecosystem. Today, JPMorgan has established a full campus in Palo Alto, hired 500 innovation bankers, and aggressively covers venture capital companies, though Dimon admits with a touch of humility that "we're not as good as they are yet."
Dimon then shares the story of how JPMorgan ultimately acquired First Republic Bank. He reveals that he personally called Treasury Secretary Janet Yellen ahead of time to warn her that First Republic, along with one or two other institutions, was in deep trouble. Dimon offered to take a look and potentially buy it early to eliminate the issue, but authorities "waited a little bit too long," turning the struggling bank into a "little melting ice cube." Once JPMorgan finally stepped in to purchase it, the panic ceased immediately. Within a couple of days, JPMorgan hedged all of First Republic's risk exposures, wrote down the bad assets, and merged the operations. Despite the bank's failure, JPMorgan retained some of First Republic's top talent and adopted their highly successful, high-touch "single point of contact" concierge service model for high-net-worth clients. This acquisition laid the groundwork for the brand-new "JP Morgan Financial Centers," the bank's first consumer effort carrying the explicit JPMorgan branding rather than Chase.
- JPMorgan Chase established a campus in Palo Alto and hired 500 innovation bankers to compete in the venture capital ecosystem.
- Dimon directly contacted Janet Yellen regarding First Republic's financial distress before the acquisition.
- First Republic's high-end concierge model inspired the creation of the new JP Morgan Financial Centers, with 20 currently open and a long-term goal of 300 over the next 20 years.
[47:58](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2878s) How JPMorgan Separated from the Pack
When asked how JPMorgan Chase managed to separate itself from its competitive set and become a "completely different animal," Dimon explains that the underlying strategy mimics that of a traditional community bank, with the exception of their massive global investment banking operation. In a small community bank, the staff knows your business, your consumer account, and handles your private affairs through a trust company without needing a Salesforce CRM because their relationship management is kept entirely "up here" in their heads. Dimon emphasizes that JPMorgan's businesses are designed to fit together and feed one another seamlessly; middle-market clients use investment banking products, and consumer clients utilize foreign exchange services. He contrasts this focused approach with Citigroup’s historical strategy under Sandy Weill. Citigroup accumulated extraneous businesses that did not fit together, such as consumer finance, life insurance, property casualty, and even truck leasing through American General. Dimon notes that it is incredibly difficult for leadership to truly understand the underlying risks when a company accumulates random "hobbies."
A fundamental driver of JPMorgan's structural advantage is its efficiency ratio. The interviewer highlights that for every dollar JPMorgan makes compared to its competitors, it keeps an extra 15 cents as profit. Dimon attributes this compounding success to a philosophy of continuous investment through the economic cycle and a strict focus on "actual economics... not the accounting of what we do." He notes that while it would be easy to artificially boost short-term margins by cutting billions of dollars in marketing or freezing branch openings, doing so would ultimately destroy long-term growth. Dimon half-jokes about their annual Investor Day, stating that he sits back and watches his team give presentations, thinking, "Oh god, we're just giving away too many secrets here." He draws an analogy to the business built by Howard Schultz at Starbucks, praising the consistency, curiosity, heart, and branch-by-branch focus required to plow through mistakes. He also uses a sports analogy, comparing business culture to Tom Brady's legendary work ethic during practice, stating that a sports team full of jerks who don't give their best will almost never be great.
- JPMorgan's efficiency ratio allows the firm to keep 15 cents more of every dollar as profit compared to its core competitors.
- Dimon emphasizes a "fortress balance sheet" and "fortress accounting" while avoiding corporate "hobbies."
- Continuous long-term investments are focused heavily on three areas: people, branches, and technology.
- Global Investment Bank leaders Doug Petno and Troy Rohrbaugh have successfully expanded commercial banking branches across Europe.
Reflecting on his tenure, the interviewer notes that every other prominent financial leader from the 2008 era has long since retired, yet Dimon is still working as hard as ever. Dimon begins by thanking his wife, Judy, who was present in the audience, noting that she has suffered through all of it with him and that he could not have done it without her. He attributes his enduring work ethic to his heritage as the grandson of Greek immigrants who never finished high school. He explains that he was raised with a foundational "Greek ethic" centered around having a purpose—whether in art, science, the military, business, or teaching—and giving it your absolute all rather than being someone who complains. He adds that he was raised to treat everyone properly and to stand up to bullies. In his personal "hierarchy of life," family comes first, followed by his country—which he calls the "indispensable nation" for pioneering freedoms of speech, religion, and enterprise—and finally his purpose, which is channeled through his leadership at the bank.
Dimon expresses that he gets a tremendous "kick" out of helping cities, states, schools, and employees through JPMorgan Chase. He jokes that his family does not want him at home every day anyway, and notes that he does not play golf. When one of his daughters told him he needed hobbies, he countered that he already has them: family travel, barbecuing, history books, hiking, wine, and a newfound appreciation for whiskey. He explicitly rejects the idea of a quiet retirement, stating that he refuses to just "twiddle my thumbs and smell the flowers." When he eventually leaves his current role, he expects to teach, write a book, or find another active pursuit. To close out the interview, the interviewer asks if Dimon agrees that there is only one job in the world that could possibly impact the country on a bigger scale than the one he currently holds, hinting at the presidency. Dimon smiles and responds, "Right now? Yeah," before concluding the session to warm applause.
- Dimon credits his foundational values to his Greek immigrant grandparents and his parents.
- His self-stated hierarchy of life places family first, country second, and his corporate purpose third.
- His personal hobbies include history, hiking, family travel, barbecuing, wine, and whiskey.
[58:30](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3510s) Late Night with DealBook and Acquired
Following Jamie Dimon's departure from the stage, the event transitions to a late-night talk show format blending *DealBook*, *Squawk Box*, and *Acquired*. Financial journalist Andrew Ross Sorkin is introduced to the stage to join hosts Ben Gilbert and David Rosenthal. Sorkin jokingly slides behind the desk, prompting the hosts to lightheartedly ask why he is there, given that they had already recorded a comprehensive three-hour episode on the history of *The New York Times* a few years prior. Sorkin quips that since he grew up at the *Times*, he wanted to help them out with notes, research, and questions for their upcoming segment.
To test the hosts' knowledge, Sorkin institutes a quick New York history pop quiz for the stage and the audience. He fires off a series of rapid questions about the heritage of *The New York Times*, querying its founding year and historical milestones. Sorkin corrects a near-miss answer regarding an early co-founder who once famously defended the newspaper's building from the rooftop with a gun during the draft riots, noting that it was Henry Raymond rather than Adolph Ochs, though he awards style points for the guess since Ochs later bought the paper from Raymond. The trivia game concludes by celebrating the naming of Times Square after the iconic publication, setting the stage for Sorkin to introduce the next guest of the evening, modern New York Times Company CEO Meredith Kopit Levien.
- *The New York Times* was founded in the year 1851.
- Co-founder Henry Raymond historically defended the newspaper building from the rooftop with a gun.
- Times Square was explicitly named after *The New York Times* newspaper.
### [01:01:13](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3673s) The Transformation of The New York Times
The conversation shifts to a live interview with Meredith Kopit Levien, CEO of The New York Times Company. The hosts set the stage by reflecting on how much has changed since their 2021 podcast episode about the company. They recall how in 2008, the Times was "on the brink of death," famously having to sell its headquarters building just to survive. Today, it has completely turned its fortunes around, standing as the largest digital subscription newspaper in the world and the only remaining standalone global newspaper company. The company boasts a market cap near an all-time high of almost \$10 billion, prompting lighthearted jokes from Meredith as the hosts heap on the praise without initially asking a formal question.
When asked about what has evolved since the pivotal 2014 Innovation Report that reshaped their long-term trajectory, Meredith shares striking growth metrics. In 2021, the Times had roughly 5 million subscribers; today, they are closing in on 12 million. Revenue, profit, and journalistic impact are all expanding. Every week, between 50 to 100 million people visit the Times website and apps, around 20 million consume their podcasts and newsletters, and over 150 million people have registered with the platform.
- **Subscription Scale:** Growing from ~5 million in 2021 to nearly 12 million.
- **Physical Newspaper Status:** The print edition now accounts for "well inside of 30%" of the business, sitting closer to 25%, though Meredith stresses it still has a long life ahead because readers love it.
- **Cultural Shift:** The organization shifted from playing defense in 2014 to playing offense today, aiming to be the "essential subscription for curious people everywhere."
---
### [01:05:17](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3917s) Recreating the Bundle: Build vs. Buy Strategy
The hosts observe that by expanding into games, sports, recipes, and product reviews, The New York Times has effectively recreated the classic, multi-faceted Sunday newspaper bundle for the digital era. They frame the Times as "the largest first party content company by subscriber count in the world." The hosts point out that historical corporate expansions and acquisitions in media frequently fail, and they ask Meredith why her team's bets are actually working.
Meredith outlines a clear three-part strategic framework: being the world's best news destination, offering market-leading lifestyle products to fuel people's passions, and tying it all together into a connected bundle. She references three major acquisitions during her tenure that perfectly anchor this strategy. The overarching magic is that the distinct pieces cross-pollinate; a user might log on just to play a game, only to end up reading a deep-dive piece on the war in Ukraine.
- **The Wirecutter:** Described as a modern-day Consumer Reports for product reviews, it drove roughly \$1 billion in commerce transactions over the past year.
- **The Athletic:** Possesses the world's largest sports newsroom with over 550 journalists and represents the fastest-growing audience segment on the Times platform.
- **Wordle:** A massive cultural gaming phenomenon acquired during the exact same week as The Athletic, bought for an undisclosed single-digit million sum.
---
### [01:09:06](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4146s) The Human Element of Journalism in the Age of AI
The discussion moves toward the rapidly shifting technological landscape, noting that while the Times relies entirely on human curation, much of the tech-centric audience now uses AI tools for daily tasks. Meredith remains highly optimistic, asserting that "journalism, particularly journalism about important things going on in the world, is first and foremost a human endeavor." She contrasts sending a drone to a battlefield with deploying a human reporter who can look into a victim's eyes and capture the emotional weight of a crisis.
Rather than viewing AI as a threat to their core product, Meredith sees it as a powerful "force multiplier." Times journalists are currently using AI to parse massive troves of public documents to uncover stories faster, and the company leverages automated voices to make written articles accessible on the go. She remarks that AI is a fantastic tool when appended to 3,000 human beings creating content, provided that the foundational IP is legally protected. This prompts the hosts to ask directly about their ongoing copyright lawsuit against OpenAI and Microsoft.
- **OpenAI & Microsoft Lawsuit:** The Times filed suit because tech companies are spending hundreds of billions on compute, power, and talent, but are failing to pay fair value for the creative content used to train their models.
- **Broad IP Implications:** Meredith emphasizes that this is not just a journalism issue, but a critical fight for "anybody who makes creative work" and foundational to American competitiveness.
- **Commercial Alternative:** She highlights their recent partnership with Amazon as an example of a sustainable, fair value exchange where the Times retains strict control over its content.
---
### [01:13:39](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4419s) Addressing Bias and Navigating Media Evolution
The hosts push into more sensitive territory, asking Meredith how she addresses the perceived "anti-tech" or "anti-business" bias that some critics associate with the publication. Meredith gently challenges the premise, stating firmly that "it's not a thing." She explains that the core mission of the Times is to "pursue the truth wherever it may lead," admitting that the destination is sometimes uncomfortable. To combat inherent bias, the company maintains a massive institutional standards operation.
Addressing tech reporting specifically, Meredith explains that modern tech giants hold a staggering amount of power and influence—comparable to entire nations—meaning they naturally command intense journalistic scrutiny. To close the segment, she shares a personal anecdote from her early days at the company 12 years ago, recalling how she told reporter Andrew Ross Sorkin right before an event, "Don't talk about the paper," emphasizing that they had to transcend being just a print company. Today, whether through text, video, or massive hit podcasts, the focus is entirely on building intimate, deep relationships with the audience.
- **Editorial Safeguards:** Every single story published by The New York Times is edited by at least two people to ensure factual verification.
- **The Power of Tech:** The intense coverage reflects tech's rise from a single industry 15 years ago to commanding the vast majority of US market capitalization today.
- **Podcast Roster:** Hit audio shows like *The Daily*, *The Ezra Klein Show*, and Ross Douthat’s *Interesting Times* act as highly effective vectors for deepening reader engagement and reaching entirely new audiences.
[01:18:10](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4690s) Casual Conversations and the Banter of Podcasts
When a reporter goes on *The Daily* to discuss a story they have just published on the homepage, they are doing two things simultaneously: explaining the news in a casual, friendly manner, and exposing the audience to how the journalism actually came together. This process acts as a crucial trust-building exercise, revealing the immense lengths to which the reporters go to present topics fairly and deeply.
The casual banter of podcasts functions as genuine entertainment, keeping listeners engaged while instructing them. Shows like *Hard Fork*, hosted by New York Times reporter Kevin Roose and Platformer's Casey Newton, demonstrate the power of conversational storytelling. This narrative style ultimately helped the *New York Times* break free from the "tyranny" of how traditional news articles had to be rigidly presented in a newspaper, introducing a more informal, wider style that has since spilled back into standard text articles.
---
[01:20:16](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4816s) A Live, Custom Wordle Game
The conversation shifts to games as the hosts reveal they asked the team at the *New York Times* to create a custom, *Acquired*-themed Wordle puzzle. Admitting that she is not very good at Wordle and that her mom "smokes" her every time, the guest confesses she actually would have preferred to play *Connections*, a game she is much faster at.
The hosts provide a hint, noting that the puzzle's solution is deeply related to a canonical *Acquired* episode, making any standard favorite starter word a great place to begin. The guest plugs in her usual starter word, though she quickly laments that the initial result "sucked." Following a few more attempts and another hint—that the answer is the last name of a founder of a predecessor company to one of the world's largest retailers—the solution is successfully reached, prompting a round of applause for Meredith Copit Levien.
---
[01:22:50](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4970s) Audience Participation and the Arrival of Barry Diller
Before bringing out the final guest of the evening, the hosts engage the audience with a piece of trivia, asking what the most listened-to episode in *Acquired*'s 10-year history is. Audience members and notable guests offer up guesses, including Christina Cassiopo (co-founder of Vanta) guessing the Hermès episode, and Ben Clymer (founder of Hodinkee) guessing the Rolex episode. However, it is Howard Schultz who correctly identifying his own appearance on the Starbucks episode—which garnered 1.3 million downloads—as the top spot.
The final guest of the night is Barry Diller, the chairman of IAC. Over his illustrious 60-year career, Diller has led an incredible number of companies within the media and technology universes, including Fox, ABC, Paramount, Expedia, Tinder, Match.com, QVC, and Ticketmaster. Alongside his wife, Diane von Fürstenberg, Diller is also recognized as one of New York's most legendary citizens for his philanthropic contributions to the city, such as funding the High Line and Little Island.
- **Starbucks Episode Downloads:** 1.3 million downloads.
---
[01:26:41](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5201s) Parking in New York and the Old Hollywood Era
Diller generates big laughs from the crowd immediately upon sitting down, jokingly demanding to know why the previous guest received a seat pillow while he did not. The banter continues as Diller reveals that he drove himself to the event, noting that he drives everywhere in New York and typically finds parking by squeezing into empty spaces near fire hydrants or other barriers. When asked if gifting an entire island to New York grants him special parking privileges, Diller cracks, "No, no, no. I get tickets... someday I'll pay for them."
The conversation turns to the first chapter of Diller's legendary career, which began in 1961 in the mailroom of the William Morris Agency. This was the era of "old Hollywood" dominated by the traditional studio system and larger-than-life moguls who were on their last legs. Diller reminisces about meeting characters like Darryl Zanuck, the founder of 20th Century Fox, who used to sit in a massive 500-seat projection room smoking a 20-foot cigar. At the time, Diller was a young executive at ABC buying movies for television, and he jokes that Zanuck only kept his various girlfriends around by putting them in "rotten, horrible Fox movies" that Diller was pressured to buy.
---
[01:29:33](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5373s) The Physical File Room and a Foundation in Entertainment
Diller represents a rare breed of executive who successfully crossed the chasm from media into technology. Reflecting on his beginnings, Diller notes that while tech companies do not have mailrooms, the William Morris Agency possessed a massive physical file room containing roughly 50 file cabinets. From the age of 19 to 22, Diller systematically read the entire file room from A to Z. Because William Morris was the oldest and largest talent agency in the world—having been in business for 70 years at that point—the room held the entire raw history of the entertainment industry.
This massive undertaking mirrors the primary research style of the *Acquired* podcast. Diller explains that letting those endless physical files and messages wash over him allowed his brain to find patterns and truly understand how the business worked. He was able to read the literal history of Elvis Presley from the exact moment he recorded his first song through his entire career. Diller notes that "there's no school you could go to that would ever teach you that."
---
[01:31:52](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5512s) The "Movie of the Week" and Climbing the Ranks at ABC
After his time at the William Morris Agency, Diller moved to ABC during the 1960s and 1970s, a period when the network was a massive talent magnet alongside figures like Roone Arledge and Bob Iger. At the time, there were only three television networks capturing 100 percent of the viewing audience. ABC was the youngest and least established of the three, meaning it was "run like a candy store." If an employee wanted responsibility, they could simply take it and take risks on ideas that were deemed highly dangerous. This environment allowed Diller to become a vice president in charge of movies at the unprecedented age of 25 and a half.
While at ABC, Diller pioneered a concept called the "Movie of the Week," creating original movies specifically for television—an idea everyone else in the industry predicted would fail. Operating like a total startup within the network, Diller began as the sole employee of the initiative but eventually built it up to produce 75 movies a year. He notes that learning how to manage people requires doing the fundamental groundwork yourself to truly understand the tasks that need to be done.
- **Movie production growth:** Expanded from a single block to 75 television movies per year.
- **Historical Production Costs:** Movies were made for roughly $500,000 each, contrasting sharply with modern one-hour television episodes that can cost $10 million.
- **Promotion:** Diller was eventually promoted to oversee all series programming, despite personally disliking the static, unchanging nature of half-hour comedies and hour-long dramas.
[01:35:36](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5736s) From Paramount Rescue to Studio Chairman
Even though he had enjoyed success in television, the speaker felt that the rug was close to being pulled out from under him due to some serious challenges. Rescue arrived over the horizon in the form of Charles Bluhdorn, the owner of a massive industrial conglomerate called Gulf & Western. The conglomerate had acquired Paramount Pictures, and the speaker had crossed paths with Bluhdorn while selling movies to the studio. Gulf & Western had a wild trajectory, starting out making car bumpers before expanding into 100 different businesses—including Puerto Rican sugar. The joke was that they did practically everything short of grave digging, though the speaker quips that they *did* make *The Godfather* in graves, "but they didn't really do that." It was a golden age of conglomerates in the 1950s and '60s, and Gulf & Western was arguably the largest.
Bluhdorn, who was only in his late 30s or early 40s at the time, repeatedly tried to recruit the speaker to work for Paramount. The speaker kept refusing because he genuinely disliked Paramount's management. One day, Bluhdorn ordered him up to his office and abruptly announced, "Okay, I'm going to make you chairman of Paramount." The speaker protested that the idea was completely insane: "Charlie, this is insane. I'm a vice president of ABC in television. Paramount is a movie company. You can't do that." Bluhdorn simply fired back, "Oh, yes, I can." Taking the job meant the speaker would become the boss of the legendary Bob Evans. Still hesitant, the speaker consulted Leonard Goldenson, the founder and chairman of ABC who had once worked as a line person at Paramount. When told of the offer and the speaker's hesitation, Goldenson bluntly remarked, "If you're that stupid, I'll fire you."
[01:38:02](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5882s) Beating the Odds with *Saturday Night Fever*
Taking over one of the five major movie studios in his 30s was unprecedented, but the transition was far from smooth. For the first two years, the speaker admits he "kind of failed" while trying to figure out how to run the studio his way, bringing him dangerously close to losing his footing. The ultimate turnaround came when Paramount released *Saturday Night Fever*, followed immediately by *Grease*. *Saturday Night Fever* featured John Travolta in his first major film role. Travolta was transitioning from the television comedy series *Welcome Back, Kotter*, and Hollywood's elite movie snobs scoffed at the casting. They "kind of peed on the people in television," questioning how a TV sitcom actor could lead a real theatrical motion picture.
The tension peaked on the night of a small, semi-private premiere at the famous Grauman's Chinese Theatre on Hollywood Boulevard. The speaker had invited all of Hollywood because he was incredibly proud of the film—viewing it as his "last gasp"—and desperately needed it to succeed. The screening was scheduled for 8:00 PM, but by 7:45 PM, the theater was more than half empty, sitting at about 40% capacity. Paramount's old-school publicity head walked over to the speaker and delivered a brutal verdict: "Well, you know, you put this Travolta and that kid just doesn't put asses in the seats." The speaker was mortified, thinking, "Oh god." However, ten days later, the movie officially opened to massive lines wrapping around blocks across the country. While Hollywood snobs initially refused to show up, regular Americans lined up happily because the movie earned phenomenal reviews.
- **Paramount's No. 1 Status:** The historic run of hits included *Saturday Night Fever*, *Grease*, *The Godfather Part II*, the original *Star Trek* movie, and *Indiana Jones*.
- **The Institutional Shift:** Paramount beat the odds by moving away from relying on packages assembled by agents (which paired a star director with big actors) and instead focusing heavily on internal material development.
- **The Script's Origin:** *Saturday Night Fever* was adapted from a *New York Magazine* article by Nick Cohn titled something like the adventures of a Saturday night. It was later revealed to be entirely fabricated fiction, but Paramount bought the rights and developed the script from it anyway.
- **Development Volume:** At any given time under this new system, Paramount kept roughly 90 projects in various stages of development.
[01:42:01](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6121s) Partnering with Rupert Murdoch
Eventually, the speaker felt "loose in the seat" at Paramount and grew eager to build something new. He envisioned creating a fourth television network to rival CBS, NBC, and ABC, but the project was killed at Paramount when Gulf & Western pulled the financing due to a minor recession around 1972 or 1973. Instead, he moved to Fox, where Rupert Murdoch followed a few months later by purchasing an interest in the company. The speaker notes he was "very lucky" to have simply inherited Murdoch as a partner. Acknowledging that Murdoch is a deeply controversial figure today—clarifying that he personally dislikes Fox News—the speaker still praises him as "one of the great entrepreneurial gamblers."
Murdoch had built an empire starting from a tiny, small-town newspaper in Adelaide, Australia, eventually dominating the entire country's print landscape before moving to the UK and doing the same. The speaker notes that Murdoch genuinely loved "betting the company," operating as a high-stakes gambling entrepreneur who routinely took massive risks to disrupt the establishment. Despite this, he was an ideal boss because he granted absolute authority and responsibility. In eight years of working together, Murdoch never made a single operating decision at Fox, and the duo had only one disagreement.
- **Global Footprint:** Murdoch created media empires across multiple continents, including a massive presence in Asia via Star TV in India, where he played a pivotal role in televising IPL cricket.
- **The Management Debate:** The speaker strongly believes managers should never "bet the company" on a single venture if a failure could drag a healthy company down. He notes that doing so requires a rare brand of addictive gambler's guts unique to people like Murdoch.
[01:46:21](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6381s) The Leap of Independence and a QVC Epiphany
Despite his aversion to Murdoch's extreme risk-taking, the speaker was inspired by him to leave corporate life and become an independent entrepreneur. At 49 years old, he had spent 30 years as a "corporatist" and was independently wealthy, "fat and happy" at Fox. However, he was struck by a binary realization: you are either capable of creating something on your own, or you are not. He suffered from the common delusion corporate executives face—feeling like the company belongs to you when it doesn't. He forced himself out the door to test his independence, overcoming petty anxieties like losing access to a corporate private jet and having to stand in regular airport lines.
He left Fox with no clear plan, determined only to avoid repeating himself by running another traditional movie or TV studio. He went on a cross-country road trip to see parts of America he had never experienced. While on the road, his wife, iconic dress designer Diane von Furstenberg, called him and insisted, "You have to go to Westchester, Pennsylvania, and see QVC." The speaker originally resisted, scoffing at the idea of visiting a home shopping network, but ultimately went. What he discovered there was a primitive but transformative convergence of televisions, telephones, and computers working in unison.
Watching a small stage where items were showcased next to a green screen, the speaker watched computer monitors track incoming calls in real-time. The sales data on the screen would rise and fall rapidly with consumer demand. It was a genuine epiphany. Until that moment, he had only known screens as a medium for telling stories. Seeing them used for real-time interactive commerce completely blew his mind. Two months later, an opportunity arose to buy into QVC. He took the leap, even though the New York and Hollywood communities widely mocked him and thought he had entirely lost his mind for moving to Westchester.
- **The Timing Advantage:** Entering QVC in 1993 allowed him to master digital connectivity and interactivity two full years before the internet was widely adopted by the public in 1995.
- **IAC Corporate Legacy:** This foundational tech knowledge later allowed the speaker to build IAC, an entity that would start, buy, or sell over 150 companies, including Expedia, TripAdvisor, Angi (Angie's List), Vimeo, Ticketmaster, Tinder, and Match.com.
- **The "Forrest Gump" Comparison:** The host jokingly compares the speaker's historic journey from the William Morris mailroom through the heights of old media and big tech to a "media and tech Forrest Gump." The speaker laughs, replying, "I think I'm a little dumber than Forrest, but that's okay."
The Tech Takeover of Hollywood and Media Hegemony
The discussion dives into how the entertainment industry has drastically changed, becoming a "much worse business" and significantly less creative or fun than it was in its golden era. For roughly 75 years, traditional Hollywood movie studios successfully resisted and adapted to technology disruptions. Whenever a new threat emerged—whether it was the VCR, video cassettes, or cable television—the studios simply bought into the new tech themselves to maintain their dominance. However, that resilience broke down entirely with the arrival of modern tech giants, shifting the entire hegemony of the media and entertainment business directly into the hands of Silicon Valley.
Today, Netflix effectively controls the media entertainment industry. As Barry Diller bluntly puts it, "They have won. No one is ever going to beat them." The fundamental disruption lies in conflicting business models. Traditional studios rely on a hit-driven model where the goal is to create individual cultural sensations. Conversely, companies like Amazon and Apple use video content as a tool for entirely different corporate objectives. Amazon's goal is to drive Prime subscriptions to sell more physical goods, meaning they do not inherently care about individual hits as long as it sells more toasters. While Netflix does not treat entertainment as a loss leader, its model is entirely service-centric; individual movies matter less than keeping the overall subscriber base satisfied with the bundle.
* **Historical Adaptation:** For nearly 75 years, traditional studios absorbed technological disruptions like VCRs and cable TV by investing in them directly.
* **Resource Disparity:** Tech giants like Apple, Amazon, and Netflix possess at least 100 times the resources of old movie companies.
* **The Prime Model:** Amazon utilizes video content to incentivize Prime subscriptions and drive core e-commerce sales.
* **Parting Words:** When pressed for a final piece of advice for the entrepreneurs in the audience, Barry Diller offers a simple, candid directive: "Be curious. I don't know. I got no piece of advice," before wishing everyone the best to warm laughter and roaring applause.
---
Reflecting on a Decade of Acquired at Radio City Music Hall
Following Barry Diller's exit, the hosts take a moment to absorb the sheer scale of the evening, reflecting on the surreal journey of their podcast. When *Acquired* started 10 years prior as a niche technology show, neither of the hosts could have imagined in their "wildest wildest dreams" that they would eventually sell out and play the iconic Radio City Music Hall. They express profound gratitude to the audience for their years of loyal listenership and give a massive shoutout to the star-studded lineup of guests and surprise participants who made the night unforgettable.
The hosts extend deep gratitude to their sponsors, production crews, and the massive team working behind the scenes. Staging an event of this magnitude required a massive collective effort, including hundreds of crew members and a dedicated team who sacrificed their days, nights, and weekends to pull it off. Amidst the swelling walk-off music, the hosts invite the crew out and give a special, highly emphasized thank you to Mike Taylor to close out the main stage portion of the evening.
* **Milestone:** The event marks the 10-year anniversary of the *Acquired* podcast.
* **Featured Main Guests:** Jamie Dimon, Andrew Ross Sorkin, Meredith Kopit Levien, and Barry Diller.
* **Audience Participants & Cameos:** Christina Cacioppo, Ben Gilbert, Howard Schultz, and Jamie Dimon.
* **Event Partners:** Hosted by JPMorgan, with clothing and wardrobe provided by Hermès.
---
Post-Show Banter and the Afterparty
Backstage, the adrenaline is still running high as the team celebrates the successful show, exclaiming, "Dude, they did it." They immediately begin trading their favorite lines and highlights from the night. A standout comedic moment for the team was Barry Diller confidently asserting "it was all me" regarding his historical business achievements. They also laugh about Jamie Dimon accidentally ruining the night's big surprise by casually announcing from the stage that he thought Howard Schultz was lurking somewhere in the audience.
The conversation wraps up with a mix of disbelief, exhaustion, and excitement. Standing in the wings of Radio City Music Hall feels entirely surreal, prompting the reflection that "the world is a wonderful place." With the main event wrapped up cleanly, the team eagerly pivots to the afterparty, leaving the audience with one final lingering question from the night’s political banter: "So, is Jamie Dimon going to run for president?"
* **Favorite Line Contenders:** Barry Diller's humorous self-attribution ("it was all me") and Jamie Dimon spoiling the surprise guest appearance.
* **Surprise Guest Element:** The presence of former Starbucks CEO Howard Schultz was intended to be kept under wraps until Dimon spotted him.
* **Final Note:** The episode concludes on a playful note regarding Jamie Dimon's potential future political ambitions.
## Notable quotes
> [22:53](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1373s) Confidence. If you lose money as a financial company, I always knew this too... people lose trust and that causes runs on banks. — Jamie Dimon
> [47:58](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2878s) actual economics... not the accounting of what we do — Jamie Dimon
> [47:58](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2878s) Oh god, we're just giving away too many secrets here. — Jamie Dimon
> [53:29](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3209s) twiddle my thumbs and smell the flowers — Jamie Dimon
> [53:29](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3209s) Right now? Yeah — Jamie Dimon
> [01:01:13](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3673s) essential subscription for curious people everywhere — Meredith Kopit Levien
> [01:09:06](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4146s) journalism, particularly journalism about important things going on in the world, is first and foremost a human endeavor — Meredith Kopit Levien
> [01:13:39](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4419s) it's not a thing — Meredith Kopit Levien
> [01:13:39](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4419s) pursue the truth wherever it may lead — Meredith Kopit Levien
> [01:25:20](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5120s) you are either capable of creating something on your own, or you are not. — Barry Diller
> [01:25:20](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5120s) They have won. No one is ever going to beat them. — Barry Diller
> [01:33:00](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5580s) I think I'm a little dumber than Forrest, but that's okay. — Barry Diller
> [01:58:47](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=7127s) it was all me — Barry Diller
## Mentioned
Jamie Dimon, Andrew Ross Sorkin, Meredith Kopit Levien, Barry Diller, Christina Cacioppo, Ben Clymer, Howard Schultz, Mike Taylor, Linda Bamman, Sandy Weill, John Reed, Jeff Bezos, Hank Greenberg, Ken Langone, Bernie Marcus, Arthur Blank, Mike Mayo, Alan Schwarz, Hank Paulson, Tim Geithner, Eric Holder, JPMorgan Chase, J.P. Morgan, Shopify, ServiceNow, Citigroup, Citibank, Amazon, AIG, Home Depot, Bank One, First Chicago, National Bank of Detroit, United Airlines, Bear Stearns, Washington Mutual, WaMu, Silicon Valley Bank, SVB, First Republic Bank, Lehman Brothers, Federal Reserve, Hermes, Best Buy, Radio City Music Hall, Central Park, Seagram building, Four Seasons, AVA on 47th Street, Wordle, Geekwire, WeWork, Who Got the Truth?, SAP, Basel I, Palo Alto, Janet Yellen, Treasury, Chase, JP Morgan Financial Centers, Salesforce CRM, American General, Starbucks, Tom Brady, Doug Petno, Troy Rohrbaugh, Judy Dimon, DealBook, Squawk Box, Acquired, Ben Gilbert, David Rosenthal, The New York Times, Henry Raymond, Adolph Ochs, Times Square, The New York Times Company, The Wirecutter, Consumer Reports, The Athletic, Connections, OpenAI, Microsoft, The Daily, The Ezra Klein Show, Interesting Times, Ross Douthat, Hard Fork, Kevin Roose, Platformer, Value, Casey Newton, Vanta, Hermès, Hodinkee, Rolex, IAC, Fox, ABC, Paramount, Expedia, Tinder, Match.com, QVC, Ticketmaster, Diane von Fürstenberg, High Line, Little Island, William Morris Agency, Darryl Zanuck, 20th Century Fox, Elvis Presley, Roone Arledge, Bob Iger, Charles Bluhdorn, Gulf & Western, Paramount Pictures, The Godfather, Bob Evans, Leonard Goldenson, Saturday Night Fever, Grease, John Travolta, Welcome Back, Kotter, Grauman's Chinese Theatre, The Godfather Part II, Star Trek, Indiana Jones, New York Magazine, Nick Cohn, Rupert Murdoch, CBS, NBC, Fox News, Star TV, IPL, TripAdvisor, Angi, Angie's List, Vimeo, William Morris, Netflix, Apple, Prime, JPMorgan
戴蒙将网络战列为金融体系的首要系统性威胁
尽管现代银行业监管机构沉迷于利率风险与私营信贷泡沫,但全球经济稳定的终极威胁,是针对脆弱国家基础设施网络的国家级网络战。
本场现场活动通过对核心主角的深度个人专访,追踪了美国大型商业帝国的演变历程。摩根大通首席执行官 Jamie Dimon 进行了长达20年的全面回顾,分享了自己在轰动一时的解雇事件中挺过来、重组 Bank One、管理系统性风险,以及应对2008年金融海啸等历史危机的经历。纽约时报首席执行官 Meredith Kopit Levien 阐述了该报向多元化订阅组合包的重大数字化转型,而传奇媒体高管 Barry Diller 则回顾了他跨越老好莱坞、创立 Fox 以及通过 IAC 和 QVC 开创数字交互先河的60年职业生涯。
主持人在 Radio City Music Hall 开启了具有里程碑意义的现场演出,回顾了他们从旧金山 WeWork 音响故障的小型听众聚会,一路走到坐满拥有6000个座位的纽约标志性场馆的发展历程。 (1:01)
Jamie Dimon 谈到了1998年被 Sandy Weill 突然从花旗集团解雇的往事,这源于双方在精简这一庞大金融集团架构问题上的分歧。 (5:44)
离开花旗集团后,Dimon 花了18个月权衡去向——包括与 Jeff Bezos 就出任 Amazon 总裁进行了一次非常成功的会面——最终他选择重返银行业加入 Bank One。 (10:08)
Dimon 在 Bank One 接手了严重的运营混乱、四分五裂的董事会以及巨额未对冲的企业信贷风险,他通过彻底转变企业文化并亲自审计每笔贷款化解了危机。 (15:48)
摩根大通的长期生存与韧性深深扎根于 Dimon 的“要塞式资产负债表”哲学,即相比追求短期利润最大化,更加优先考虑高利润率、深厚流动性、保守会计准则,并为最坏情况下的“肥尾”风险做好准备。 (21:36)
Reading summary
At Acquired's tenth-anniversary event at Radio City Music Hall, corporate leaders Jamie Dimon, Meredith Kopit Levien, and Barry Diller illustrated how long-term institutional survival requires disciplined balance-sheet management, digital product bundling, and adapting to platform economics.
The Fortress Balance Sheet and Risk Governance (21:36)
Jamie Dimon argued that corporate resilience depends on prioritizing survival over peak cyclical profits. After being ousted from Citigroup in 1998 over disagreements regarding shedding non-core assets, Dimon assumed leadership of a fragmented Bank One in 2000, investing $60 million of his own capital. He restructured bad loans and reduced the balance sheet by roughly $50 billion prior to an economic downturn. Following Bank One's 2004 merger with JPMorgan Chase, Dimon established the firm's signature 'Fortress Balance Sheet' strategy, which relies on deep liquidity, conservative capital reserves, and rigorous accounting standards that often produce lower returns than aggressive competitors during economic expansions.
Dimon contended that misaligned compensation structures and excessive leverage inevitably trigger systemic failures. Prior to the 2008 financial crisis, Wall Street investment banks operated at leverage ratios as high as 35-to-1, with compensation plans rewarding short-term trading books. To eliminate misaligned incentives, Dimon dismantled internal 20% profit pools and capped leverage, noting that moving from 30x to 40x leverage served primarily to inflate individual trader bonuses by roughly 25%. Anticipating weakness in subprime mortgages and quantitative portfolios in late 2006, JPMorgan curtailed subprime exposure and amassed cash reserves.
Crisis Interventions and Contemporary Financial Vulnerabilities (32:33)
JPMorgan's conservative posture enabled it to execute critical distressed acquisitions during the 2008 crisis, beginning with Bear Stearns for $2 per share via an emergency liquidity facility with the Federal Reserve. Although Bear Stearns required an immediate $12 billion asset write-off and later resulted in a $5 billion federal mortgage settlement, the subsequent acquisition of Washington Mutual added 2,300 branches across high-growth states. JPMorgan acquired WaMu at a $30 billion discount to tangible book value to absorb expected mortgage losses and immediately raised $11 billion in public equity within 48 hours to preserve its capital ratios.
Assessing modern financial stability, Dimon warned that regulatory conventions such as 'held to maturity' accounting allow institutions to conceal sharp portfolio devaluations when interest rates climb, a flaw that triggered the failures of Silicon Valley Bank and First Republic Bank. Dimon noted that while the expanding $2 trillion private credit market lacks the hyper-leveraged fragility of the historical $9 trillion subprime mortgage sector, broader risks persist due to elevated equity valuations—such as the S&P 500 price-to-earnings ratio sitting near 23 compared to a historical baseline of 15—and the growing peril of cyber warfare.
The Digital Transformation and Bundling of Journalism (65:17)
The New York Times Company transitioned from near-insolvency in 2008 to a digital subscription business with a market capitalization near $10 billion. Chief Executive Meredith Kopit Levien credited this recovery to an operational model centered on core news reporting, distinct lifestyle coverage, and an integrated digital bundle. Between 2021 and 2024, the publication's subscriber base expanded from approximately 5 million to nearly 12 million, accelerated by acquisitions including Wirecutter (which drove roughly $1 billion in commerce transactions), The Athletic (with over 550 sports journalists), and Wordle.
Regarding artificial intelligence, Levien maintained that deep investigative journalism remains an irreplaceable human effort. Rather than replacing reporters, the Times applies AI as an efficiency tool for reviewing document troves and generating automated voice audio. To defend its core assets, the company filed copyright litigation against OpenAI and Microsoft, asserting that commercial AI developers must pay fair value for proprietary intellectual property rather than training models on journalistic archives without compensation.
Platform Hegemony and the Disruption of Hollywood
Barry Diller observed that the entertainment industry's 75-year record of absorbing technological disruptions—such as home video and cable television—ended when Silicon Valley platform companies seized distribution power. Diller stated that Netflix has decisively won the streaming market, asserting that legacy studios will not overcome its scale. He attributed this divergence to conflicting business models: traditional studios rely on hit-driven theatrical releases to turn individual profits, whereas technology conglomerates deploy video content to advance separate commercial goals.
Diller highlighted that Amazon finances streaming video primarily to drive Prime memberships and retail merchandise sales, whereas Netflix operates a service-centric subscription model that de-emphasizes individual box-office performance. Consequently, legacy media companies unable to match the non-entertainment revenue engines of modern technology giants face a structurally diminished and financially strained operational environment.
The proceedings demonstrate that enduring institutions survive disruption by maintaining structural discipline and coherent business models, whether through banking balance sheets, journalistic product bundles, or media distribution networks. However, unanswered questions persist regarding how traditional intellectual property and entertainment businesses will compete against capital-rich technology conglomerates and generative AI systems.
精炼阅读摘要
本期《Acquired》现场特辑汇聚了银行业、传统传媒与现代数字出版的三位领袖,核心论点在于:无论万亿金融巨头、数字化转型的百年报业还是跨越六十年的娱乐帝国,其穿越周期的根基均建立在对底层风险的敬畏、对主业协同的专注,以及在技术颠覆中捍卫核心价值边界的定力。
极端风险敬畏与堡垒资产负债表 (21:36)
摩根大通董事长兼首席执行官 Jamie Dimon 强调,金融生存的首要法则是防御低概率但具毁灭性的“肥尾”极端风险,而非在顺周期追求过度利润。他推行以充沛流动性、保守资本结构与严格会计核算为特征的“堡垒资产负债表”(Fortress Balance Sheet),公开抨击现行会计规则允许机构在繁荣期前置可疑收益。这一逻辑贯穿其管理历程:接管陷入混乱的 Bank One 时,他顶住压力审计并撇清全部坏账,在经济衰退前将资产负债表缩减约 500 亿美元;在 2008 年金融危机前夕,当华尔街投行普遍借助监管漏洞将杠杆拉至 35 倍时,他主动压缩次贷风险敞口并储备流动性,使摩根大通得以在危机中以每股 2 美元承接 Bear Stearns,并以 300 亿美元账面折价收购 Washington Mutual,且在交易后 48 小时内从公开市场筹集 110 亿美元以加固安全垫。
针对近年银行业动荡,Dimon 批评现行“持有至到期”(HTM)监管会计准则掩盖了主权债务亏损,指出硅谷银行(SVB)与第一共和银行(First Republic Bank)倒闭的本质在于管理层和监管方忽视的利率期限错配——在低利率时期大量购入 3% 收益率的抵押贷款,当利率升至 5% 时资产价值直接缩水至五六成。尽管摩根大通随后受邀承接第一共和银行并在硅谷增设 500 人规模的创新团队,Dimon 仍警告当前市场资产价格虚高(标普 500 指数市盈率处于 23 倍高位,远高于历史稳健期的 15 倍),并将网络攻击与地缘政治视为比传统信贷更为严峻的系统性威胁。
组织治理重构与主业协同优势 (47:58)
在 Dimon 看来,金融机构能够脱颖而出的深层动力在于治理机制纠偏与主业业务的自然互补。在掌舵摩根大通后,他彻底取缔了华尔街投行针对特定短期交易提取 20% 利润池的传统分红方式,消除了交易员为博取个人奖金而将杠杆从 30 倍加至 40 倍的投机冲动,确立“不得对客户做出不当行为”的底线原则,即便部分高管因此流失也在所不惜。
在商业模式上,Dimon 将摩根大通的运转逻辑类比为巨型“社区银行”,让中型市场商业信贷、全球投行并购服务与零售外汇等业务在内部无缝咬合、相互供血,从而构筑起极高的运营效率护城河——摩根大通相比竞争对手每赚取 1 美元收入,能多沉淀 15 美分的净利润。他借此反思前东家 Citigroup 的扩张教训,批评无序收购卡车租赁、人寿保险等非核心副业不仅难以形成业务合力,还会导致最高管理层彻底失去对底层潜在风险的穿透能力。
报业数字突围与AI时代的内容壁垒 (61:13)
The New York Times 首席执行官 Meredith Kopit Levien 阐述了这家百年报纸从 2008 年被迫出售总部大楼的破产边缘,转型为全球最大独立数字订阅媒体的实践路径。通过贯彻“核心新闻目的地+垂类生活方式”的战略,该报将导购平台 The Wirecutter(年促成约 10 亿美元电商交易)、拥有逾 550 名记者的体育媒体 The Athletic 以及现象级智力游戏 Wordle 整合为多产品数字捆绑包(Bundle)。这一布局驱动其订阅用户从 2021 年的约 500 万跃升至近 1200 万,市值接近 100 亿美元的历史高位,并实现了休闲娱乐用户向严肃国际报道的跨业务转化。
面对生成式人工智能对传媒生态的冲击,Levien 强调深度新闻采编本质上是人类情感与现场观察的专属实践,并非算法或无人机所能替代。The New York Times 依托两道人工事实核查防线保障公信力,同时仅将 AI 作为协助记者挖掘海量公共文档与拓展语音阅读的“力量倍增器”。围绕知识产权争端,Levien 解释对 OpenAI 和微软发起诉讼的核心原因在于:科技公司斥巨资投入算力、电力与工程人才,却拒绝对训练大模型所消耗的高价值原创版权支付对价,这一维权行动关乎整个创意内容生态的长期经济基石。
媒介范式颠覆与硅谷的技术霸权 (106:21)
拥有六十年行业经验的 IAC 董事长 Barry Diller 梳理了传统好莱坞向现代科技平台转移的话语权更迭。早年他在威廉·莫里斯经纪公司翻阅全量历史档案自学行业精髓,在派拉蒙以《周末夜狂热》和《油脂》完成票房破局,随后在福克斯与善于巨额豪赌的鲁伯特·默多克共事;他在 49 岁走出传统片厂体制,通过电视购物网络 QVC 敏锐捕捉到电视、电话与计算机三网合一的商业雏形。然而,Diller 指出好莱坞过去 75 年能够消化录像带与有线电视的冲击,却在硅谷的降维打击下彻底丧失了产业主导权。
在 Diller 看来,Netflix 已经毫无悬念地赢得了流媒体竞争,宣告了传统电影业以爆款为核心的商业模式彻底终结。传统制片厂依赖单片票房与文化轰动效应,而现代流媒体纯粹依赖订阅服务运转。更为关键的是,苹果与亚马逊等科技巨头仅将流媒体内容作为生态辅助工具(例如亚马逊通过视频带动 Prime 会员体系以售卖更多实体商品),根本不在意单部作品的盈利表现。这种价值取向的错位使得如今的内容制作沦为科技巨头的引流附属品,令娱乐业变成了利润受损、原创力被稀释的严峻赛道。
本场对话展现了资深决策者在周期更替中的防御哲学:无论是银行业的资本自律、新闻业对版权与人类核查的坚守,还是传媒巨头对平台垄断的现实评估,均证明技术虽能重写分发模式,但企业的持久壁垒仍在审慎的底层风控与主业价值的不可替代性;至于版权诉讼能否迫使人工智能产业重构利益分配机制,以及金融巨擘未来是否走向公共政治舞台,仍有待市场持续检验。
Detailed notes — zh
## Background
该视频由知名商业播客频道 Acquired 于 2025 年 11 月 5 日发布在 YouTube 平台上。视频是 Acquired 在纽约无线电城音乐厅(Radio City Music Hall)举办的首部现场“音乐会级电影”,记录了两位主持人与摩根大通首席执行官 Jamie Dimon、《纽约时报》首席执行官 Meredith Kopit Levien、知名记者 Andrew Ross Sorkin 以及传奇传媒大亨 Barry Diller 的重磅现场对谈,并穿插了 Howard Schultz 等嘉宾的客串互动。
## TL;DR
整场盛会分为两大核心篇章:第一幕深入复盘了摩根大通董事长兼 CEO Jamie Dimon 的职业生涯,详述他从被花旗扫地出门到拯救 Bank One,再到坚守“堡垒式资产负债表”、在 2008 年次贷风暴与 2023 年硅谷银行危机中逆势扩张的金融风控哲学。第二幕以深夜脱口秀形式展开,由 Andrew Ross Sorkin 趣味暖场,《纽约时报》CEO Meredith Kopit Levien 分享了纽时从纸媒危机逆袭为千万级数字订阅帝国的转型之路及面对 AI 时代的维权与坚守;最后,传奇传媒大亨 Barry Diller 压轴登场,回顾了他从好莱坞收发室、首创“周播电影”、执掌派拉蒙与福斯,到自担风险押注 QVC 开启互联网商业帝国的非凡历程,并深刻剖析了流媒体与科技巨头对影视工业的降维冲击。
## Atmosphere & style
整场演出兼具百老汇舞台的恢弘震撼与深度商业对谈的极致通透,现场乐队与全场爆满观众的掌声呼应,营造出极具感染力的狂欢气场。两位主持人与商业巨擘们的对话既有深入骨髓的战略洞察与历史机密,又充满了举重若轻的冷幽默、犀利自嘲与好友式的互怼调侃。从回顾创业低谷的唏嘘沉静,到直面系统性金融危机的惊心动魄,再到后台彩蛋中主创团队难以置信的兴奋与感慨,整场演出洋溢着纯粹的探索激情、深厚的人文底色以及对商业与时代精神的至高礼赞。
## Bulletin
- [19:27](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1167s) 摩根大通董事长兼 CEO Jamie Dimon 回顾其风控哲学与危机并购史,指出摩根大通在繁荣期严格压缩杠杆、拒绝虚高 ROE,并强调收购贝尔斯登和 WaMu 虽使公司后续背负数百亿美元罚金与诉讼,但构筑了其如今约 8,000 亿美元市值的系统性信用基石。
- [01:00:36](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3636s) 《纽约时报》CEO Meredith Kopit Levien 披露其数字化转型成果:订阅用户数已逼近 1,200 万,纸媒收入占比压减至 25% 左右,并依靠 Wirecutter、The Athletic 和 Wordle 组成的高频生活方式矩阵与核心硬新闻形成互哺飞轮。
- [01:53:20](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6800s) 传奇传媒大亨 Barry Diller 剖析内容工业的范式变迁,指出 Netflix 与拥有万亿资金的科技巨头已彻底重构影视产业格局,将过去以单品爆款为核心的商业模式降维成平台会员留存与引流工具。
- [41:17](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2477s) Jamie Dimon 警示当前宏观与金融系统的深层隐患,认为 2 万亿美元规模的私人信贷(Private Credit)虽存局部风险但不足以引发系统性危机,真正的首要系统性威胁在于地缘冲突下针对电网、供水及通信等关键基础设施的网络战攻击。
## Key takeaways
- [12:34](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=754s) Dimon 坚持不以短视指标为导向,接管第一银行(Bank One)时自掏腰包 6,000 万美元(占个人当时半数身家)购入股票,以破釜沉舟的姿态绑定长期利益并重构混乱的底层风控与 IT 架构。
- [21:36](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1296s) 摩根大通的“堡垒式资产负债表”(Fortress Balance Sheet)理念核心在于直面极端肥尾风险(Fat Tails),压力测试直接套用历史极值情景(如高收益债利差飙升至 17%),宁可牺牲顺周期利润也不碰高危杠杆。
- [30:43](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1843s) 拆除投行部门的利益黑匣子是避免爆雷的关键:Dimon 坚决废除单一交易的高额提成与暗盘协议,杜绝交易员为了放大个人奖金而将资产杠杆推高至 30-40 倍的逆向激励。
- [35:02](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2102s) 政府救市后的监管反噬让 Dimon 感叹“再也不相信政府”,摩根大通在危机后支付的罚金与诉讼中 80% 源于代为接盘的贝尔斯登与 WaMu 历史坏账,但出于国家责任感未来危急时刻仍会出手。
- [44:12](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2652s) 硅谷银行(SVB)暴雷本质是“高集中度存款”在风投圈引发的数字化踩踏与长期资产未按市值计价(Mark-to-Market)叠加的结果,盲目依赖“持有至到期”(HTM)会计掩盖了实际资产缩水。
- [51:04](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3064s) 摩根大通超额利润率(每赚 1 美元比同行多截留 15 美分)并非靠削减开支,而是源于零售、中型商业银行与顶级投行之间像“社区银行”一样紧密咬合、相互引流滋养的业务生态体系。
- [01:04:27](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3867s) 《纽约时报》完成从“被动防守”到“全面进攻”的战略跃迁,围绕硬新闻主干自研并收购 Wirecutter、The Athletic、Wordle 等垂直资产,打造成覆盖日常高频场景的综合订阅包(Bundle)。
- [01:09:06](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4146s) 面对 AI 浪潮,纽时主张以人为本、视 AI 为记者采编的放大器,同时坚持起诉大模型侵权以捍卫内容原创价值,要求大模型厂商必须为训练所需的核心智力资产支付对等对价。
- [01:16:21](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4581s) 播客(如 The Daily、Hard Fork)凭借对话式叙事(conversational storytelling)拉近受众距离,通过展现采掘调查与交叉核实的过程,成为现代新闻重构读者深层信任的关键阵地。
- [01:27:32](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5252s) Barry Diller 早年在威廉·莫里斯经纪公司通读近 70 年原始通信档案,以“沉浸式一手史料研读”领悟了好莱坞商业逻辑底层规律,这一路径与 Acquired 的研究范式不谋而合。
- [01:31:52](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5512s) 在 ABC 任职期间,Diller 靠极致成本控制与工业化流程首创“周播电影”(Movie of the Week),随后执掌派拉蒙打破好莱坞经纪人打包模式,引入储备 90+ 项目池的主动剧本研发体系。
- [01:42:01](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6121s) Diller 极度崇尚 Rupert Murdoch 的敢赌气魄,但在企业管理上坚决反对普通企业“拿整家公司作赌注”,认为除非被逼入绝境,否则绝不能用成熟的好业务去为高危创新试错买单。
- [01:49:11](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6551s) 在 1993 年踏入 QVC 演播室并看到电视、电话与绿屏电脑实现的实时互动曲线后,Diller 顿悟“屏幕不仅是讲故事的工具,更是商业交互入口”,从而在互联网普及前夜确立了跨界科技投资的长期认知优势。
- [01:53:20](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6800s) 流媒体战争的终局是科技巨头对传统制片厂体制的降维打击:影视作品对 Amazon 而言是兜售日用品的引流品,对 Netflix 而言是整体订阅池的留存组件,单部爆款的传统统治力被技术商业模式彻底稀释。
## Detailed walkthrough
### [00:00](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=0s) 幕后序曲:从旧金山 WeWork 到无线电城音乐厅
在大幕拉开之前,Ben Gilbert 与 David Rosenthal 穿行在纽约街头,对整场演出的不可思议感到惊叹。演出门票在没有对外公布任何嘉宾阵容和节目细节的情况下便全部售罄。“这可是百老汇,这是剧院艺术,大家就是来看一场货真价实的表演,”Ben 兴奋地说道。他们搭乘 B 标志的地铁线穿梭于曼哈顿,顺道在中央公园附近买了一根热狗,聊起纽约那张著名的《纽约客》杂志封面漫画——在纽约客眼中,曼哈顿一过哈德逊河对面就是加州,中间空无一物。
走在通往舞台的路上,两人回忆起 Acquired 最早的线下活动。最初是西雅图的 GeekWire 大会,接着是在旧金山田德隆区(Tenderloin)的一间 WeWork 里为仅仅约 100 名听众录制节目。那次录制中途扩音系统(PA system)彻底罢工,还是工作人员紧急狂奔到百思买(Best Buy)现买了一套设备才撑完全场。如今站在无线电城音乐厅(Radio City Music Hall)门前,两人不禁感叹这一路走来的跨越。
---
### [01:33](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=93s) 燃爆现场:无线电城舞台上的升级开场
伴随着全场雷鸣般的掌声与欢呼,报幕声引出两位主持人登上舞台。起初,舞台灯光简单,两人坐在空旷的台前,旋即意识到这样传统狭小的播客录制形式完全浪费了无线电城音乐厅这处世界顶级舞台的恢弘气势。Ben 随即呼叫现场音乐人 Mike Taylor:“迈克,能帮我们把现场的气氛拉满吗?”
音乐随即轰鸣而起,Mike Taylor 现场弹唱起 Acquired 标志性的主题曲《Who Got the Truth》,震撼的节奏与动感的舞台效果瞬间点燃了整个音乐厅。两人换上爱马仕(Hermès)定制正装重新亮相,David 笑着称赞 Ben 的造型利落帅气,随后正式宣布演出开始,向来自全美各州乃至全球不同大洲不远万里赶来的观众们致谢。
---
### [03:58](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=238s) 盛会架构:两幕大戏与第一位重磅主角
面对纽约这座全球最伟大城市中殿堂级的舞台,Ben 和 David 决定打破常规,将整场演出划分为两大章节:
- **第一幕**:聚焦一家举足轻重的美国企业,邀请亲自缔造这一传奇的企业领袖本人登台,展开深度对话。
- **第二幕**:中场休息之后,尝试一种专为无线电城音乐厅量身定制的全新演出形式,并与另外两位纽约最具代表性的传奇 CEO 进行思想碰撞。
在介绍今晚第一幕的核心主角时,主持人们给出了极高的评价:在当今美国商界,他是唯一一位其影响力超越了企业管理者范畴、被整个国家视为领袖的在任 CEO。他掌舵的巨舰市值高达约 8,000 亿美元,不仅是纽约最有价值的企业,也是密西西比河以东市值最高的高峰。在一片雷鸣般的掌声中,摩根大通(JPMorgan Chase)董事长兼首席执行官杰米·戴蒙(Jamie Dimon)缓步登台。
```mermaid
flowchart TD
accTitle: Acquired 无线电城现场演出的整体结构
accDescr: 图表展示了当晚现场演出的双幕结构及第一幕登场的重磅嘉宾摩根大通CEO杰米·戴蒙。
subgraph ShowStructure["Acquired 现场演出架构"]
A["开场与引言"] --> B["第一幕:商业史诗深度对话"]
A --> C["第二幕:全新互动形式与双CEO对谈"]
end
subgraph ActOne["第一幕核心"]
B --> D["主角:摩根大通董事长兼 CEO Jamie Dimon"]
D --> E["复盘 20 年间打造全球最重要金融机构的历程"]
end
```
---
### [05:36](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=336s) 1998年花旗滑铁卢:从接班人到被扫地出门
对谈开门见山切入历史。Ben 与 David 计划梳理杰米·戴蒙用 20 年时间把摩根大通从一家普通大行打造成“全球最具系统重要性金融机构”的完整脉络。然而对话的起点却并不光鲜,而是直接拉回到 1998 年戴蒙职业生涯最至暗的时刻。在此之前的 13 年里,戴蒙与导师桑迪·威尔(Sandy Weill)并肩作战,通过商业信贷公司(Commercial Credit)、Primerica、旅行者集团(Travelers)的一系列兼并,最终与花旗银行(Citibank)合并,一手构建了现代金融联合帝国的雏形——花旗集团(Citigroup)。华尔街普遍认为戴蒙接任花旗 CEO 只是时间问题。然而在 1998 年,戴蒙却被突然解雇,一切归零。
戴蒙在现场坦诚复盘了他与桑迪·威尔在战略上的根本分歧:桑迪热衷于金融多元化联合体,四处收购不同业务、重组套现;而戴蒙则坚持“瘦身”战略,主张剥离与核心业务无关的板块,只保留在战略上有协同价值的资产。正是这一理念上的冲突,埋下了决裂的种子。
随后戴蒙生动还原了被解雇那一天的戏剧性场景:
- 当时他正在纽约的公寓里招待 100 位参加管培生招聘的高校年轻人。
- 桑迪·威尔与联合 CEO 约翰·里德(John Reed)紧急致电,要求他立刻参加周日下午 4 点的管理层会议。
- 赶到会议室后,两人宣布了三项决定:前两项涉及重要人事调整(包括调整戴蒙主管的全球投资银行部业务),戴蒙当场认为极其愚蠢;第三项则是直接通知:“我们希望你辞职。”
- 戴蒙敏锐地意识到董事会已完成投票,新闻通稿早已拟好,不可逆转,于是果断回答:“好。”
回到家后,戴蒙把被解雇的消息告诉了三个年幼的女儿(当时分别约 10 岁、12 岁和 14 岁):
- 小女儿惊慌地问:“爸爸,我们以后是不是得睡大街了?”
- 老二最关心学业:“那我还能上大学吗?”
- 最大的女儿则毫不客气地补刀:“太好了,既然你不用工作了,你的手机能给我吗?”
当天晚上,包括下午刚开完会的管理团队在内,约 50 名高管同事提着威士忌涌进戴蒙的公寓,场面滑稽得像“参加自己的守灵会”。一位身材高大的密友走进门,戴蒙的女儿问他是谁,对方回答:“我为你爸爸工作。”随后他又苦笑着改口:“不过现在已经不是了。”
戴蒙借此分享了支撑他走出低谷的座右铭:“卷入其中的只是我的净资产(Net Worth),而不是我的自我价值(Self-Worth)。”尽管后续花了长达 18 个月与花旗完成极其苛刻的退出谈判并寻找下一站,他始终保持了风度与定力。
### [10:30](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=630s) 离开花旗后的空档期与亚马逊的“平行宇宙”
在离开花旗集团(Citigroup)后,杰米·戴蒙(Jamie Dimon)先是和家人度过了一个惬意而漫长的假期。等到当年9月(大约六个月后),他重新回归了朝九晚五的生活节奏。当时他在纽约著名的西格拉姆大厦(Seagram Building)租了办公室,尽管手头没有具体的工作业务,但他每天依然准时上下班,在办公室给各界人士通电话,仔细权衡人生的下一步规划。那段时间,他每天中午都会下楼到底层的四季餐厅(Four Seasons)用餐。他思考了各种可能性:创办自己的商业银行(Merchant Bank)、直接退休去大学教书,或者单纯依靠自有资金做投资——毕竟那一年他才42岁,正值当打之年。
在此期间,杰米·戴蒙曾受邀飞往西雅图与杰夫·贝佐斯(Jeff Bezos)会面。当时贝佐斯正在物色一位亚马逊公司(Amazon)的总裁。两人一见如故、十分投缘,从此结下了深厚的友谊。杰米评价贝佐斯是“一位极其卓越的非凡人物”。但对于当时的杰米而言,跨界去西雅图做互联网电商跨度实在太大。他打趣道,那时电影《当哈利遇到莎莉》(When Harry Met Sally...)的热度犹在,他脑海中浮现的画面是:“我的天,去西雅图我可能再也不用穿西装了,我可以去住游艇船屋了,那生活一定棒极了。”Acquired 主持人不禁感叹,如果他当年接下这份工作,大家今天将身处一个何等不同的“平行宇宙”。杰米笑称,虽然没去亚马逊,但至少收获了与贝佐斯一生的友谊。
```mermaid
flowchart TD
accTitle: 杰米·戴蒙离职后的职业选择
accDescr: 展示杰米·戴蒙在离开花旗后收到的各种工作邀请与最终的选择路径
subgraph 潜在机会与探讨
A["西雅图: 亚马逊 Amazon<br/>与贝佐斯洽谈总裁职位"]
B["纽约: AIG<br/>汉克·格林伯格抛出橄榄枝"]
C["亚特兰大: 家得宝 Home Depot<br/>创始人盛情邀请担任掌门人"]
D["次级抵押贷款公司<br/>高风险次贷机构(果断拒绝)"]
end
subgraph 最终抉择
E["芝加哥: 第一银行 Bank One<br/>陷入危机的区域巨头(市值约200亿美元)"]
end
A -.->|跨界幅度过大| E
B -.->|不愿刚脱离韦尔又入格林伯格之手| E
C -.->|非金融主场且此前从未进过其门店| E
D -.->|彻底否决| E
```
### [11:24](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=684s) 拒绝 AIG 与家得宝:回归熟悉的金融主场
随着探索的深入,杰米开始严肃考虑下一份全职工作。当时不少大型跨国投资银行向他抛出橄榄枝。执掌美国国际集团(AIG)的金融巨鳄汉克·格林伯格(Hank Greenberg)也亲自给他打电话,力邀他加盟。但杰米心里直打鼓:自己刚刚从控制欲极强的桑迪·韦尔(Sandy Weill)手下离开,如果再去给同样铁腕强势的汉克·格林伯格打工,那自己的“脑子一定是坏掉了”。此外,还有几家次级抵押贷款公司找上门来,杰米的反应则是斩钉截铁的“绝不可能”。
与此同时,猎头公司还牵线了家得宝(Home Depot)。杰米飞赴亚特兰大,与家得宝的传奇创始人肯·兰格恩(Ken Langone)、伯尼·马库斯(Bernie Marcus)和阿瑟·布兰克(Arthur Blank)共进晚餐。在餐桌上,作为地道纽约客的杰米坦承了一个尴尬的秘密:“在你们给我打电话之前,我这辈子从没踏进过任何一家家得宝的店门。”后来还是一位朋友特意带他去店里买了工具和绿植补课。尽管杰米非常赞赏家得宝的企业文化和几位创始人的魄力,肯·兰格恩至今也常常念叨“当年要是开出更高的薪酬就拿下你了”,但杰米最终选择拒绝并非为了钱,而是因为他心心念念的依然是自己的“栖息地”——金融服务与银行业。
- **工作邀约对比**:
- **AIG**:由铁血强人汉克·格林伯格掌舵,管理风格与花旗的桑迪·韦尔极其相似,杰米因此敬而远之。
- **家得宝(Home Depot)**:零售业巨头,文化富有激情,但并非杰米专长的金融腹地。
- **次级贷款机构**:高风险模式,杰米直接拒绝甚至不予考虑。
- **第一银行(Bank One)**:总部位于芝加哥的陷入困境的银行,完全契合其银行专业底色与重组抱负。
### [12:34](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=754s) 押上身家的赌注:6000万美元买入第一银行
最终,杰米锁定了第一银行(Bank One)。这是一家总部位于芝加哥的银行业巨头,当时刚刚经历了一系列并购消化不良,深陷泥潭。搬迁对于杰米的家庭是一项重大考验,两个孩子当时分别只有14岁和12岁,举家搬迁离开纽约绝非易事。但他们一家在芝加哥租房过渡后买下了一处漂亮的联排别墅(Brownstone),迅速爱上了这座城市。
在规模上,第一银行当时市值约为210亿美元(此前花旗集团的市值高达2000亿美元)。面对体量上的落差,杰米心态十分豁达,他崇尚“生活是靠自己过出来的,不要为洒掉的牛奶哭泣,穿上裤子就开干”。为了向董事会、员工和外部股东展现孤注一掷的决心,杰米在正式入职出任首席执行官前夕,自掏腰包砸下6000万美元购入第一银行的股票,这相当于他当时个人净资产的一半。在商业史上,几乎未曾有过新任外来 CEO 在入职前夕将一半身家押进公司的先例。杰米坦言,即便当时市场因为传言银行会被收购而导致股价偏高,他也毫不在乎:他要成为“与这艘大船同生共死的船长”,用全仓下注(Lock, stock, and barrel)的方式向所有人宣告自己绝不会在短期套现,而将完全着眼于企业的长远健康做决策。
### [15:05](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=905s) “连大力神都治不好”的烂摊子与初入职场的下马威
杰米接手的第一银行,在业内被视作彻头彻尾的灾难。知名华尔街银行业分析师迈克·梅奥(Mike Mayo)曾在一份著名研报中留下经典断言:“连大力神赫拉克勒斯(Hercules)都收拾不了这个摊子。”第一银行本质上是由老第一银行(Bank One)、芝加哥第一国民银行(First Chicago)和底特律国家银行(National Bank of Detroit, NBD)强行拼凑而成的畸形巨无霸。三家机构合并后从未进行过真正的底层业务整合,内部并存着多套割裂的对账单系统、交易处理系统、支付网络和 SAP 系统。银行服务质量急剧下滑、客户账户大批流失,管理层甚至不得不关闭大量分支机构,旗下的信用卡业务更是濒临崩溃。
在公司治理层面,情况同样剑拔弩张。第一银行董事会竟有多达21名董事,他们分属于被并购的各个原始山头,党同伐异,“其中11个人痛恨另外10个人”。杰米在接受聘任当天与其中6位董事会面,他直截了当地告诉他们:自己会告知大家全部的真相,无论是好的、坏的还是丑陋的,绝不粉饰太平;他需要董事会的全力支持来打造一家伟大的公司。然而握完手后,董事们便散会离去,将孤身一人的杰米留在空荡荡的执行高管楼层。
找不到方向的杰米只能去敲人力资源主管的门,告知对方自己需要一间办公室和一名助理。行政部门原打算将位于角落位置的显赫董事长办公室安排给他,杰米当场拒绝,要求把工位设在高管楼层的正中央:“我要待在正中间,这样只要探出头就能看到所有人。”随后,管理团队被召集到一间铺着白色厚地毯的豪华会议室。杰米端着一杯咖啡走进去,高管们立刻提醒他:“杰米,鉴于这里的地毯,出于众所周知的原因,我们在这里是从不喝咖啡的。”杰米低头看了看咖啡,又抬头扫视了一圈众人,平静地撂下一句话:“从现在起,你们可以喝了。”("You do now.")
### [17:36](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1056s) 穿透虚假繁荣:重塑第一银行的风险文化
在Acquired主持人的追问下,话题转向了摩根大通(JPMorgan Chase)日后笑傲华尔街的核心基石——风险管理文化。杰米强调,管理层对风险的本质理解至关重要。“风险意识(Risk conscious)绝不等于消除风险,而是对风险进行精准合理的定价,并深刻理解各种极端潜在结果的冲击。”
杰米进驻第一银行后迅速梳理资产,立刻被眼前的景象震惊:第一银行账面上承担的美国企业级信贷风险(Corporate Credit Risk),竟然比规模大得多的花旗银行还要庞大。更致命的是,该行的会计处理方式激进到了令人发指的程度。他们肆意压低拨备水平、缩减资本计提,将本质上亏损的信贷业务包装成高利润产品对外宣称。一旦看穿了这层粉饰出来的虚假繁荣,杰米感到极度心惊甚至有些恐慌,随即决定卷起袖子,亲自排查每一个信贷资产包与业务敞口,全面掀起底层风险清洗与重构的风暴。
### [18:46](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1126s) 掌舵 Bank One:清理资产负债表与聘请 Linda Bamman
杰米·戴蒙(Jamie Dimon)接手第一银行(Bank One)后,立刻对账目上的每一笔贷款进行了大刀阔斧的审视。他全额计提减值准备、增加坏账拨备并向董事会全盘汇报,力求提高每单位风险资本所能产生的收益。戴蒙骨子里永远在进行压力测试,他向董事会展示:如果经济衰退即将来临,银行在信贷业务上究竟会亏掉多少钱。
为了彻底扭转局面,戴蒙招募了风险管理领域的顶尖人才琳达·巴曼(Linda Bamman)。两人的入职谈判极具戴蒙式的务实风格——巴曼开出条件:“如果你让我主管信贷,你会允许我抛售贷款吗?”戴蒙答:“可以。”“你会让我做贷款对冲吗?”“可以。”“我能做100亿美元规模的对冲与剥离吗?”戴蒙斩钉截铁地回答:“可以。”巴曼随即表示:“好,那我加入。”在她的操盘下,Bank One 将资产负债表规模削减了近 500 亿美元。随后的经济衰退如期而至,由于提前清理了风险敞口,Bank One 得以安然度过风暴,唯一的重创是联合航空(United Airlines)宣告破产,使他们一度实际接盘并持有了该公司短暂的一段时间。
- **信贷清理策略**:全面下调不良资产账面估值,提高风险储备金,追求更高的单位风险收益率。
- **关键高管引入**:授权 Linda Bamman 自由出售贷款与对冲风险,成功削减约 500 亿美元高风险资产。
- **唯一重大踩雷**:联合航空破产重组事件,Bank One 曾被迫短期持有其重组资产。
---
### [19:27](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1167s) 戴蒙主义核心:绝不在风险中灰飞烟灭(Don't Blow Up)
当主持人指出戴蒙的底层经营哲学就是“不惜一切代价避免爆仓(Don't blow up)”时,戴蒙谈到了自己的成长经历与历史沉淀。市场上永远有一种嘈杂的生态圈声音在喊着:“大家都在这么干”、“这次不一样”、“没问题的”。但戴蒙的父亲就是一名股票经纪人,他 14 岁时(1972 年)就买了自己的第一只股票,早在 1968 年美股道琼斯指数触及 1000 点时,年少的他就已经在帮父亲打下手。
历史的残酷教训早已刻在戴蒙的基因里:1974 年市场暴跌 45%,华尔街街头的加长礼车一夜消失,高级餐厅纷纷倒闭;1980 年初短暂复苏,随即陷入 1982 年更惨烈的衰退,股市跌破 800 点,甚至低于 1968 年的水平;1987 年“黑色星期一”,美股单日崩盘 25%;1990 年商业地产危机让 J.P. Morgan、花旗(Citibank)、大通(Chase)以及汉华实业银行(Chemical Bank)全被打得跪地求饶,当时绝大多数银行市值只剩下 10 亿美元左右,花旗也不过约 30 亿美元。紧接着是 1997 年亚洲金融危机、2000 年互联网泡沫破裂以及 2008 年次贷危机。戴蒙指着台下的安德鲁·罗斯·索尔金(Andrew Ross Sorkin)提到,索尔金刚送给他一本关于 1929 年大崩盘的新书,“历史总在押着相同的韵脚”——极度的杠杆、泛滥的贪婪、盲目的乐观,当时市场年复一年地暴跌 20%、30%、20%,最终累计暴跌 90%,“倒霉的破事总会发生(Shit happens)”。
```mermaid
flowchart LR
accTitle: 华尔街历史周期与重大危机
accDescr: 展现杰米·戴蒙亲历的多次市场崩盘与金融危机时间线
subgraph 早期危机经验
Y1974["1974年崩盘<br/>暴跌 45% / 华尔街萧条"] --> Y1982["1982年衰退<br/>跌破 800 点"]
Y1982 --> Y1987["1987年黑色星期一<br/>单日暴跌 25%"]
end
subgraph 银行系统风暴
Y1990["1990年地产坏账<br/>各大银行市值跌至10亿级"] --> Y2000["2000年互联网泡沫<br/>资本市场估值破裂"]
Y2000 --> Y2008["2008年次贷危机<br/>高收益债利差飙升至20%"]
end
```
---
### [21:36](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1296s) 肥尾效应与压力测试:宁要活命,不要虚高 ROE
对待极端风险,戴蒙的准则从来不是去猜小概率事件何时发生,而是假定“最坏的倒霉情况一定会发生”并确保银行能硬扛过去。戴蒙刚进 J.P. Morgan 时翻看风控手册,发现他们对高收益债券(垃圾债)的压力测试设定是信用利差走阔 40%(从 400 个基点扩大到 560 个基点)。戴蒙当场推翻:“不行,我们的压力测试标准必须是历史最差水平——1700 个基点(17%)。”风控人员当时反驳说市场已经更成熟完备,绝不可能重现那种极端情况。结果到了 2008 年危机,高收益债利差直接暴飙至 20%,市场完全冻结,连一张债券都卖不出去。
戴蒙强调,他紧盯的是“肥尾效应(Fat Tails)”,而不是美联储设定的常规压力测试模型:股市腰斩 50%、基准利率飙升至 8%、信用利差回到历史最高点。在金融业,要命的有三件事:过高杠杆、激进会计准则、失去公众信任。银行一旦亏损登上新闻头条,客户就会恐慌提款,造成致命的挤兑。在 2007 年以前的繁荣期,许多同行通过激进加杠杆赚取高达 30% 的净资产收益率(ROE),这些机构后来绝大多数破产清算;而戴蒙宁可在好年份“牺牲一部分超额收益”,维持极度保守的财务基础,换取在 2008 年和 2009 年屹立不倒。
- **垃圾债压力测试**:团队原设定利差扩大 40%,戴蒙强制拉高至历史极值 17%(1700 个基点),后在 2008 年危机中实际破纪录触及 20%。
- **肥尾测试情景**:股市下跌 50%、利率升至 8%、信用利差重回历史最糟极端。
- **高杠杆代价**:繁荣期追求 30% ROE 的对手行多数在危机中倒闭,戴蒙坚持保守底线以换取终极生存。
---
### [24:08](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1448s) 坚守“堡垒式资产负债表”(Fortress Balance Sheet)
谈到其著名的“堡垒式资产负债表”管理哲学,戴蒙回忆早在 1990 年代初他就不断向团队灌输这个概念:必须建立起能够抵御极端严冬的厚重防护垫。所谓堡垒,核心在于卓越的客户服务、优良的利润率、充沛的流动性以及坚实的资本充足率。在财务处理上,戴蒙自称是“你能找到的最保守的会计”,坚决不提前确认未实现的利润,而是选择随着时间推移平摊确认。
戴蒙直言不讳地讽刺会计准则:“会计师最讨厌我这么说,但现行会计规则的漏洞大到你能开一辆卡车穿过去。”在很多账目中,对未来的良性长远投资在账面上被计为“当期支出”,而盲目发放高风险烂贷款所赚取的利息在短期内却被当作“漂亮收入”,直到炸雷才会露出原型。此外,戴蒙极为强调客户的道德与资质:“在银行业,你的客户是什么成色,最终就会投射成你的银行是什么成色。”同时必须持续严审薪酬激励机制,防止员工因为愚蠢或缺乏职业操守的冒险行为而拿到高额分红。
---
### [25:22](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1522s) 世纪大合并:从 Bank One 到执掌摩根大通
2004 年,芝加哥的 Bank One 与总部位于纽约的 J.P. Morgan Chase 达成历史性合并。名义上这是一桩“对等合并(Merger of Equals)”,Bank One 股东获得了合并后新公司 42% 的股份。戴蒙笑着吐槽外界总以为他是后来才执掌摩根大通的,但实际上从合并第一天起,他就统管着新公司超过 40% 的业务基本盘。
其实在接手 Bank One 之初,戴蒙就已经洞察到与 J.P. Morgan 合并是极具战略逻辑的必然路线。早在 2000 年 J.P. Morgan 与 Chase 宣布合并时,刚到 Bank One 的戴蒙看着市值 250 亿美元的自己和庞大数倍的新巨头(八九百亿美元规模),曾感叹合并梦碎。但四年之间,Bank One 股价翻倍,而对方估值回调,双方终于进入了对等谈判区间。时任 J.P. Morgan 董事长兼 CEO 的比尔·哈里森(Bill Harrison)正在寻找继任者,两人秘密磋商了一年半之久。
最终达成的并购协议在华尔街堪称罕见且强势:J.P. Morgan 赢得了公司的名称与总部所在地,Bank One 股东拿到了控制权溢价,而戴蒙则从第一天起就确立了实权——协议规定他在 18 个月后自动接任全行 CEO,除非由双方各出 8 席构成的 16 人董事会中有高达 75% 的绝对多数票反对,才能废除该继任条款。这笔交易当时引发了滑稽的双向诉讼:J.P. Morgan 董事会被股东起诉“买戴蒙花钱太多”,戴蒙则被 Bank One 股东起诉“卖身价太低”。谈及这块金字招牌,戴蒙坦承“J.P. Morgan”这一品牌宛如珠宝界的蒂芙尼(Tiffany),是无与伦比的瑰宝,不过在严谨的数字并购算式中,他并没有给品牌无形资产单列虚高的估值。
- **股权比例与对等合并**:Bank One 占合并后公司 42% 股份并享受收购溢价,J.P. Morgan Chase 保留品牌名与纽约总部。
- **罕见的 CEO 锁定条款**:18 个月后由戴蒙接任 CEO,只有 16 名董事(8 名来自 Bank One,8 名来自 JPM)中达到 75% 反对票才能阻止。
- **并购官司趣事**:J.P. Morgan 因“高价挖戴蒙”被控买贵了,戴蒙反被自己股东指控“卖便宜了”。
### [27:58](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1678s) 兼并与收购的前提:自身过硬与严谨的商业逻辑
杰米·戴蒙(Jamie Dimon)回顾接掌公司初期时谈到,当时董事会及外界许多人都以为他会立即展开大刀阔斧的并购交易。然而戴蒙当即泼了冷水:“不行,我们现在还很烂(no, we suck),我们还没赢得去经营别人公司的资格。”在他看来,企业只有先把自身业务经营好,才有底气去与别人合并。
谈及评估并购时的底层考量,戴蒙强调商业逻辑必须无懈可击。以与摩根大通(J.P. Morgan)的合并为例,双方业务版图高度重合且互补:双方都有零售银行业务,也都经营信用卡业务(当时表现都很差);摩根大通拥有顶级的投资银行,而芝加哥第一银行(Bank One)则拥有庞大的美国本土企业银行业务网络,急需这些投行服务的支持;此外双方均有财富管理部门。这种业务高度匹配意味着存在巨大的成本协同效应。
除了商业逻辑,决定成败的关键是执行力。市场上充斥着大量走向崩溃的失败交易——要么缺乏强有力的管理层,要么无法整合后台系统,要么内部派系林立互相倾轧(戴蒙顺带打趣提到花旗集团当年就是如此)。最后才是估值定价。虽然拥有像蒂芙尼(Tiffany)般高贵的顶级品牌,但如果基本面整合行不通,光有品牌光环也毫无价值。
---
### [29:00](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1740s) 2006年的华尔街狂欢:摩根大通的逆周期风控与去杠杆
时间推进到2006年,戴蒙正式出任合并后的摩根大通董事长兼首席执行官。彼时的华尔街陷入了极致狂欢,投机气氛宛如重回1980年代。在全行业都在疯狂加杠杆追逐高利润的当口,摩根大通却选择逆流而退,大幅收紧风险敞口。
戴蒙指出,2006年下半年市场便已初现裂痕,量化基金开始暴露出隐患,次级抵押贷款(subprime)资产质量也明显恶化。摩根大通果断砍掉了大量次贷风险资产。尽管事后看仍承受了一定损失,戴蒙甚至感慨“真希望当时砍得更狠一些”,但这家银行当时的杠杆率仅为华尔街其他大型投行的约三分之一,且在2006年便开始未雨绸缪地囤积流动性。
受会计准则和巴塞尔协议(Basel I / Basel III 演进阶段)的漏洞刺激,当时主要投行的杠杆倍数从原本稳健的12倍一路飙升至35倍甚至更高,大行们在担保债务凭证(CMO)和过桥贷款(bridge loans)上疯狂押注。戴蒙给出一组鲜明的对比数据:在2007年巅峰期,全华尔街的过桥贷款规模高达4,500亿美元,而如今整个市场仅约400亿美元——摩根大通一家现在的实力就能吃下这400亿美元总额。正是当年那些被极度杠杆化的劣质资产,在随后的房地产按揭市场全面崩溃中,将整个华尔街系统拖入了深渊。
---
### [30:43](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1843s) 扭转恶性激励:拆除投行部门的利益黑匣子
主持人提出疑问:在面对同样的市场暴利诱惑和同样的信息环境下,人的行为通常随激励机制而动,摩根大通究竟如何避免了被卷入毁灭?戴蒙直言,核心在于从企业内部彻底重构了薪酬与奖金的激励逻辑。
在戴蒙看来,员工绝不能以牺牲客户利益或公司长远安全为代价去追逐奖金。华尔街彼时充斥着各种长达三年、五年的特殊个人协议和“暗盘交易”(side deals),高管们只要承担超额风险就能中饱私囊。戴蒙上任后坚决废除了几乎所有这类个人定向挂钩机制:
> “在如今的摩根大通内部,没有心照不宣的眼神示意(no winks, no nods),没有任何私下小协议,也几乎没有任何人会单纯因为某单特定业务被单独重赏。”
很多交易员如果拿着资产包20%的利润分成,面对30倍杠杆时就会毫不犹豫推到40倍杠杆,因为杠杆每翻一档就直接给他的年终奖加码25%。戴蒙直接砍掉了这套20%利润提成机制和超额杠杆,哪怕这导致了一批资深高管愤然离职也在所不惜。他强调,管理层必须时刻反思机制是否诱导了背离客户价值与风险底线的“不良行为”。
```mermaid
flowchart TD
accTitle: 华尔街旧激励机制与摩根大通改革对比
accDescr: 对比传统华尔街投行的高杠杆利益驱动模式与戴蒙在摩根大通推行的风控与激励重塑机制。
subgraph WallStreet["传统华尔街激进模式"]
A["业务利润直接提成 (如20%分成)"] --> B["推升极端杠杆 (30倍至40倍)"]
B --> C["追求短期账面暴利"]
C --> D["风险爆发 / 机构爆雷"]
end
subgraph DimonModel["戴蒙领导下的摩根大通模式"]
E["取消私下协议与单一业务分成"] --> F["严控杠杆 (仅大型投行约1/3)"]
F --> G["提前囤积流动性 / 严格尽调"]
G --> H["抵御系统性危机"]
end
```
---
### [32:30](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1950s) 2008年3月13日:贝尔斯登生死72小时与每股2美元收购
2008年3月13日周四夜晚,一场足以引发多米诺骨牌效应的危机突然爆发。当天贝尔斯登(Bear Stearns)股价收于57美元(就在数月前它还在150美元上方)。正在第47街的 Avra 希腊海鲜餐厅为自己庆祝生日的戴蒙,接到了贝尔斯登首席执行官艾伦·施瓦茨(Alan Schwartz)的绝望求援电话。
施瓦茨在电话中急迫地表示:“杰米,我在今晚亚洲市场开盘前需要300亿美元。”戴蒙坦言自己根本不可能凭空变出300亿美元,并询问对方是否已经联系了美国财政部长汉克·保尔森(Hank Paulson)和纽约联储主席蒂姆·盖特纳(Tim Geithner)。挂掉电话后,戴蒙草草吃了几口便告别家人赶回办公室。当晚摩根大通拉响最高应急警报,上百名员工夜穿戴整齐重返工作岗位。
由于摩根大通和美联储在法律技术层面上都无法直接向一家濒临破产的机构直接借出300亿美元,团队连夜设计了一套过桥贷款方案:美联储将资金借给摩根大通,摩根大通以贝尔斯登的优质资产作抵押向其注资,硬生生撑过周五交易日,为周末的全面评估争取到了宝贵的48小时。
- **闪电尽调**:随后几天,数千名摩根大通专业人员涌入贝尔斯登,逐笔审查贷款、资产负债表、衍生品、诉讼记录及人事合同。
- **2美元作价**:周日晚间,摩根大通宣布以每股2美元的价格收购贝尔斯登,整个公司作价仅约10亿美元(而其不久前市值还达200亿美元)。
- **资产与隐患**:交易中摩根大通甚至以几乎为零的账面成本拿下了贝尔斯登位于曼哈顿麦迪逊大道383号、价值10亿美元的总部大厦,并吸纳了其核心团队;然而作为上市公司并购,极低的收购价直接招致了贝尔斯登原股东铺天盖地的诉讼。
---
### [35:02](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2102s) “我再也不会相信政府了”:拯救系统后的监管清算与妥协
虽然这笔收购避免了金融系统在2008年春天过早崩盘,但后续的痛苦远超想象。外界估算摩根大通最终为处置和清理贝尔斯登的烂摊子承担了150亿至200亿美元的代价。除直接资产冲销外,让戴蒙最感愤怒的是几年后美国联邦政府推翻以往默契,就贝尔斯登遗留下来的有毒次级按揭贷款向摩根大通提起诉讼,并处以高达50亿美元的巨额罚金。
戴蒙在现场坦言,换届后的政府完全无视前任政府的承诺与协作:“我们拯救了金融体系,救了那么多人,他们却反手让我们为贝尔斯登当年发放的坏账买单。”这一经历让他公开表示“我再也不会这么做了,我再也不会真正相信政府了”。
在被问及这种背离是否源自美国“四年一换届”的政治体制特性时,戴蒙确认新一届政府根本不会对自己前任的承诺承担任何道义或法律包袱,甚至在处理相关事务时直接践踏了既定合同。面对掌握国家机器绝对权力的联邦司法部门,戴蒙最终不得不选择低头。他回忆自己带着首席独立董事前往华盛顿会见时任司法部长埃里克·霍尔德(Eric Holder)商讨和解时,对方本以为戴蒙会拍桌叫板,然而戴蒙进门后的第一句话却是:
> “埃里克,我是来投降的(Eric, I am here to surrender)。我无法对抗联邦政府,我也赢不了联邦政府,这一点你心知肚明。”
### [036:51] “走向投降”与政府救助的代价
谈到金融危机后摩根大通(J.P. Morgan Chase)面临的监管追责与天价罚单,杰米·戴蒙(Jamie Dimon)坦言当时自己甚至做好了妥协的准备。他回忆当时直面司法部门时说道:“刑事起诉可能会毁掉我的公司。我绝不会让这种事发生在我的公司或我的国家身上。我是来投降的(I'm here to surrender)。”但他依然据理力争,要求对方弄清收购贝尔斯登(Bear Stearns)和华盛顿互惠银行(Washington Mutual,简称 WaMu)的真实背景——因为政府索赔与指控中80%的内容都源于这两家被摩根大通在危难中接盘的公司,而非摩根大通本身的业务。然而监管官员听完只是客套回应会予以考虑,最终却从未给出具体核算的细节。戴蒙无奈表示,整件事令人痛苦至极,但他深知必须继续向前看。
主持人指出,尽管账面上看这笔交易让摩根大通背负了沉重的代价,但危机期间树立的“救世主”信誉,正是如今摩根大通市值能高达约8000亿美元的关键基石。被问及如果历史重演是否还会接下政府的救市电话时,戴蒙展现出了典型的爱国者底色:“如果政府再次打电话说‘我们需要你拯救国家’,出于爱国心我当然还是会做。”但他随即开玩笑地补充道,下一次自己一定会提前设计好机制,“尽量避免被下一任总统惩罚”。现场顿时响起笑声,主持人也打趣建议道,以后的并购协议里必须写明“除非国会以75%的投票支持起诉,否则默认免责”。
- 戴蒙指出,危机后政府对摩根大通发起的指控与罚金中,有80%都源自贝尔斯登和 WaMu 遗留的问题,而非摩根大通自身的内生业务。
- 尽管面临巨大的政治反弹和惩罚性诉讼,戴蒙仍表示在国家需要时自己会毫不犹豫施以援手。
---
### [038:28] 华盛顿互惠银行的收购契机与“堡垒资产负债表”
贝尔斯登事件发生六个月后,雷曼兄弟倒闭仅一周,摇摇欲坠的华盛顿互惠银行便迎来了崩盘时刻。戴蒙指出,当时几乎所有银行董事会都吓得退避三舍,因为整个金融体系似乎都在解体。但摩根大通早已对其资产情况了如指掌,深知这是一次绝佳的版图扩张机遇。WaMu 拥有2300家零售网点,能一举填补摩根大通在加利福尼亚州、佛罗里达州和佐治亚州等高增长健康市场的空白。在交易架构上,摩根大通比有形账面价值折价约300亿美元收购了其业务,直接将债务留在了母公司实体中,而这300亿美元的折价恰好完全覆盖了预期的房贷坏账损失,从而实现了“干净资产”的并表。
完成收购后一两天内,戴蒙做出了一个令市场震惊且违背寻常商业直觉的举动:他直接面向资本市场再度增资配股,募集了110亿美元的股本。戴蒙解释,这并非因为当时缺乏资金,而是他极度保守的风险偏好使然。他时刻做好情况可能进一步恶化的准备,确保摩根大通在吃下 WaMu 之后的资产负债表依然与收购前一样坚不可摧。得益于长期积累的信誉,投资者在危机最深重的一个月里依然毫不犹豫地买单。
```mermaid
flowchart TD
accTitle: WaMu Acquisition and Capital Preservation Flow
accDescr: 摩根大通收购华盛顿互惠银行的交易架构与堡垒负债表策略
subgraph Acquisition["WaMu 收购架构"]
A["评估 WaMu 资产"] --> B["折价300亿美元收购优质业务与网点"]
B --> C["债务剥离留存母公司 / 坏账全额核销"]
end
subgraph Expansion["战略版图补强"]
B --> D["获取2,300家零售分支网点"]
D --> E["进军加州、佛罗里达、佐治亚等核心州"]
end
subgraph CapitalShield["堡垒资产负债表加固"]
C --> F["次日向市场增发110亿美元股权"]
F --> G["确保资本充足率与流动性绝对安全"]
end
```
- **收购估值折价**:以比有形账面价值(Tangible Book Value)折价300亿美元的价格完成收购,刚好抵消预期的按揭贷款损失。
- **增持资本金**:收购后48小时内紧急增发110亿美元普通股,用于维持充裕的流动性缓冲。
- **整合执行速度**:摩根大通调动了跨部门近5万人,仅仅用了9个月时间便将 WaMu 的2300家网点、系统、结算与薪酬体系彻底并网整合。
---
### [041:17] 华尔街的周期性爆炸与当下的系统性隐忧
当被问及为什么“堡垒资产负债表”这种显而易见的审慎策略没有被同行普遍照搬时,戴蒙指出,许多机构总是难逃激进会计手法的诱惑,在承压测试时自欺欺人,承担了过高的利率风险、信用敞口与期权风险。他回顾金融史,指出每一次行业爆炸往往都始于未经历过完整经济周期的新型金融产品——从1929年的股票融资、期权、股权衍生品、按揭抵押证券,到曾经甚至引发爆仓的政府保证吉利美(Ginnie Mae)债券、量化策略(Quant)和杠杆贷款。
谈及当下规模已达2万亿美元、受市场热议的“私人信贷”(Private Credit)是否会重蹈覆辙,戴蒙认为私人信贷行业内确实有优秀且专业的操盘手,客户需求也很旺盛,虽然伴随野蛮生长必将出现局部违约爆雷,但整体并不具备当年的系统性毁灭风险。他对比指出,次贷危机时按揭贷款市场规模高达9万亿美元,损失超过1万亿美元,且叠加了多重杠杆。眼下真正让他警惕的是整体资产估值的高企(标普市盈率处在23倍的高位,而非低风险的15倍)以及信用利差的收窄;而在所有宏观隐患之上,戴蒙认为最大的潜在威胁是网络战(Cyber Risk)。摩根大通每年在网络安全上耗资约8亿美元,但他极度担忧美国在电网、供水、通信和军事设施上的防护能力在遭遇大国地缘对抗网络攻击时会不堪一击。
- 资产估值对比:市盈率(P/E)在15倍时下行空间有限、上行空间可观;而处在23倍时则上行空间狭窄、下行下跌风险巨大。
- 网络安全投入:摩根大通每年在网络防护上投入超8亿美元,戴蒙认为电网、水务、通信基础设施的脆弱性是面临地缘威胁时最严峻的问题。
- 压力测试频率:摩根大通内部每周推演多达约100种不同的极端宏观压力情景。
---
### [044:12] 2023年银行业风暴:硅谷银行与第一共和银行的倒闭根源
时间推进到2023年春季,硅谷银行(Silicon Valley Bank,简称 SVB)与第一共和银行(First Republic Bank)相继轰然倒下,摩根大通再次出面接盘第一共和银行。戴蒙复盘了这场危机的深层机制,指出外界常将其归咎于“未投保存款”(Uninsured Deposits),但核心本质其实是极其致命的“高集中度存款”(Concentrated Deposits)。在风投生态圈中,数百甚至上千家风险投资机构(VC)步调一致地向被投企业客户发出撤资通牒,引发了前所未有的数字化挤兑。
在这场极速挤兑中,拥有约2000亿美元存款的硅谷银行竟然在短短一天之内被抽走了1000亿美元。除了存款端极度单一脆弱之外,这些银行在资产端更犯了灾难性的管理错误:未向美联储贴现窗口足额质押抵押品以备流动性,并在低息时代承担了极高的利率风险敞口。戴蒙严厉批评了“持有至到期”(Held-to-Maturity,简称 HTM)这一会计分类,认为该规则虽能在账面上粉饰监管指标、免去国债按市值计价(Mark-to-Market)的浮亏,却掩耳盗铃地掩盖了资产实际市值的缩水,最终在遭遇流动性挤兑时让脆弱的资产负债表原形毕露。
- **存款集中挤兑**:数千家风投系企业在VC警告下集体抽资,导致硅谷银行在单日之内被提取1000亿美元存款,占其2000亿美元存款总额的半壁江山。
- **内部管理缺陷**:未在美联储贴现窗口做好充足合格抵押品储备,无法在危机爆发时获取紧急流动性。
- **HTM 会计弊病**:通过“持有至到期”(HTM)规避账面浮亏标记,掩盖了利率上行对债券投资组合造成的真实净值损害。
### [45:43](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2743s) 硅谷银行危机与收购第一共和银行的内幕
Jamie Dimon 深入复盘了 2023 年美国区域性银行危机的核心症结:利率风险与按市值计价(mark-to-market)的残酷现实。他解释道,一家银行如果名义账面价值是 100,但只要对其持有的长期低息资产进行按市值计价,其有形账面价值(tangible book value)可能瞬间腰斩到 50,甚至跌至 30 到 40 美分。监管机构当时误导性地暗示利率将长期保持低位,促使这些银行大量买入收益率仅为 3% 的抵押贷款支持证券;当市场利率飙升至 5% 时,这些资产在二级市场上的实际价值只剩五六成。Dimon 指出,无论是管理层还是监管机构,事前都清楚这种极端的利率敞口风险,这本是完全可以预防和化解的。
谈及硅谷银行(Silicon Valley Bank)时,Dimon 承认摩根大通此前一直在该领域尝试竞争,但从危机中汲取了大量经验教训,迅速升级了对风险投资生态圈的服务能力。如今摩根大通在帕洛阿尔托(Palo Alto)设立了专门园区,聘请了 500 名专注于创新的银行家深入覆盖风投圈。而对于第一共和银行(First Republic Bank),摩根大通很早就紧密监控其风险。Dimon 甚至亲自致电财政部长珍妮特·耶伦(Janet Yellen),明确警告第一共和银行等机构深陷危机,并表态摩根大通愿意接盘以彻底消除系统性隐患。虽然监管方犹豫拖延致使资产如同“融化的冰棒”,但摩根大通一旦完成收购,问题便被迅速平息——几天之内完成所有风险对冲,计提资产减值并深度整合。不仅如此,摩根大通还留用了其核心团队,并将其标志性的超高净值客户专属服务理念全盘吸纳,在麦迪逊大道等地开创了全新的“J.P. Morgan 金融中心(JP Morgan Financial Center)”,将零售银行、中小企业贷款、房屋按揭乃至高端旅行礼宾服务融为一体。
- 资产减值致命伤:3% 票息抵押贷款在利率涨至 5% 时市值暴跌至票面的 50% 到 60%,导致有形账面价值断崖式下跌。
- 风险投资生态圈布局:摩根大通设立帕洛阿尔托新园区,配备 500 名创新银行家全面渗透 VC 及初创企业客户。
- 闪电拆弹第一共和银行:收购后数天内完成所有风险敞口对冲,平息市场恐慌。
- 财富中心拓展:基于第一共和银行的单一服务网点模式,摩根大通已设立约 20 家高端金融中心,未来计划在 20 年内扩建至 300 家。
---
### [47:58](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2878s) 为什么摩根大通能拉开差距:像社区银行一样协同生态
面对主持人的提问——究竟是什么让摩根大通彻底拉开与竞争对手的距离,成为一个完全不同的物种?Dimon 给出了一个出人意料的答案:摩根大通的底层逻辑与一家优质的“社区银行”别无二致,区别仅在于多了一套顶级全球投资银行业务。传统的社区银行深谙镇上每一个居民和企业主的需求,商业账户、个人账户和信托业务融为一体,不需要复杂昂贵的 Salesforce CRM 系统,因为“客户关系系统就装在行长和信贷员的脑子里”。摩根大通的核心战略正是让所有业务板块有机咬合、互相滋养(feed each other),坚决不保留任何与主营业务无关的赘瘤。
Dimon 尖锐地对比了昔日花旗集团(Citigroup)的教训。在桑迪·韦尔(Sandy Weill)执掌时期,花旗狂热追求规模扩张,盲目拼凑消费信贷、人寿保险、财险,甚至为了做大规模收购了经营卡车租赁业务的美国通用(American General)。这种跨界拼图让管理层根本无法洞察各板块内部潜藏的致命风险,最终不得不全面剥离。Dimon 坦言自己痛恨把公司业务当作“业余爱好”,摩根大通只做战略吻合的实业;即便市场像手风琴般来回剧烈拉扯,公司也始终坚守“堡垒级资产负债表”(Fortress balance sheet)与严谨会计准则,将资本持续倾注于三项核心资产:人才、网点与技术。由 Doug Petno 与 Troy Rohrbaugh 等高管挂帅的商业银行与投行业务已成功开辟至欧洲全境,形成强大的跨国业务飞轮。
```mermaid
flowchart TD
accTitle: 摩根大通核心业务协同飞轮架构
accDescr: 展示零售银行、中型市场商业银行、全球投行与私行业务之间相互引流、协同滋养的闭环模式
subgraph CoreEngine["协同底层支撑"]
F1["堡垒级资产负债表 (Fortress Balance Sheet)"]
F2["持续投入:人才、网点与技术"]
end
subgraph BusinessEcosystem["互相滋养的业务生态 (Feed Each Other)"]
CB["商业中型市场业务<br/>(Middle Market Banking)"]
IB["全球投资银行业务<br/>(Global Investment Banking)"]
Retail["零售与消费者银行<br/>(Consumer & Small Business)"]
Wealth["财富管理与外汇服务<br/>(Private Banking & FX)"]
end
CB -->|"输送并购/发债需求"| IB
IB -->|"提供外汇与对冲工具"| CB
Retail -->|"沉淀存款并导流高净值"| Wealth
Wealth -->|"反哺零售与按揭生态"| Retail
CB -->|"企业主个人业务衍生"| Wealth
IB -->|"全球清算与协同"| Retail
CoreEngine -.-> BusinessEcosystem
```
- 业务协同准则:中型市场客户采购投行产品,零售客户使用外汇(FX)服务,坚决剔除不产生战略协同的无关资产。
- 拒绝无序扩张:对比花旗涉足卡车租赁等业务导致风险失控,强调金融机构必须能够看清底层业务实质风险。
- 长期资本投入三要素:不随周期波动而中断,坚定投资于人员配置、分支机构扩张(包括欧洲商业银行业务)与底层金融科技。
---
### [51:04](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3064s) 效率比率的秘密与长期主义文化
主持人提出,深入剖析摩根大通的财务报表时,最惊人的指标是其效率比率(efficiency ratio):相比竞争对手,摩根大通每赚取 1 美元收入,能比同行多截留整整 15 美分的利润。Dimon 澄清,这种超额利润率绝不是靠偷工减料或削减开支挤出来的;相反,摩根大通是在保持庞大战略投资的同时实现这一利润率的。如果单纯为了迎合短期账面,他明天就可以削减数十亿美元的市场营销费用,或者停止开设新网点,明年立刻能省下 10 亿美元使当期利润率飙升,但这会以牺牲未来增长和长期利润率为代价。
Dimon 强调,摩根大通追求的是穿越周期的“真实经济学”(actual economics),而不是浮于表面的会计技巧。他打趣道,每年公司的投资者日(Investor Day)上,他从不亲自登台做 PPT 汇报,而是在台下看着管理团队把摩根大通的核心做法巨细靡遗地讲给外界听,心里总忍不住感叹“天呐,我们透露了太多机密配方”。随后,他借现场前排就座的星巴克创始人霍华德·舒尔茨(Howard Schultz)为例,指出卓越企业的真正护城河是日复一日在每个网点、每件产品上的专注、好奇心与爱心。Dimon 借用体育竞技做对比:像汤姆·布拉迪(Tom Brady)这样的巨星在日常训练中每一天都在全力以赴;在商业世界里人们可以用漂亮的汇报来夸夸其谈(BS),但在真正的赛场上,一支充斥着自私混蛋、互不协作的球队绝不可能赢得冠军。
---
### [53:29](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3209s) 坚守一线的原动力
访谈进入尾声,主持人向 Dimon 抛出了最后一个触及灵魂的问题:回望 2008 年金融危机甚至更早的 2001 年,当时与他同台竞技的其他华尔街领袖和各大银行掌舵人如今早已全部退休,就连摩根大通内部许多同代老将也已告别职场;而 Dimon 依然保持着一如既往的高强度工作状态,全情投入。究竟是什么促使他坚守至今?面对这一提问,Dimon 首先深情地向坐在台下的妻子表达了感谢,动情地表示如果不是妻子多年来默默承受这一切并给予坚定支持,自己绝不可能走到今天。
### [54:08](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3248s) 杰米·戴蒙的人生哲学与卸任展望
杰米·戴蒙(Jamie Dimon)坦言,如果没有妻子的支持,自己绝不可能走到今天。他回忆道,自己的祖父母都是希腊移民,连高中都没有读完,但希腊人骨子里有一种代代相传的伦理道德;而妻子朱迪(Judy)的家庭也是如此。这种价值观的核心在于:人生一定要拥有使命感(purpose)——无论投身于艺术、科学、军事、商业,还是成为一名优秀的父母或教师,都必须竭尽全力,切忌整天怨天尤人;同时要善待身边的每一个人,如果在生活中看到有恶霸欺凌弱小,必须挺身而出,绝不能坐视不管。
谈及自己的人生排序,戴蒙给出了清晰的三层阶梯:排在第一位且永远最重要的是家庭;第二是国家,他坚信美国是不可或缺的伟大国度,为世界带来了言论自由、宗教自由和企业自由,而这份价值需要不断向世人重申;第三才是自己的事业与使命。戴蒙笑称,家里人其实也不希望他每天无所事事待在家里,而在摩根大通(J.P. Morgan)的工作让他能够为城市、州政府、学校、企业和广大员工提供实质帮助,这带给他极大的成就感。只要精力充沛,他就会一直干下去。当被女儿调侃“需要培养一些爱好”时,戴蒙反驳说,自己其实喜欢陪伴家人、旅行、烤肉、品尝葡萄酒和威士忌,热爱阅读历史,也喜欢徒步,只是因为背伤无法再打网球,但他对豪车这类奢华之物毫无兴趣。谈到未来真正从摩根大通退下之时,他表示自己不会无所事事地“去数拇指或闲着闻花香”,可能会去教书、做些有意义的事,甚至像安德鲁·罗斯·索尔金(Andrew Ross Sorkin)那样写一本书。当主持团队暗示多年来外界一直呼吁他参选或从政、目前似乎只剩唯一一个职位在影响力上能超越他现有的岗位(意指美国总统)时,戴蒙心领神会地幽默回应,引来全场热烈掌声。
```mermaid
flowchart TD
accTitle: Jamie Dimon's Hierarchy of Life
accDescr: Jamie Dimon's three priorities in life starting with family at the top, followed by country, and then purpose through work.
subgraph Priorities["杰米·戴蒙的人生优先级"]
F["第一顺位:家庭 (Family)<br/>永不动摇的核心根基"]
C["第二顺位:国家 (Country)<br/>捍卫言论、信仰与企业自由的不可替代之国"]
P["第三顺位:事业与使命 (Purpose)<br/>通过摩根大通赋能城市、企业与员工"]
F --> C
C --> P
end
```
### [57:17](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3437s) 中场休息与安德鲁·罗斯·索尔金登台
在戴蒙离场后,现场进入了短暂的中场环节,大屏幕播放了赞助商 ServiceNow 和 Shopify 的品牌短片,展现了企业级 AI Agent 以及电商创业者的故事。随后,《纽约时报》(The New York Times)知名金融专栏 DealBook 创始人兼 CNBC《财经论谈》(Squawk Box)联合主播安德鲁·罗斯·索尔金(Andrew Ross Sorkin)突然出现在舞台的主持桌后,开玩笑宣称这是“DealBook meets Squawk Box meets Acquired”的深夜联名现场。
看到索尔金反客为主坐在主播台,重新上台的本(Ben Gilbert)和大卫(David Rosenthal)故作疑惑,表示今晚的主题是深夜脱口秀风格、专访纽约标志性企业 CEO,这套桌椅本该是他们的地盘。索尔金则笑着打趣说,听说今晚要聊《纽约时报》,而自己正是在纽时长大的老兵,所以特地来帮忙提供笔记和问题。不过为了测试两位主播是否有资格主导接下来的访谈,索尔金当场出了一套“纽时知识小测验”:
- **创立年份**:纽时创办于哪一年?本秒答 1851 年,完全正确。
- **守卫大楼历史**:当年是谁曾在纽时大楼楼顶持枪抵御暴徒?大卫抢答是阿道夫·奥克斯(Adolph Ochs),索尔金纠正称是最初的联合创始人亨利·雷蒙德(Henry Raymond),不过奥克斯作为后来买下报社的人也能拿到风格分。
- **地标命名**:纽约哪处标志性地标是以纽时命名的?答案显而易见是时代广场(Times Square)。
- **最标志性的现代 CEO**:索尔金随即隆重请出纽时历史上最具标志性的现代掌门人——《纽约时报》首席执行官梅雷迪思·科皮特·莱维恩(Meredith Kopit Levien)。
### [01:00:36](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3636s) 纽时 CEO 梅雷迪思·科皮特·莱维恩:从生死边缘到全球巨擘
在全场欢呼中,梅雷迪思·科皮特·莱维恩登台。送走次日清晨 6 点还要赶回 CNBC 直播早间节目的索尔金后,访谈正式展开。本和大卫回顾了纽时的惊险逆袭:在 2008 年金融危机期间,纽时一度濒临崩溃边缘,不得不将总部大楼售后回租;而仅仅十余年后,纽时不仅成为全球最大的数字订阅报刊,也是全球仅存的独立上市报业巨头,市值创下近 100 亿美元的历史新高。
距离 Acquired 在 2021 年制作长达三小时的《纽约时报》专题节目已过去四年,本询问莱维恩这几年间订阅业务的最新进展,以及自 2014 年那份彻底改变报社命运的《创新报告》(Innovation Report)发布以来,公司战略的变与不变:
- **订阅规模爆发式增长**:2021 年播客录制时,纽时的订阅用户数约为 500 万;如今这一数字已逼近 1200 万,营收与利润双双攀升,更重要的是其新闻与文化影响力也在持续扩大。
- **受众覆盖网络**:目前每周有 5000 万至 1 亿独立访客访问纽时网站和 App;约 2000 万人收听播客或阅读电子邮件新闻简报;累计注册用户数已突破 1.5 亿大关,展现出极强的用户黏性与转化池。
- **2014 年以来的业务蜕变**:莱维恩指出,2014 年公司确立了“成为人们日常生活中不可或缺的一部分”的长期战略。彼时纸质版报纸依然是商业营收的绝对主引擎,纽时虽然拥有顶尖的新闻采编水准,但在数字化读者获取与受众运营上却被原生的数字新闻初创媒体打得节节败退。
- **收入结构翻转**:如今两者的地位已经完全倒置,纸质报纸在总营收中的占比已被压到 30% 以内(实际约为 25% 左右),数字化业务已经挑起公司发展的绝对大梁。
### [01:04:27](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=3867s) 从防守转向进攻:现代《纽约时报》的版图重塑
《纽约时报》CEO 梅雷迪思·科皮特·莱文(Meredith Kopit Levien)指出,公司不仅将在未来长期繁荣存在,而且其产品矩阵在各维度上都迎来了巨大扩张——涵盖了更多的报道范围、话题与内容形态,以全新方式融入人们的日常生活。在企业文化层面,时报经历了根本性转变,从“被动防守”彻底走向了“全面进攻”。回顾 2014 年前后,公司还在为能否摆脱单纯的传统报纸形态而背水一战;而如今,定义时报的是其宏大的野心:探索《纽约时报》以及新闻业在人们的生活中究竟能发挥多大的潜能与价值。
面对主持人关于“时报是否已超越传统新闻,成为按订阅用户数计全球最大的第一方内容公司”的提问,莱文给出了清晰的战略定义:时报的目标是成为全球所有充满好奇心、渴望理解并融入世界的读者“不可或缺的订阅产品”(the essential subscription)。为了实现这一目标,时报围绕三大支柱构建闭环:
- 坚定不移地打造“全球最佳新闻目的地”;
- 依托自研与并购,构建多款市场领先的生活方式与垂直产品(烹饪、游戏、体育、消费指南),帮助读者过好生活并发展爱好;
- 将上述所有业务整合进统一互通的会员组合包(Bundle),让《纽约时报》在用户生活的各种时刻都能持续输出价值。
```mermaid
flowchart TD
accTitle: The New York Times Bundle Strategy
accDescr: Diagram showing how core news and lifestyle products feed into an integrated subscription bundle.
subgraph Core ["核心业务"]
News["全球最佳新闻报道<br/>(Hard News)"]
end
subgraph Expansion ["高频垂直产品矩阵"]
Wirecutter["Wirecutter<br/>(现代消费者报告)"]
Athletic["The Athletic<br/>(全球最大体育编辑室)"]
Games["Games & Wordle<br/>(益智游戏)"]
Cooking["Cooking<br/>(烹饪与菜谱)"]
end
subgraph Ecosystem ["互通飞轮"]
Bundle["统一互联会员体验<br/>(Connected Bundle)"]
end
News --> Bundle
Wirecutter --> Bundle
Athletic --> Bundle
Games --> Bundle
Cooking --> Bundle
Bundle -.->|"流量与内容双向互哺"| News
```
### [01:06:44](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4004s) “自研与收购”:成功打造跨界护城河的逻辑
主持人和莱文探讨了多数媒体公司跨界往往折戟的痛点,询问时报为何能连续在烹饪、购物导购等五到七个领域取得成功。莱文分享了时报在并购上的成功范例:现代消费品评测标杆 Wirecutter、拥有全球最大体育采编团队(超 550 名专业记者)的 The Athletic,以及被誉为神来之笔的游戏 Wordle。值得一提的是,Wordle 是在收购 The Athletic 的同一周被迅速拿下的,两者交易金额差距悬殊(数亿美元对比数百万美元区间),但都极为成功。
莱文总结了这些成功业务的共同特征:
- **依托庞大市场空间**:体育、游戏、消费指南以及食谱每一个赛道本身都有极其巨大的用户基数与商业空间。
- **提供稀缺且高价值的体验**:例如 The Athletic 深入更衣室的核心深度报道,满足了硬核体育迷其他渠道无法替代的需求,因而成为时报目前增长最快的用户群体。
- **切入高频日常场景**:无论是每天做饭、日常购物还是玩小游戏,用户与产品的互动频次极高。仅 Wirecutter 一项,去年就驱动了约 10 亿美元的商品交易总额(GMV)。
- **协同效应与双向互哺**:读者往往因为玩一款游戏或查一个菜谱进入应用,随后顺手阅读关于乌克兰战争的深度深度报道,二者形成完美飞轮。
### [01:09:06](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4146s) AI 时代的坚持:以人为本的报道与大模型版权维权
在 AI 迅速重塑内容生产的今天,时报依然是一家由专业人士亲自把关与策展的媒体。莱文指出,新闻报道归根结底是一项“人对人”的事业——哪怕无人机能够拍摄前线废墟,也永远替代不了一个有血有肉的记者亲临战场第一线,去倾听、共情并记录受灾民众的真实声音。
同时,时报对 AI 技术的态度绝非抗拒,而是视其为整体业务的“放大器”(force multiplier)。莱文以自身为例,透露自己晨跑时就会使用 AI 语音功能收听文本报道;采编团队也使用 AI 算法对海量公共文档与公开档案进行高效筛选。AI 的核心价值在于赋能 3000 名专业新闻工作者,而不是取代他们。然而,这一切健康发展的前提是:大模型厂商绝不能侵占与挪用人类耗费巨额人力物力创作的智力成果。
针对《纽约时报》起诉 OpenAI 和微软未授权使用时报内容训练大模型一案,莱文掷地有声地指出了诉讼背后的核心逻辑与法律立场:
- **商业公平与价值交换**:大模型开发商在算力、能源以及顶级人才上砸下了数以千亿美元计的真金白银,因此他们理应为赖以训练模型的优质核心内容支付公平对等的合理报酬。
- **全美创作者知识产权的底线**:这绝非仅关乎新闻机构的存亡,更是关乎所有作家、艺术家及知识产权创作者生态的繁荣,直接关系到国家竞争力的基石。
- **拥抱合规合作**:时报并非一概排斥合作,前提是拥有可持续的公平价值交换机制,并保证内容可控性(如近期时报与亚马逊达成的授权合作)。
### [01:13:39](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4419s) 事实核查与媒体中立性:直面“反科技/反商业”偏见的质疑
当主持人提起外界(尤其科技与创投圈)常感知到的时报存在所谓“反科技(anti-tech)或反商业(anti-business)偏见”时,莱文首先礼貌地挑战了这一预设的普遍性,随后明确予以否认:“这绝不是事实。”
莱文阐述了《纽约时报》的核心立足点:新闻的使命在于“不偏不倚地追寻真相,无论真相指向多么令人不安的地方”。调查性报道的核心工作就是挖掘对大众至关重要的新事实。面对各种主题中随处可见的偏见指控,时报投入了极其巨大的精力、资金与科学流程来最大限度消除报道过程中的主观偏差。时报内部维持着庞大的新闻规范标准运作体系(standards operation),从信息源的合法可信度到多方事实交叉印证,每一个环节都有严格的专业红线守护。
### [01:14:57](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4497s) 科技巨头的报道标准与新闻业态的演进
Meredith Kopit Levien 深入探讨了《纽约时报》(The New York Times)对事实核查的严苛标准与对科技行业的报道哲学。她指出,事实要么经得起验证,要么根本算不上事实;在《纽约时报》,任何一篇刊发的报道都必须至少经过两位编辑的严格把关。谈及科技行业,她特别强调,如今塑造整个信息生态系统的大型科技巨头,其掌控的权力、影响力和深刻重塑大众生活的能力,已经堪比甚至超过许多国家或政府。正因如此,《纽约时报》才会以对等甚至更全面的规格去监督和报道它们。比如该报曾推出关于人工智能(AI)的大型专题策划,站在当下视角探讨 AI 将如何深刻影响普通人的生活,其中既有审慎的批判,也有大量篇幅客观展现 AI 即将带来的美好前景。她深信,让公众更全面地看到像 Andrew Ross Sorkin 这样的记者在背后付出的调查与求证努力,就能赢得更多信任。从金融危机至今的 15 年间,科技已从曾经的边缘或普通单一产业,一跃成为占据美国乃至全球资本市场绝大部分市值的庞然大物。
```mermaid
flowchart TD
accTitle: 纽约时报多媒介传播与信任建立闭环
accDescr: 展示纽约时报如何通过严格编辑、多媒介传播、幕后呈现进而建立深层用户信任
subgraph Core ["新闻采编核心"]
A["严苛采编准则<br/>(每篇报道至少双人编辑把关)"]
B["全方位客观审视<br/>(如大型 AI 专题)"]
end
subgraph Media ["多媒介传播"]
C["音频播客与移动视频<br/>(The Daily / Hard Fork 等)"]
D["解构传统报纸体裁<br/>(对话式叙事、记者幕后讲述)"]
end
subgraph Value ["受众价值沉淀"]
E["展现调查过程与信源求证"]
F["建立深层次亲切感与读者信任"]
end
A --> B
B --> C
C --> D
D --> E
E --> F
```
- **事实把关机制**:《纽约时报》的每篇稿件均至少由两位编辑审核,确保每一条可核实事实的准确性。
- **科技权重变迁**:过去 15 年间,科技行业从金融危机时期的普通门类,跃升为贡献全美及全球大部分市值的万亿级支柱行业,这也是 Acquired 等播客受到广泛关注的核心时代背景。
---
### [01:16:21](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4581s) 从报纸到播客:对话式叙事与受众信任的重构
谈到媒介形态从纸媒向多渠道的演变,Meredith 回忆起 12 年前刚加入《纽约时报》时的往事。当时她陪同 Andrew Ross Sorkin 在后台候场(准备见广告客户),就在他登台前一刻,Meredith 抓住他嘱咐:“千万别只谈‘报纸’(Don't talk about the paper)。我们不只是一家报纸公司。”对《纽约时报》而言,不论载体是文字、视频还是音频,根本目的都是用最优质的内容去触达并连接最广泛的人群。在这一策略中,播客发挥了举足轻重的作用,不仅拥有《The Daily》、《The Ezra Klein Show》以及被视为保守派视角的《Interesting Times with Ross Douthat》等头部王牌节目,还深化了核心读者的黏性,吸引了数以百万计的新受众。
Meredith 坦言,听播客就像结识了跑步搭子(running partners),她自己就曾戴着耳机听着 Ben 和 David 的声音跑过无数里程。当一线调查记者登上《The Daily》,用日常对话的方式向听众拆解当天头版报道时,他们不仅是以更轻松的朋友口吻引导新闻,更向受众透明公开了这篇报道背后的艰辛采掘与核实过程,这是建立信任最有力的手段。
此外,播客主持人之间的闲聊与插科打诨(banter)构成了极具价值的“寓教于乐”(entertainment-instruction)。例如《纽约时报》报道 AI 的播客《Hard Fork》(由 Kevin Roose 与 Casey Newton 主持),Meredith 作为一家必须应对 AI 浪潮的掌舵人期期必听,并被两位主播的互动深深吸引。Ben 与 David 补充道,这正是 Acquired 的“对话式叙事”(conversational storytelling)核心——通过两个人的对谈构建完整的故事线。这种更具口语化、平实风格的音频实验,也反哺并打破了传统报纸文章僵硬呆板的书写框架,赋予了现代文字报道更宽广自由的表达空间。
---
### [01:20:15](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4815s) 现场挑战:Acquired 定制版 Wordle
对话告一段落后,Ben 和 David 为 Meredith 准备了一个特别环节。既然以游戏业务为开场谈到了《纽约时报》的游戏板块,而 Wordle(字谜游戏)又占据了广大受众海量的日常生活时间,Acquired 团队特意邀请《纽约时报》游戏团队量身定做了一个深度关联 Acquired 经典节目的定制版 Wordle。Meredith 欣然戴上老花镜应战,打趣称自己其实更擅长《Connections》(连线游戏),因为玩 Wordle 总是被她母亲“虐得很惨”。
在台下观众与大屏幕镜头的注视下,Meredith 输入了自己常用的首发测试词,结果并不理想;随后她又连续尝试了几个词来测定字母分布。眼看猜测次数告急,Ben 和 David 开始给予提示:
- 该谜底是一个人的姓氏(Last name)。
- 这个人可以说是一家传奇公司的创始人。
- 这家公司是当今全球最大零售巨头之一的前身。
在几轮线索与字母排查下,Meredith 凭借精准的测试策略(甚至自我打气“Go me on Bripe!”)成功锁定了正确答案。全场随即响起了热烈的掌声与欢呼,Meredith 在舞台乐声中致谢退场。
---
### [01:22:45](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4965s) 观众互动竞猜:谁是 Acquired 史上收听之王?
送别 Meredith 后,Ben 和 David 开启了今晚的特别观众互动环节,向无线电城音乐厅(Radio City Music Hall)全场观众抛出一个压轴悬念:在 Acquired 走过的十年历程中,**历史上收听量最高的单集究竟是哪一集?**
现场观众纷纷开始大声抢答。David 环顾台下,一眼认出了坐在前排的熟人——独角兽企业 Vanta 的联合创始人 Christina Cacioppo。作为有着 9 年“老粉”(OG)资历的忠实听众,Christina 接过麦克风,给出了她的首个猜测:
- **猜想一**:是否是奢侈品巨头爱马仕(Hermès)那一集?
- Ben 和 David 回应:爱马仕集的收听量确实极度靠前,但目前并不是绝对的第一名。
紧接着,David 又在台下发现了一位举手的老朋友——腕表权威网站 Hodinkee 的创始人、全球顶级腕表专家 Ben Clymer。Ben Clymer 曾在 Acquired 制作具有标杆意义的劳力士(Rolex)单集时提供了大量不可替代的深度研究与专业支持。走上麦克风的 Ben Clymer 半开玩笑、信心满满地反问道:“那绝对得是劳力士(Rolex)那一集,对吧?”全场顿时响起会心的笑声与掌声,静待最终答案揭晓。
### [01:24:32](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5072s) 最受欢迎的单期节目与特邀嘉宾登场
在与现场观众互动的趣味问答环节中,台下的一位特别观众打破了悬念——星巴克前首席执行官兼名誉董事长霍华德·舒尔茨(Howard Schultz)笑着说道:“我可不这么认为,我觉得是我做嘉宾的那期。”全场随即爆发出热烈的掌声与笑声。这一猜测被立刻证实,霍华德加盟的那期星巴克长篇商业特辑以 130 万次下载量,荣登 Acquired 创办以来的历史收听冠军。台下的摩根大通 CEO 杰米·戴蒙(Jamie Dimon)不甘示弱地打趣喊道“到目前为止而已(So far)”,引得主持人们开玩笑表示他“胜负欲极强”,并承诺第二天就向他汇报当期节目的数据进展。
紧接着,主持人隆重请出了当晚压轴的重量级对谈嘉宾。这位传奇人物在超过 60 年的职业生涯中,掌舵或深度影响的商业帝国跨越了传统媒体与互联网科技两个时代,涵盖 20 世纪福克斯(Fox)、ABC 广播公司、派拉蒙影业(Paramount)、Expedia、Tinder、Match.com、电视购物频道 QVC、家庭购物网(HSN)以及票务巨头 Ticketmaster 等等。不仅如此,他与妻子黛安·冯芙丝汀宝(Diane von Fürstenberg)更是纽约市最重要的慈善家与建设者之一,一手资助并打造了高线公园(The Highline)和哈德逊河上的漂浮公园“小岛”(Little Island)。在观众的掌声与欢呼声中,IAC 董事会主席巴里·迪勒(Barry Diller)走上舞台。
### [01:26:41](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5201s) 迪勒的幽默开场与在纽约开车的怪癖
登台入座后,巴里·迪勒立刻展现出他特有的冷面幽默。看到沙发椅上的配置,他直接向主持人发问:“为什么她(上一位嘉宾)有靠垫而我没有?”主持人们连忙解释是对方主动要求的,并打趣道下次一定会写进接待要求(rider)里;迪勒则调侃称自己的接待清单其实只有一瓶水。
对谈随即聊到迪勒的日常生活。尽管身为百亿富翁,迪勒在纽约却几乎从不依赖专职司机,而是选择自己开车穿梭在曼哈顿街头。主持人好奇他如何在停车位极为紧张的纽约找到车位,迪勒风趣地自曝秘诀:自己总是直接在街头找空隙,哪怕旁边立着消防栓或其他障碍物,也会毫不客气地把车挤进去。当主持人调侃说“如果你给纽约捐建了一座岛,难道不能享有专属停车特权吗”时,迪勒大笑着回应:“并没有,我只拿到了违章罚单,不过总有一天我会去把它们付清的。”
### [01:27:32](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5252s) 1961 年老好莱坞与威廉·莫里斯的“收发室大学”
巴里·迪勒的人生第一篇章始于好莱坞黄金时代的尾声。1961 年,年仅 19 岁的迪勒进入著名的威廉·莫里斯经纪公司(William Morris Agency, WMA)从最底层的收发室做起。回忆起那个时代,迪勒感慨那时的好莱坞就像“1861 年”一样遥远,虽然已经有了打字机等基本技术,但整个行业仍由那些创立好莱坞的传奇电影大亨(Moguls)所统治。尽管当时像卢·沃瑟曼(Lew Wasserman)和西德·辛伯格(Sid Sheinberg)等新一代掌权人已在崛起,但旧时代的巨头们仍苟延残喘。迪勒甚至在 20 世纪福克斯创始人达里尔·扎纳克(Darryl Zanuck)迟暮之年与他有过荒唐的交集:当时已跳槽到 ABC 的迪勒负责为电视台采购电影,扎纳克叼着一根足有“20英尺长”的巨型雪茄,在能容纳 500 人的私人放映室里拉着迪勒看片——扎纳克需要电视台买单,才能给他的历任小女友们投资拍摄粗制滥造的福克斯烂片,以此维系感情。
谈及跨界经历,迪勒是从传统媒体起步并取得顶尖成就、而后又成功跨入互联网科技领域的最罕见代表。而这一切商业敏锐度的源头,竟来自威廉·莫里斯经纪公司的档案室。当时那间大房间里陈列着约 50 个巨大的金属档案柜,里面封存着作为行业鼻祖的经纪公司近 70 年来所有的纸质通信底稿。在 19 岁到 22 岁整整三年间,迪勒以惊人的毅力把档案柜里的文件从字母 A 到 Z 全部通读了一遍。
- **档案研究的商业价值**:迪勒借此完整看遍了猫王(Elvis Presley)从录制第一首歌曲到登顶乐坛的全部合同与往来记录,以及好莱坞每一位巨星与制片人的真实商业运作。
- **与 Acquired 播客方法的共鸣**:主持人指出,这与制作深度商业播客的逻辑如出一辙——将海量一手原始史料(Primary Research)输入大脑,让人类大脑自然识别并总结出行业背后的底层运作规律。这种无可替代的沉浸式实战学习,是任何商业院校都无法传授的。
### [01:31:52](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5512s) ABC 的创业式狂飙与“周播电影”的发明
从威廉·莫里斯离开后,迪勒加入了美国广播公司(ABC)。在 20 世纪 60 和 70 年代,ABC 是群星闪耀的摇篮,走出了鲁恩·阿利奇(Roone Arledge)和罗伯特·艾格(Bob Iger)等传奇领袖。迪勒解释了当时 ABC 独特的组织氛围:全美三大电视网瓜分了上亿收视观众,但 ABC 成立最晚、排名第三且根基最浅。正因如此,它就像一家“糖果小铺”一样运转,没有任何既定官僚框架;任何人只要敢于承担责任、愿意冒险,就能放手一搏去开拓新事物。
在极其年轻的年纪——迪勒特意纠正并非 23 岁,而是 25 岁半——他便被任命为 ABC 副总裁,成为全美电视网历史上最年轻的副总裁。迪勒掌管了电影部门,并主导开创了改变电视历史的“周播电影”(Movie of the Week)模式:
```mermaid
flowchart TD
accTitle: ABC周播电影模式的演进
accDescr: 展示迪勒在ABC从单独一人发起原创电视电影到年产75部的规模化过程
subgraph Phase1["创新启动"]
A["打破传统:电视台自制原创电影"] --> B["由巴里·迪勒一人独立负责"]
end
subgraph Phase2["规模化扩张"]
B --> C["从最初每年拍摄 25 部"]
C --> D["大获成功并增加播放档期至每周三晚"]
D --> E["年产量迅速扩张至 75 部"]
end
subgraph Phase3["极致成本控制与管理精髓"]
E --> F["单部电影制作预算严格控制在 50 万美元"]
F --> G["亲历基层所有流程,建立对人员和工序的深刻理解"]
end
```
在 ABC 之前,从来没有人为电视专门拍摄过原创故事片,业界普遍认定这一尝试必然惨败,这反而让年轻的迪勒获得了自由创新的试验田。最初部门只有他一名员工,他从零招聘团队、熟悉每一个环节的实际执行,在做中学,不仅提炼出深刻的团队管理哲学,更构建出一套高频、低成本的工业化制作流程。在如今单集 1 小时美剧动辄耗资 1000 万美元的时代背景下,迪勒带领团队当年仅用每部约 50 万美元的成本,便将周播电影从每年 25 部推升到一年 75 部。随着电影和迷你剧(Miniseries)的接连大火,迪勒随后被进一步提拔负责所有常规剧集(Series Programming)。然而这一变动也带来了新的烦恼,因为迪勒打心底厌倦那些千篇一律、剧情停滞不前的半小时情景喜剧和一小时固定单元剧,而这也为他未来跳槽派拉蒙埋下了伏笔。
### [01:35:33](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5733s) 查尔斯·布卢多恩的提拔与派拉蒙的惊人邀请
Barry Diller 回顾了他在 ABC 电视网时期的处境。当时由于要坚守严肃叙事内容,角色的年龄与生活轨迹必须严格符合故事逻辑,稍有不慎整个根基就可能被抽走。就在此时,他的救星跨越地平线而来——庞大工业集团 Gulf and Western 的掌门人查尔斯·布卢多恩(Charles Bluhdorn)。Gulf and Western 当时拥有派拉蒙影业(Paramount),Diller 因为向派拉蒙出售电影版权而结识了布卢多恩。
这家庞然大物的发家史堪称疯狂:起初只是制造汽车保险杠,后来一路扩张到上百种业务,涉足波多黎各制糖业等五花八门的领域,甚至可以说“除了掘墓行业,几乎什么都干”,成为五六十年代企业并购狂潮中规模数一数二的超级集团。布卢多恩当时才三十多岁到四十出头,仅用大约十年就建成了商业帝国。布卢多恩一直想挖 Diller 去派拉蒙,但 Diller 厌恶派拉蒙的管理层,屡次拒绝。直到有一天,布卢多恩把 Diller 叫到办公室,直接下达命令:“我要任命你为派拉蒙的主席。”Diller 震惊地反驳道:“查理,这简直疯了!我是 ABC 电视网的副总裁,派拉蒙是一家电影公司,你不能这么做。”布卢多恩却答道:“哦,我当然可以。”这直接让三十多岁的 Diller 一跃成为好莱坞传奇制片人罗伯特·埃文斯(Robert Evans)的顶头上司。犹豫不决的 Diller 随后去征求 ABC 创始人兼董事长伦纳德·戈登森(Leonard Goldenson)的意见,戈登森听完直接训斥道:“如果你蠢到拒绝这个机会,我现在就把你开除。”
- **Gulf and Western 集团**:从汽车保险杠制造商起家,迅速多元化扩张至制糖、娱乐等上百项产业,并收购派拉蒙。
- **年轻执掌大厂**:Diller 年仅 30 多岁便掌舵好莱坞五大制片厂之一,在当时的好莱坞历史上前所未见。
---
### [01:38:12](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5892s) 前两年的挣扎与《周末夜狂热》的豪赌
执掌派拉蒙的前两年,Diller 过得非常艰难,甚至接近失败,因为他必须摸索出属于自己的运作方式,随时面临卷铺盖走人的危机。直到派拉蒙相继推出了《周末夜狂热》(Saturday Night Fever)以及紧随其后的《油脂》(Grease),局面才彻底扭转。
《周末夜狂热》起用了约翰·特拉沃尔塔(John Travolta),而特拉沃尔塔当时只是情景喜剧《欢迎归来,科特》(Welcome Back, Kotter)里的电视演员。好莱坞电影圈傲慢至极,对电视从业人员向来嗤之以鼻,外界纷纷嘲讽派拉蒙“疯了”,竟然让一个电视喜剧演员来挑大梁演院线大片。在好莱坞著名的格劳曼中国大剧院(Grauman's Chinese Theatre)举行半公开首映礼当晚,离晚上八点开场只剩十五分钟时,全场上座率还不到四成,派拉蒙的老宣传主管甚至走过来对 Diller 泼冷水:“你知道的,你找了特拉沃尔塔,那小子根本没法把观众吸引进影院坐下。”Diller 当时心里一沉,以为一切都完了。然而仅仅十天后正式公映,全美各大影院门口便排起了绕街长龙。好莱坞的势利名流不屑一顾,但普通观众却用脚投票,影片口碑与票房全面爆发。
---
### [01:40:15](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6015s) 影视工业的体系革新:从“组包模式”到“剧本研发池”
在 Diller 的带领下,派拉蒙势如破竹,接连产出《教父2》(The Godfather Part II)、首部《星际迷航》(Star Trek)电影、《夺宝奇兵》(Indiana Jones)等传世名作,一跃成为好莱坞首屈一指的制片巨头。
主持人追问派拉蒙反败为胜的秘诀,Diller 开玩笑说“当然全靠我”,随即严肃解释了核心原因:他们将电视工业的研发逻辑引入了电影界。在此之前,电影行业的典型模式是由经纪人把大牌明星和名导打包后推销给制片厂;而派拉蒙改变了这一规则,转向主动进行大规模的内部项目孵化与深度剧本开发。以《周末夜狂热》为例,灵感仅仅来自《纽约》(New York)杂志上尼克·科恩(Nik Cohn)写的一篇虚构特稿,派拉蒙买下版权后一步步打磨出剧本。派拉蒙随时保持着大约 90 个处于不同开发阶段的项目,通过这种大比例的项目池筛选与精细化运营,彻底颠覆了好莱坞靠运气押注的概率法则。
```mermaid
flowchart LR
accTitle: 好莱坞制片模式转变
accDescr: 对比传统经纪人组包模式与 Diller 引入的电视化项目研发池模式
subgraph OLD["传统电影制片模式"]
A["经纪人打包"] --> B["捆绑大导与明星"] --> C["直接推销给影业投拍"]
end
subgraph NEW["Diller 的派拉蒙模式"]
D["敏锐捕获创意雏形"] --> E["建立 90+ 研发项目池"] --> F["严格比率筛选与打磨"] --> G["持续产出高胜率大片"]
end
```
---
### [01:42:01](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6121s) 投奔福斯与鲁伯特·默多克的“孤注一掷”哲学
在派拉蒙大获成功后,Diller 开始跃跃欲试想要打造第四家全国性电视网,与 CBS、NBC、ABC 三巨头分庭抗礼,但这一计划因当时的经济衰退和母公司收紧资金而搁浅。不久后 Diller 离开派拉蒙加盟二十世纪福斯(20th Century Fox),而鲁伯特·默多克(Rupert Murdoch)在几个月后买入福斯股份,两人自此展开合作。
谈及当今争议缠身的默多克,Diller 抛开政治偏见,盛赞其为商业史上极其罕见的“赌徒型企业家”。默多克从澳大利亚阿德莱德一份不起眼的小镇报纸起家,靠着非凡胆识横扫全澳报业,随后席卷英国乃至全球。与传统管理者不同,默多克极度热衷于“赌上整家公司”(betting the company)去挑战建制派,更重要的是,他对认准的管理层给予绝对的信任与授权。在长达八年的共事中,默多克从未干预过福斯的任何日常运营决策,两人八年间仅仅产生过一次分歧。
当被主持人问及“是否赞同将赌上整家公司作为管理战略”时,Diller 毫不犹豫地回答:“绝不。”台下随即爆发笑声。Diller 直言自己没有那种赌徒心魄,他坚信企业必须勇于承担各种风险去创新,但“拿整家公司作赌注”是绝不可踩的红线——除非你是默多克,或者公司已经被逼入绝境、别无选择。
### [01:46:05](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6365s) 离开大企业母体:独立创业的心理决断与专机困惑
Barry Diller 告诫大家,切忌因为想做新业务,就拿一家运营良好的成熟公司去孤注一掷;如果新业务失败把原本的好业务也一同拖垮下水,那就太愚蠢了。然而,即使深谙此道,Diller 当年在 Rupert Murdoch 的激励下,依然毅然决定脱离受雇体系,成为自担风险的企业创始人。彼时他不仅是 Fox 电影制片厂与电视网的掌舵人,身处好莱坞与名利场的权力顶峰,而且早已赚得盆满钵满、家境殷实。
回顾这次人生转折,Diller 坦言自己在体制内工作了整整 30 年。在企业里打工时,人们往往会产生一种“这家公司属于我”的错觉——虽然身为管理者必须抱有这种主人翁心态,但从法律和产权角度来看,公司终究不属于你。49 岁那年,一个尖锐的念头在他脑海中挥之不去:“我能脱离这种‘母体教会’(mother church)独立生存吗?”对他而言,这成了非黑即白的灵魂拷问:要么你拥有独立创造一番事业的能力,要么你没有。他坦承当时自己生活安逸满足("fat and happy"),原本大可留在 Fox,但内心深处无法忍受自己“其实没有独立能力”这个可能性,正是这种心结将他“生生地逼出了大门”。
为了打破心理舒适区,Diller 经历过一段戏剧性的内心博弈。他打断主持人的提问,分享了一个非常直白的感悟:在离开 Fox 的关口,他问自己,难道仅仅因为不再享有随时待命的私人飞机、必须像普通人一样在机场排队值机,自己就要放弃追求独立吗?“我的自尊难道已经堕落到这种地步,要为了贪恋一架本来就不属于自己的飞机而左右整个人生选择吗?”意识到这一点后,他痛下决心必须勇敢走向外面的世界,彻底告别特权阶层的虚荣。
### [01:49:11](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6551s) 穿越美国的公路旅行与 QVC 的交互式启示
离开 Fox 后,Diller 陷入了迷茫,他明确知道自己不想重复过去、不想再接手第三家电影制片厂,但对未来究竟该做什么毫无头绪。为了开阔眼界,他独自驾车开启了一场穿越美国中部的公路旅行。就在路上,他的妻子 Diane von Furstenberg 给他在车里打来电话,强烈建议他去宾夕法尼亚州的西切斯特(Westchester)看一看电视购物网络 QVC。起初 Diller 满心抗拒,觉得堂堂好莱坞大亨去考察电视购物简直荒谬,但在妻子的极力劝说下还是驱车前往。
踏入 QVC 的演播室后,Diller 见证了让他终生难忘的一幕:电视、电话与计算机在这座相对简陋的演播室里完成了最初步的融合。在一个只有主持桌五倍大的小舞台上,主持人正在展示商品,而旁边的绿色显像管电脑屏幕上,电话进线量的波峰波谷随着商品展示实时上下剧烈起伏。Diller 用“顿悟”(epiphany)来形容当时的震撼:“在那之前,我所理解的屏幕永远只是用来讲故事的,我从来不知道屏幕居然可以用来进行商业交互。”
```mermaid
flowchart LR
accTitle: QVC Primitive Interactivity Flow
accDescr: Diagram showing how TV broadcast, viewer telephone calls, and green screen computer monitoring created real-time interactive commerce.
subgraph Broadcast["演播与展示"]
A["演播室展示商品<br/>(TV Broadcast)"]
end
subgraph Audience["用户端响应"]
B["观众拨打电话订购<br/>(Telephone Calls)"]
end
subgraph Data["实时数据闭环"]
C["绿屏电脑实时曲线监控<br/>(Real-Time Green Screen)"]
end
A --> B
B --> C
C -.实时指导销售节奏.-> A
```
这一划时代的商业模式让 Diller 彻底着迷。仅仅两个月后,机遇巧合降临,他果断出资入股 QVC。在 1993 年,这一举动引来了纽约和好莱坞精英圈的一片嘲弄,人人都以为这位呼风唤雨的娱乐教父“彻底疯了”。然而,Diller 敏锐地抓住了这波浪潮,更重要的是,他在 1995 年互联网全面普及之前整整两年,就通过 QVC 深刻理解了底层连接技术与网络交互的力量,这让他在整个科技革命爆发前夜占据了无可匹敌的信息差优势。
- 主持人 Ben 特别提到,西切斯特恰好是他的家乡,在那个年代那里连一架私人飞机都没有。
- Diller 随后创立的 IAC 集团,在互联网浪潮中收购、分拆并孵化了超过 150 家企业,其中包括 Expedia、TripAdvisor、Angie's List、Vimeo、Ticketmaster、Tinder 以及 Match.com。
- 主持人调侃 Diller 的履历从 William Morris 邮件收发室一路贯穿到硅谷与好莱坞顶峰,宛如“传媒与科技界的阿甘(Forrest Gump)”,Diller 幽默回应自嘲:“我觉得我可能比阿甘还笨一点,但没关系。”
### [01:53:20](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6800s) 科技巨头对影视工业的霸权与给创业者的忠告
针对传统好莱坞制片厂为何能抵抗留声机、VCR、有线电视等近百年的技术冲击,却最终被科技巨头攻破的问题,Diller 做出了极其透彻的商业剖析。在过去七八十年里,好莱坞制片厂之所以屹立不倒,是因为无论面对家庭录像带还是有线网,电影公司都凭借雄厚实力直接把这些分发渠道买下并将其内部化。但互联网时代不同,Netflix 这家纯粹的科技公司横空出世,在影视流媒体领域彻底确立了霸主地位,“如果说今天有一家实体真正掌控了传媒娱乐业,那就是 Netflix,他们已经赢了,没有人能击败他们。”
与此同时,Apple 和 Amazon 等万亿级科技巨头裹挟着远超好莱坞百倍的雄厚资金跨界杀入。传统娱乐业的核心商业逻辑是“不惜代价创造爆款单品”(create hits),然而对于 Amazon Prime 来说,流媒体视频不过是吸引用户订阅 Prime 会员以购买更多烤面包机等日用品的“引流品”(loss leader)。对于 Netflix 而言,虽然内容不是亏本引流工具,但其底层逻辑也变成了维护订阅会员对整体服务的满意度,单个爆款影视剧的重要性被无限稀释。传媒娱乐业的控制权已彻底易手,旧时代的制片厂体制在科技商业模式的降维打击下分崩离析。
在访谈尾声,当主持人请 Diller 给全场数千名创业者留下一句人生建议时,这位纵横传媒商业半个多世纪的传奇人物淡然一笑,给出了一个充满返璞归真色彩的答案:“保持好奇心吧。其实我没有什么大道理可讲,只祝大家一切都好。”随着 Diller 走下舞台,全场爆发出雷鸣般的掌声与欢呼。随后主持人 David 与 Ben 重新登台致谢,感慨在 Radio City Music Hall 举办专场对于这个十年前起步的技术播客而言,是做梦都不曾敢想的巨大里程碑。
### [01:57:10](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=7030s) 闭幕致谢、乐队演奏与谢幕(Closing & Curtain Call)
在无线电城音乐厅(Radio City Music Hall)震撼的掌声中,Acquired 主持人 Ben Gilbert 与 David Rosenthal 开始了全场演出的致谢环节。他们首先向当晚登台的重磅嘉宾们表达了由衷的敬意与谢意,包括摩根大通首席执行官 Jamie Dimon、《纽约时报》首席执行官 Meredith Kopit Levien、资深商业记者 Andrew Ross Sorkin 以及传奇传媒大亨 Barry Diller。此外,他们还向在现场互动和观众席中惊喜亮相的 Acquired 宇宙老朋友们致谢——Vanta 创始人 Christina Cacioppo、Hodinkee 创始人 Ben Clymer、星巴克名誉董事长 Howard Schultz,以及令人惊喜地再次参与观众互动的 Jamie Dimon。
随后,两位主持人向促成这场盛会的所有幕后力量表达了诚挚感谢:包括本次演出的主办合作方摩根大通(J.P. Morgan),为两位主持人提供服装赞助的爱马仕(Hermès),以及摩根大通团队中无数为活动倾注日夜与周末时间的成员。他们特别感谢了现场由数百人组成的制作与执行团队,并邀请团队成员们走上舞台接受观众的掌声。在热烈的谢幕氛围中,现场乐队在领队 Mike Taylor 的带领下奏响激昂的闭幕乐曲,演出在欢呼与音乐声中落下帷幕。
- 登台主嘉宾致谢:Jamie Dimon、Meredith Kopit Levien、Andrew Ross Sorkin、Barry Diller
- 现场客串嘉宾:Christina Cacioppo、Ben Clymer、Howard Schultz
- 合作伙伴与赞助商:摩根大通(J.P. Morgan)、爱马仕(Hermès)
- 音乐总监/乐队领队:Mike Taylor
---
### [01:58:47](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=7127s) 彩蛋片段:后台复盘与经典台词回顾(Post-Credits Sequence)
在舞台灯光暗下、转入演职员名单后的彩蛋片段中,镜头切到了后台,记录了主创团队走下舞台后真实、兴奋而轻松的闲聊时刻。有人惊叹道:“哥们儿,他们真办成了!(Dude, they did it.)” 两位主持人与伙伴们意犹未尽地讨论着今晚各自心中最惊艳的“全场最佳金句”(line of the night)。其中最令人捧腹的当属 Barry Diller 在台上毫不客气、极其霸气地宣称“全都是我的功劳(It was all me)”。
大家还调侃了演出现场接二连三的“剧透”插曲:团队原本精心策划了 Howard Schultz 的惊喜出场环节,结果 Jamie Dimon 在前面的对谈中就直接大大咧咧地当众说道“我觉得 Howard Schultz 就在这儿”,甚至连 Andrew Ross Sorkin 也在台上一语道破,让原定的神秘惊喜荡然无存。走在后台走廊上,大家互致拥抱与祝贺,依然沉浸在难以置信的情绪中:“我不敢相信我们居然真的在无线电城音乐厅演了一场,太超现实了,这世界真是太美好了。”最后,在一句关于“Jamie Dimon 到底会不会去竞选总统?”的玩笑调侃与意味深长的“走着瞧吧(We'll see)”中,全员动身前往庆功派对,整场纪录片圆满落幕。
## Notable quotes
> [00:00](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=0s) 这可是百老汇,这是剧院艺术,大家就是来看一场货真价实的表演 — Ben Gilbert
> [05:36](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=336s) 卷入其中的只是我的净资产(Net Worth),而不是我的自我价值(Self-Worth)。 — 杰米·戴蒙
> [15:05](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=905s) 从现在起,你们可以喝了。 — 杰米·戴蒙
> [27:58](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1678s) 不行,我们现在还很烂(no, we suck),我们还没赢得去经营别人公司的资格。 — 杰米·戴蒙
> [30:43](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=1843s) 在如今的摩根大通内部,没有心照不宣的眼神示意(no winks, no nods),没有任何私下小协议,也几乎没有任何人会单纯因为某单特定业务被单独重赏。 — 杰米·戴蒙
> [35:02](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=2102s) 埃里克,我是来投降的(Eric, I am here to surrender)。我无法对抗联邦政府,我也赢不了联邦政府,这一点你心知肚明。 — 杰米·戴蒙
> [01:16:21](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=4581s) 千万别只谈‘报纸’(Don't talk about the paper)。我们不只是一家报纸公司。 — 梅雷迪思·科皮特·莱维恩
> [01:24:32](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5072s) 我可不这么认为,我觉得是我做嘉宾的那期。 — 霍华德·舒尔茨
> [01:35:33](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=5733s) 如果你蠢到拒绝这个机会,我现在就把你开除。 — 伦纳德·戈登森
> [01:46:05](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6365s) 我的自尊难道已经堕落到这种地步,要为了贪恋一架本来就不属于自己的飞机而左右整个人生选择吗? — 巴里·迪勒
> [01:49:11](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6551s) 在那之前,我所理解的屏幕永远只是用来讲故事的,我从来不知道屏幕居然可以用来进行商业交互。 — 巴里·迪勒
> [01:53:20](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6800s) 如果说今天有一家实体真正掌控了传媒娱乐业,那就是 Netflix,他们已经赢了,没有人能击败他们。 — 巴里·迪勒
> [01:53:20](https://www.youtube.com/watch?v=6sDYv7Ig-6Y&t=6800s) 保持好奇心吧。其实我没有什么大道理可讲,只祝大家一切都好。 — 巴里·迪勒
## Mentioned
Ben Gilbert, David Rosenthal, Mike Taylor, Jamie Dimon, Sandy Weill, John Reed, Jeff Bezos, Hank Greenberg, Ken Langone, Linda Bamman, Andrew Ross Sorkin, Bill Harrison, Alan Schwartz, Eric Holder, Howard Schultz, Judy Dimon, Meredith Kopit Levien, Christina Cacioppo, Ben Clymer, Barry Diller, Diane von Fürstenberg, Darryl Zanuck, Charles Bluhdorn, Leonard Goldenson, John Travolta, Rupert Murdoch, Acquired, 无线电城音乐厅 (Radio City Music Hall), 摩根大通 (JPMorgan Chase), 花旗集团 (Citigroup), 第一银行 (Bank One), 亚马逊 (Amazon), AIG, 家得宝 (Home Depot), 贝尔斯登 (Bear Stearns), 华盛顿互惠银行 (Washington Mutual), 硅谷银行 (Silicon Valley Bank), 第一共和银行 (First Republic Bank), 纽约时报 (The New York Times), DealBook, Squawk Box, Wirecutter, The Athletic, Wordle, 威廉·莫里斯经纪公司 (William Morris Agency), 美国广播公司 (ABC), 派拉蒙影业 (Paramount Pictures), 二十世纪福斯 (20th Century Fox), QVC, IAC, Netflix, ServiceNow, Shopify, 爱马仕 (Hermès)
## Video description
It’s finally here! Today we are releasing Acquired’s first “concert film” — the full video recording of our Radio City live show from this summer with Jamie Dimon, Andrew Ross Sorkin, New York Times CEO Meredith Kopit Levien, Barry Diller, and cameos from around the Acquired Cinematic Universe including Christina Cacioppo, Ben Clymer, and Howard Schultz.
*Sponsors:*
- Live Show Presented By: J.P. Morgan: https://bit.ly/acquiredJPMPs14
- Shopify: https://bit.ly/ShopifyACQ25
- ServiceNow: https://bit.ly/acquiredsn
*More Acquired:*
- Get email updates: https://www.acquired.fm/email and vote on future episodes!
- Join the Slack: http://acquired.fm/slack
- ACQ Merch Store: https://www.acquired.fm/store
0:00 Intro and Welcome
4:50 Jamie Dimon
57:17 Intermission
58:30 Andrew Ross Sorkin
1:00:36 Meredith Kopit Levien
1:20:15 Acquired Wordle
1:22:45 Trivia with the Audience
1:25:20 Barry Diller
1:56:32 Closing, band, and curtain call
1:58:47 Post-Credits Sequence
_Note: Acquired hosts and guests may hold assets discussed in this episode. This podcast is not investment advice, and is intended for informational and entertainment purposes only. You should do your own research and make your own independent decisions when considering any financial transactions._
[Source](https://www.youtube.com/watch?v=6sDYv7Ig-6Y)
Source quotes
[0:00] Ben Gilbert: 这可是百老汇,这是剧院艺术,大家就是来看一场货真价实的表演
[5:36] 杰米·戴蒙: 卷入其中的只是我的净资产(Net Worth),而不是我的自我价值(Self-Worth)。
[15:05] 杰米·戴蒙: 从现在起,你们可以喝了。
[27:58] 杰米·戴蒙: 不行,我们现在还很烂(no, we suck),我们还没赢得去经营别人公司的资格。
[30:43] 杰米·戴蒙: 在如今的摩根大通内部,没有心照不宣的眼神示意(no winks, no nods),没有任何私下小协议,也几乎没有任何人会单纯因为某单特定业务被单独重赏。
[35:02] 杰米·戴蒙: 埃里克,我是来投降的(Eric, I am here to surrender)。我无法对抗联邦政府,我也赢不了联邦政府,这一点你心知肚明。
[76:21] 梅雷迪思·科皮特·莱维恩: 千万别只谈‘报纸’(Don't talk about the paper)。我们不只是一家报纸公司。
[84:32] 霍华德·舒尔茨: 我可不这么认为,我觉得是我做嘉宾的那期。
[95:33] 伦纳德·戈登森: 如果你蠢到拒绝这个机会,我现在就把你开除。
[106:05] 巴里·迪勒: 我的自尊难道已经堕落到这种地步,要为了贪恋一架本来就不属于自己的飞机而左右整个人生选择吗?
[109:11] 巴里·迪勒: 在那之前,我所理解的屏幕永远只是用来讲故事的,我从来不知道屏幕居然可以用来进行商业交互。
[113:20] 巴里·迪勒: 如果说今天有一家实体真正掌控了传媒娱乐业,那就是 Netflix,他们已经赢了,没有人能击败他们。
[113:20] 巴里·迪勒: 保持好奇心吧。其实我没有什么大道理可讲,只祝大家一切都好。
Source quotes
[22:53] Jamie Dimon: Confidence. If you lose money as a financial company, I always knew this too... people lose trust and that causes runs on banks.
[47:58] Jamie Dimon: actual economics... not the accounting of what we do
[47:58] Jamie Dimon: Oh god, we're just giving away too many secrets here.
[53:29] Jamie Dimon: indispensable nation
[53:29] Jamie Dimon: twiddle my thumbs and smell the flowers
[53:29] Jamie Dimon: Right now? Yeah
[61:13] Meredith Kopit Levien: essential subscription for curious people everywhere
[69:06] Meredith Kopit Levien: journalism, particularly journalism about important things going on in the world, is first and foremost a human endeavor
[73:39] Meredith Kopit Levien: it's not a thing
[73:39] Meredith Kopit Levien: pursue the truth wherever it may lead
[85:20] Barry Diller: you are either capable of creating something on your own, or you are not.
[85:20] Barry Diller: They have won. No one is ever going to beat them.
[93:00] Barry Diller: I think I'm a little dumber than Forrest, but that's okay.
[118:47] Barry Diller: it was all me
Original transcript
[0:02] I can't believe the show sold out
[0:04] without us telling anyone what's
[0:06] happening.
[0:06] >> I know, right? [laughter]
[0:09] I hope uh I hope people aren't
[0:11] disappointed.
[0:12] >> Should we have told them at least one
[0:14] guest or like released a detail or
[0:18] I like it. You know, it's Broadway. It's
[0:21] theater. It's uh you're in for a show.
[0:24] >> Come see Acquired as a show. Yep. The
[0:28] suspense, the mystery. Which train are
[0:30] we taking again?
[0:31] >> Uh, I think it's the B.
[0:33] >> B. B. Nice.
[0:34] >> New York really jumps. It does feel like
[0:36] the center of everything.
[0:37] >> You know the famous New Yorker cartoon
[0:39] about [music] how New Yorkers see the
[0:41] geography of America that it's it's the
[0:44] island of Manhattan in the cartoon and
[0:46] then there's the Hudson River and then
[0:47] it's just California on the other side
[0:49] of the Hudson River. There's nothing in
[0:50] between. [laughter]
[0:51] We got a little bit of time before the
[0:53] show. What do you think [music] about a
[0:54] hot dog?
[0:54] >> I get a hot dog.
[0:55] >> All right, let's do it.
[0:58] Thank you. I love it. [music]
[0:59] >> It is my favorite thing to do when I
[1:01] come to New York.
[1:01] >> It's the best.
[1:02] >> Spend some time in Central Park and
[1:03] you're just like walk around all day,
[1:05] pop out, [music] get bagels. I was
[1:07] trying to think what was the first
[1:09] listener live thing we ever did.
[1:11] >> I think it was the Geekwire conference
[1:13] in Seattle. And then we did the Wei Work
[1:16] in San Francisco in the Tender Lions.
[1:17] About 100 people.
[1:18] >> Yep. The PA system went out halfway
[1:20] through.
[1:20] >> Someone ran to Best Buy.
[1:22] >> Yep. Picked up a new PA system. That was
[1:24] amazing.
[1:25] Come a long way.
[1:26] >> Come a long way.
[1:29] >> Should we do it?
[1:30] >> Let's do it.
[1:33] >> New York City, PLEASE PUT YOUR HANDS
[1:35] TOGETHER FOR BIG GILBERT AND DAVID
[1:39] ROSEN.
[1:41] Who got the [music] truth?
[1:44] Is it you? Is it you? Is it you? Who
[1:46] [music] got the truth now?
[1:49] Is it you? Is it? [applause]
[1:55] Hello acquired listeners. [cheering]
[2:01] [applause]
[2:03] >> We are so so excited to have you all
[2:06] here tonight for our live podcast
[2:09] episode recording.
[2:11] So, all right, David, should we do it?
[2:14] Let's do it.
[2:19] Um, I think this was better in theory.
[2:24] I'm not sure. It feels like kind of a
[2:26] waste of all this this stage, this radio
[2:30] city music hall that we have here.
[2:33] >> I think you're right. Should we um
[2:36] should we do the other thing?
[2:37] >> Yeah, maybe we should do the the other
[2:39] thing instead. Let's do that. Hey, Mike.
[2:41] Uh, could you help us level it up a
[2:43] little bit in here?
[2:44] >> I think we can cook something up.
[2:46] >> [applause]
[2:48] >> Radio City. [music]
[2:52] Are you ready? WHO GOT THE TRUTH?
[2:58] Is it you? You [music] who got the
[3:00] truth? Now,
[3:02] is it you? Is it you? Is it you? [music]
[3:04] Set me down. Say it straight. Another
[3:06] story on the way. Who [music] got the
[3:09] truth? Who got the truth?
[3:15] >> [applause]
[3:17] >> Radio City, Mike Taylor, everyone. Woo.
[3:23] [applause]
[3:24] Now,
[3:25] this feels a little more Radio City.
[3:28] >> Yes, it does.
[3:29] >> David Rosenthal, you look sharp.
[3:31] >> Uh, you do too, Ben.
[3:33] >> I suppose we have our friends uh friends
[3:34] at Hermes to thank for helping us
[3:36] celebrate the occasion and show up in
[3:37] style.
[3:38] >> Yes. As always. As always. Indeed.
[3:40] Indeed.
[3:41] >> Well, welcome to Acquired LIVE AT RADIO
[3:43] CITY MUSIC HALL.
[3:47] >> [applause]
[3:48] >> THANK YOU SO much for all of you for
[3:51] coming out and those of you who traveled
[3:53] from far away. We've got people from
[3:55] different states, different continents.
[3:56] Thank you so much. So, what are we
[3:58] really doing tonight?
[3:59] >> Ben and I thought long and hard about
[4:02] what to do tonight. What is the best
[4:04] show we can put on on the greatest stage
[4:07] in the greatest city in the entire world
[4:10] here in New York? Woo! [cheering]
[4:12] [applause]
[4:15] And we realized that what we should do
[4:17] tonight is obvious what Acquired should
[4:19] do. We are going to have three
[4:21] conversations with three of the city's
[4:24] most iconic company CEOs. The way we're
[4:28] going to do it is in two acts. So act
[4:30] one, we've got a big conversation with
[4:32] an important American company that we
[4:35] haven't covered yet here on Acquired
[4:36] that we're going to tell here with the
[4:38] protagonist himself. And in act two
[4:41] after intermission, we are going to have
[4:42] some fun and we're going to try out a
[4:44] new format for Acquired specifically
[4:46] tailored for Radio City Music Hall.
[4:48] >> Yep. So, our first conversation, there
[4:51] is really only one active CEO today here
[4:56] in America who transcends leading his
[4:58] company and really is also looked to as
[5:01] a leader for our country.
[5:03] >> His company is now worth around $800
[5:05] billion. And not only is it the most
[5:08] valuable company in New York, but it's
[5:09] the most valuable company east of the
[5:10] Mississippi.
[5:12] >> So for tonight's big conversation,
[5:14] please welcome the chairman and CEO of
[5:16] JP Morgan Chase,
[5:19] Jamie Diamond, [music]
[5:26] great to have you here. [music]
[5:36] Well, this feels appropriate. [laughter]
[5:39] >> You guys dressed up for me.
[5:42] >> You dressed up for us, too. Thank you.
[5:44] Well, we know you're a big history buff,
[5:46] and we consider ourselves historians
[5:48] above all else. So, uh, what we'd like
[5:51] to do here tonight is walk through the
[5:54] 20-year story with you of sort of how
[5:56] you turned JP Morgan Chase from a bank
[5:59] among many to the most systemically
[6:01] important financial institution in the
[6:02] world. Are you game?
[6:03] >> Sounds great. Thank you. [laughter]
[6:06] >> We want to start in 1998.
[6:10] You and your mentor Sandy While have
[6:12] just spent the past 13 years building
[6:15] the modern financial institution
[6:18] conglomerate. really the the the
[6:19] blueprint for what JP Morgan Chase is
[6:22] today. Except it's not JP Morgan, it's
[6:25] Croup. And everybody on Wall Street in
[6:28] the entire world expects that you are
[6:30] going to be named CEO of Cityroup in
[6:33] short order.
[6:33] >> This is 1998.
[6:35] >> 1998. This is not what happens. Instead,
[6:37] you get fired and you have to restart
[6:40] your whole career, everything, your
[6:43] whole life from scratch. Sorry to start
[6:45] here by the way, [laughter]
[6:47] >> but but before we get into what you do
[6:50] next, what was the model that you and
[6:52] Sandy built at Cityroup?
[6:54] >> Okay, first of all, I am thrilled to be
[6:56] here. I want to congratulate these guys
[6:58] for building the acquired. Uh it's a
[7:01] it's a great intelligent addition to
[7:04] what we need to learn in society. And so
[7:06] I would say it wasn't quite the model
[7:08] because if you look at what we did at
[7:09] commercial credit primarch was then
[7:11] travelers and merged. We were a
[7:13] financial conglomerate. We bought lots
[7:15] of companies and lots of different
[7:16] businesses. We fixed them up. We turned
[7:18] around. We made money. Uh and then we
[7:20] merged it with City Bank which obviously
[7:22] was a huge bank. And uh you know my view
[7:25] is I was we should skinny it down and
[7:26] kind of shed the parts that aren't that
[7:28] important to the rest of the company and
[7:30] keep the things that strategically
[7:32] belong together. It was one of my small
[7:33] disagreements with Sandy about the
[7:35] future of the company. And so um but it
[7:38] was big. It was making a lot of money.
[7:39] It was quite successful at the time and
[7:41] then I got fired.
[7:44] >> So So how are you feeling in that
[7:46] moment?
[7:47] >> When I got fired?
[7:48] >> Yeah, that moment.
[7:49] >> Well, you know, my wife is here and I
[7:51] was hosting a 100 people uh recruiter
[7:55] recruiting kids in my apartment in New
[7:56] York City. Same apartment I have now.
[7:58] And uh they called me. We have a manage
[8:00] meeting a Sunday at 4 pm that night and
[8:02] Sandy and John Reed called me up and
[8:04] said, "Can you come a little early? We
[8:05] got a bunch of stuff to talk about." I
[8:07] was the president, chief operating
[8:09] officer. I drove I said, "I can't." They
[8:11] said, "Well, it's really important." So,
[8:12] I drove up there. Uh, and I sat down in
[8:15] the room with Sandy and John and they
[8:16] said they want to make a few changes and
[8:19] they have three of them. And they said
[8:21] we one one we want to make this person
[8:23] in charge of that. I Okay, well, that
[8:26] didn't make sense to me. The second one
[8:28] they wanted to make someone in charge of
[8:29] the global investment bank which I was
[8:30] running. I thought it was another stupid
[8:33] decision. And the third is they said and
[8:35] we want you to resign. And I said okay
[8:38] because you know at that moment I knew
[8:40] it was all arranged. The boards had
[8:42] voted the press release was written. The
[8:44] management team was coming up. So I
[8:46] waited uh you know for the management
[8:48] team to come up. I wished them the best.
[8:49] I said you guys have a chance to build
[8:50] one of the great companies. They all
[8:52] thanked me. Uh they Sandy said you want
[8:54] to do the press with me? I said, "Yeah,
[8:56] but I'll do it from home." Uh, so I went
[8:58] home, went to see my kids. They were
[9:00] like, one of my daughters here, too.
[9:02] They were like 12, 14, 12, and 10. And I
[9:05] walk in the front door. And, uh, I tell
[9:08] them, you I was fired. And the youngest
[9:10] one says, "Daddy, uh, do we have to
[9:13] sleep on the streets?" I said, "No, no,
[9:15] we're okay." And the middle one, who's
[9:17] always obsessed with college for some
[9:19] reason. Can I still go to college? I
[9:20] said, "Yeah." And the one who was here
[9:22] was the oldest one said, "Great. Since
[9:24] you don't need it, can I have your cell
[9:25] phone? [laughter]
[9:28] And then that night about 50 people came
[9:31] over. All the same people I just met,
[9:33] all the management team bringing whiskey
[9:34] and it was like being your own wake. And
[9:36] there's one really tall guy who came in,
[9:38] very good friend of mine. And he looks
[9:40] and my daughter looks up and says, "Who
[9:42] are you?" He says, "I used I work for
[9:44] your daddy." And he says, "Not anymore
[9:46] you don't." [laughter] And
[9:48] uh that was it. I was okay. You know, I
[9:51] was like I tell people my net worth, not
[9:53] my self worth that was involved.
[9:55] >> And for anyone who doesn't sort of
[9:57] already know Jaime's story, you were the
[9:59] rising star. I mean, you were the city
[10:02] was the biggest bank. You were the era
[10:05] parent. I mean, this is this was like
[10:06] unfathomable. And for you to take it
[10:08] this gracefully, uh, you know, it says a
[10:11] lot. So, you're sort of wandering in the
[10:15] woods as I best I can kind of
[10:17] reconstruct it for about 18 months. Is
[10:18] that right? Figuring out what's next.
[10:20] Yeah, I you know it took me a while to e
[10:22] exit and sign agreements and get out.
[10:25] They were kind of mean. Uh but and then
[10:28] I stepped in office and it was late. I
[10:30] we went for a nice long vacation and
[10:31] stuff like that. Uh when I got back in
[10:34] September, so I was 6 months later I
[10:36] went to my I started going to work. I
[10:37] had nothing to do but I went from you
[10:38] know to 9 to5 and started calling people
[10:40] and thinking about what I'm going to do.
[10:41] It was in the Seagru building so I go
[10:43] for lunch downstairs every day and I
[10:46] >> Four seasons
[10:47] >> at the Four Seasons and I explored
[10:48] everything. Thought my own merchant
[10:50] bank. I could have retired just teaching
[10:53] uh just investing but I was 42
[10:55] >> and you you took a call about running
[10:57] Amazon, didn't you?
[10:58] >> I went to I loved I went to visit Jeff
[11:00] Bezos who was looking for a president at
[11:02] the time. He and I hit it off. We've
[11:04] been friends ever since. He's an
[11:05] exceptional human being. Uh, but it was
[11:07] like a bridge too far. Even though that
[11:09] movie just come out when Sally met
[11:10] Harry, I was thinking, "My god, I'll
[11:12] never wear a suit again. I'm going to
[11:13] live in a house boat.
[11:14] >> This would be really great. Uh,
[11:16] >> what what an alternate universe we'd be
[11:18] living in.
[11:19] >> It would have been an alternate
[11:19] universe." But I'm still good friends
[11:21] with Jeff. So, I got at least one good
[11:22] thing out of it. Uh, and then I would
[11:24] then I got serious, you know, and I was
[11:26] I was offered jobs to run, you know, big
[11:28] other big global investment banks. Uh,
[11:31] Hank Greenberg, who ran AIG, called me
[11:33] up and said, "You should come join us."
[11:34] So I was thinking I'm going to go from
[11:36] Sandy Wild to you. I mean I had to have
[11:37] my head examined to do something like
[11:39] that. [laughter]
[11:41] >> I didn't know the AIG story
[11:43] >> then. Yeah. Well that that happened
[11:44] years later too. And then u I got a
[11:46] phone call from Head Hunter about Bank
[11:48] One. And I was also you guys a lot of
[11:50] you probably know Ken Langon and Bernie
[11:52] Marcus and Arthur the Blank ran Home
[11:53] Depot. My wife I loved them but at my
[11:56] first dinner with them I went to see
[11:58] them in Atlanta. I said I have to make a
[11:59] confession until you guys called. I had
[12:01] never been in a Home Depot and
[12:04] >> we were actually wondering David and I
[12:05] were dating.
[12:06] >> We were talking about a lifelong New
[12:07] Yorker.
[12:08] >> My friend made me go up there and get
[12:09] some equipment and plants and stuff like
[12:12] that. So, but I love their culture,
[12:15] their attitude. They want me to do it.
[12:17] Kentland says he still I still should
[12:19] have gotten you. I wasn't going to pay
[12:20] you enough. Of course, it had nothing to
[12:21] do with anything like that. Uh, and I
[12:23] had Bank One, but bank one was my
[12:26] habitat. I was used to financial
[12:28] companies, you know, services, banking.
[12:30] It wasn't quite global. It was a little
[12:31] global at the time. Uh and you know it
[12:34] was a troubled bank and you know I
[12:36] decided that you know life is what you
[12:37] make it. It was hard in my family. I had
[12:39] a we had to move. I think for anyone
[12:42] who's going to move kids that you know I
[12:43] think there were 14 12.
[12:46] >> Some context on bank one for for folks
[12:48] who are not familiar.
[12:50] >> It's not in New York. It's a large bank
[12:52] but it's a troubled bank.
[12:54] >> It's based in Chicago.
[12:55] >> Large David. It's a it's a $30 billion
[12:58] market cap bank. City Group where you
[12:59] just had been before was a 200
[13:02] >> Yeah.
[13:02] >> billion dollar bank.
[13:03] >> It was 21 billion at the time because it
[13:05] had you have the right numbers but it's
[13:06] did a split and so if you look back it
[13:08] was more like 20 20 billion or something
[13:09] like that. Yeah. And city was 200 but
[13:11] you know I didn't worry about that. I
[13:13] was like you know in life you make
[13:14] things what they are. I don't like
[13:15] complaining about overspilled milk. You
[13:18] know you just put on your pants you get
[13:19] going and see if you can make out of it.
[13:21] And uh
[13:22] >> but you it sounds like you had
[13:23] opportunities to stay in New York to run
[13:26] bigger more glamorous
[13:27] >> things. this when I was going to run the
[13:28] company. The other ones would have been
[13:30] some investment banks. I didn't really
[13:32] trust some of the people who were
[13:33] talking to me about that. And there's a
[13:34] whole bunch of other stuff that I
[13:36] explored. I took phone calls, some small
[13:38] companies, some big companies, there's a
[13:39] couple of subprime mortgage companies
[13:41] who called me and I was like, absolutely
[13:43] not. [laughter] Uh
[13:45] >> we'll get to that. We'll get to that.
[13:46] >> We'll get to that. And uh so I just
[13:48] thought this was a chance, you know, and
[13:50] uh you know, if the family's willing to
[13:52] move and we got a nice took us a while.
[13:54] We had lived in a rental for a while,
[13:55] but we got a nice brownstone. And you
[13:57] know, we end up loving Chicago. Chicago
[13:59] is a wonderful city in a lot of
[14:01] different ways. And and you know, like I
[14:03] said, it is what you make it, you know,
[14:05] and I I I put half my money in the stock
[14:07] at the time.
[14:08] >> Yeah.
[14:08] >> Yeah.
[14:09] >> I tied my I was going to be the captain
[14:11] of the ship. I was going to go down with
[14:12] the ship, you know. I made it clear to
[14:14] everyone I was here permanently and
[14:15] it'll be what it is. And so I got to
[14:18] work like literally the next day. Did
[14:19] >> Did we do the math right that right
[14:21] before you joined Bank One, you bought
[14:23] $60 million of stock?
[14:24] >> I did. I mean, I I that's I've never
[14:27] heard of someone taking a CEO job and
[14:29] saying, "I'm going to invest half my net
[14:31] worth in this company now."
[14:33] >> Yeah. And I thought it was I thought it
[14:35] might be overvalued a little bit because
[14:36] there was people thought it might be
[14:38] sold or something like that, but I
[14:39] didn't care about that. You know, if you
[14:41] work at a company and the new CEO comes
[14:43] in, he's from out of town and you're
[14:45] going to have a lot of shareholders and
[14:47] you know, I knew I knew a lot of the
[14:48] shareholders. I was going to know a lot
[14:49] of the shareholders. I wanted them to
[14:50] know I was in 100%. Lock, stock, and
[14:53] barrel. There was no question. I would
[14:55] never sell that stock and I'm going to
[14:57] go down with the ship or go up with the
[14:58] ship. And they also you I was making
[15:00] decisions that I thought were right for
[15:02] long-term health of the company, not for
[15:04] a short term type of thing.
[15:05] >> So, so what did you find when you got
[15:07] there? Day one of the job you start
[15:09] investigating is it better, worse, the
[15:11] same than you thought.
[15:12] >> You know, there there had been an
[15:14] analyst called Mike Mayo done a report.
[15:16] I remember one of the great lines of the
[15:17] report. Even Hercules couldn't fix it.
[15:19] It had been an amalgamation of Bank One,
[15:21] First Chicago, National Bank of Detroit.
[15:23] They had never put the companies
[15:25] together. So they had multiple statement
[15:27] systems, processing systems, payment
[15:29] systems, you know, SAP systems. Uh they
[15:33] had different brands, you know, services
[15:36] coming down. We were losing accounts.
[15:37] They were closing branches. It was a
[15:39] mess. But, you know, it was all of it.
[15:41] Systems, people, ops. But again, I just,
[15:44] you know, I just I met the management
[15:46] team. I It's hard. You know, I walked
[15:48] in, I met six of the directors. I there
[15:52] were 21 directors 11 hated the other 10.
[15:56] >> Yeah. I mean even wait there were 21
[16:00] board members.
[16:01] >> 21 board members from the mer multiple
[16:03] acquisitions. They they were tribal.
[16:05] They ended up hating each other. I knew
[16:07] that when I went in because I knew one
[16:08] people and you know I spoke to a lot of
[16:10] people did research in the bank. But
[16:12] again in life you get handed these
[16:14] things and it's not perfect. You know
[16:16] even today people want to be handed
[16:18] something perfect. It's not perfect. And
[16:19] I was so I met six of directors. I
[16:21] walked in. When I got off of the job, I
[16:24] shook all their hands. I told them I'm
[16:25] going to do the best I do. I'm tell the
[16:26] truth, the whole truth, none of the
[16:27] truth. The good, the bad, the ugly.
[16:28] We're not going to [ __ ] We're going
[16:29] to try to build a great company. I'm
[16:31] going to need your help. And uh and then
[16:34] they they said they left. [laughter] So
[16:38] now I'm on the executive floor. I don't
[16:40] even know where to go, you know. And so
[16:42] I kind of knocked on someone's door, the
[16:44] head of HR. I said, I do need an office
[16:46] and I really need an assistant. and they
[16:49] were going to give me the chairman's
[16:50] office in the corner. I said, "No, no, I
[16:52] want to be like right in the middle so I
[16:53] can see people." I stick my head out.
[16:55] Uh, and then I went to meet the
[16:57] management team. I went to this, they
[16:59] put them all in this conference room, a
[17:00] nice white plush carpets. I walked in
[17:04] with a cup of coffee and they said, "Uh,
[17:06] Jamie, we don't drink coffee here for
[17:08] obvious reasons." So, I looked at them.
[17:11] I looked at the coffee. I looked at
[17:12] them. I said, "You do now." [laughter]
[17:17] And then I then I just started meeting
[17:18] with them all and the systems were
[17:20] terrible. The company's losing money. I
[17:22] didn't know all the businesses really
[17:23] well. So the credit card company had
[17:25] collapsed. That's probably the business
[17:26] I knew the least. Uh but again, it
[17:28] didn't that didn't matter to me. I was
[17:30] going to try to fix it. It had some good
[17:32] assets and things like that. So I rolled
[17:34] up my sleeves and went to work.
[17:36] one of um as as when we were chatting a
[17:38] couple weeks ago in preparing for this
[17:40] um we asked you in the context of JP
[17:44] Morgan like what what are the critical
[17:46] things in your mind that has made JP
[17:47] Morgan what it is today and the first
[17:48] thing you said was risk and the culture
[17:50] around risk
[17:52] >> fundamentalis understanding by
[17:53] management of risk.
[17:54] >> Yeah.
[17:55] >> When you got to bank one
[17:58] I think this is where you first started
[17:59] putting into practice the culture around
[18:01] risk. What was the risk culture at Bank
[18:03] 1 and how did you change it?
[18:05] >> Yeah, I you know I've always been very
[18:06] risk conscious and risk conscious does
[18:08] not mean getting rid of risk. It means
[18:11] properly pricing it and understanding
[18:13] the potential outcomes. Uh uh and so
[18:16] when I got there, you know, I just
[18:17] started meeting people and going
[18:18] through, I quickly realized that Bank
[18:21] One had more US corporate credit risk
[18:24] than City Bank did. And they the way
[18:28] they accounted for it was unbelievably
[18:30] aggressive and you know so they had less
[18:32] capital, less reserves, less this. They
[18:34] they were calling these things
[18:36] profitable. They were basically losing
[18:37] money. Uh and you know loans in a lot of
[18:40] business you got to be very careful
[18:41] about the credit business. And once I
[18:43] found out that I kind of panicked a
[18:45] little bit and I went through every
[18:46] single loan in the books. I marked them
[18:48] all down, put up more reserves, told the
[18:50] board uh about it and then wanted to
[18:53] earn more revenues per dollar of risk.
[18:56] And I always stress tested and I showed
[18:58] the board that if we have a recession
[18:59] and we're about to have one, uh, how
[19:02] much money we lose in credit? So, I
[19:04] hired a woman called Linda Bamman who
[19:06] said, "Okay, if you're going to if
[19:07] you're going to let me do credit, you
[19:08] going to let me sell loans?" They said,
[19:09] "Yes." "Are you let me hedge loans?"
[19:11] "Yes." "Can I do 10 billion?" I said,
[19:13] "Yes." She said, "Okay, I'll join." And
[19:15] we probably reduced the balance sheet by
[19:17] 50 billion because and then we did have
[19:19] a recession but we were kind of okay by
[19:20] then with one big bad one which is
[19:23] United which went bankrupt and we
[19:24] basically owned it for a small period of
[19:27] time.
[19:27] >> There seems to be kind of a fundamental
[19:29] Jamie Diamondism which is don't blow up.
[19:32] I mean a lot of other people have gotten
[19:34] decent at pricing risk but everyone else
[19:36] seems to be willing to get closer to the
[19:39] line than you. Where did you sort of
[19:41] develop this don't blow up at all costs
[19:44] concept? So there's you know around risk
[19:46] there's always this ecosystem you've
[19:47] always heard it everyone's doing it
[19:49] everyone's okay this is going to work
[19:51] this time is different and you know the
[19:53] history tells you learn teaches you a
[19:55] lot and I always say you treat his my
[19:57] dad was a stock broker and so I bought
[19:59] my first stock when I was 14 in 1972 the
[20:03] stock market hit a thousand it hit a
[20:05] thousand in 1968 I was already helping a
[20:08] little bit with stuff
[20:10] by 1974 was down 45%
[20:14] All the limousines in Wall Street were
[20:16] gone. Restaurants were being closed. You
[20:19] know, markets move violently. And then,
[20:22] you know, we had kind of a recovery in
[20:23] 1980. Had a recession. 82. You had a
[20:26] recession. In ' 82, it was lower than it
[20:27] had been in 1968. And it hit 800. And
[20:31] then in ' 87, the market was down 25% in
[20:34] one day. In 1990, all these banks, JP
[20:37] Morgan, City, Chase, Chemical, were all
[20:39] taken to their knees by real estate
[20:41] losses. And they were all worth about a
[20:42] billion dollars. I met I think city was
[20:45] three billion at the time and the other
[20:46] ones were about a billion dollars. And
[20:48] then you had the 97
[20:50] also real estate related thing. You had
[20:52] the 2000 internet bubble, you know, and
[20:55] then you had the great financial crisis.
[20:57] And I could if you go through history,
[20:58] there's tons of these things. Andrew War
[21:00] Soren is in here and I just read his
[21:02] book. He's nice enough to send it to me
[21:04] in 1929. And man, history does rhyme.
[21:08] Too much leverage, too much risk.
[21:10] Everyone thinks it's going to be great.
[21:11] No one thinks it can go down a lot. You
[21:13] know, that stock market went down 20%
[21:15] one year, 30% next year, 20% the next
[21:17] year. At one point, it was down 90%. You
[21:20] know, [ __ ] happens.
[21:21] >> It seems like your philosophy is that
[21:24] the most the worst thing will happen.
[21:26] So, just plan for it. Don't don't say,
[21:28] "Oh, we're good as long as this crazy
[21:31] insane, you know, four sigma event
[21:33] doesn't happen." You're like, "No, that
[21:34] will happen. It happens often."
[21:36] >> Yeah. So when I got when I look at it I
[21:38] always ask like when I do stress testing
[21:40] of risk for high yield the worst I
[21:42] remember getting a JP Morgan and going
[21:44] through the risk books and there their
[21:47] stress test was that high yield would
[21:49] move 40% the credit spread that's and at
[21:52] the time was it 400 or whatever it was
[21:54] that means five 560 okay and I said no
[21:58] our stress test is going to be worst
[21:59] ever worst ever was 17%. and they said
[22:03] that'll never happen again. The market's
[22:04] more sophisticated. Well, in ' 08, it
[22:06] hit 20%. And you couldn't have sold a
[22:09] bond. There was no market. So, you know,
[22:11] those things do happen. And the point
[22:13] isn't that you're trying to guess them.
[22:14] The point is you you can handle them.
[22:17] So, you continue build your business.
[22:19] And so, I always look what I call the
[22:20] fat tails and manage that we can handle
[22:22] all the all the fat tails. And not the
[22:25] stress test the Fed gives us, but all
[22:26] the fat tails. Market's down 50%,
[22:28] interest rates up to 8%, credit spreads
[22:30] back to worst ever. Of course, your
[22:32] results will be worse, but you're there.
[22:34] And and the thing about financial
[22:36] services, leverage kills you. Aggressive
[22:39] accounting can kill you, which a lot of
[22:40] companies do do. Um, and you know, the
[22:43] goal should be and also confidence. If
[22:46] you lose money as a financial company, I
[22:47] always knew this too. People the
[22:49] headlines are, you know, people read
[22:51] that and if they're aligned on putting
[22:53] their money with you, they look at that
[22:54] different. So, I
[22:55] >> they lose trust. they lose trust and
[22:57] that which caused you've seen runs on
[22:58] banks and you've saw some recently uh
[23:01] because people run take their money out.
[23:03] >> The one there's a thing that you just
[23:05] said which is that you might do worse
[23:09] but you're there there's sort of this
[23:10] trade-off that you make where you're
[23:12] less profitable in the short term but at
[23:13] least you stick around. If you look back
[23:16] at the companies that you've run,
[23:19] beguan, JP Morgan, Chase, is that true
[23:21] in the good years that you've actually
[23:22] been less profitable than those who are
[23:24] kind of riskone.
[23:26] >> Yeah, a little bit. He's saying that,
[23:27] you know, if you look at the history of
[23:28] banks from up until 2007, a lot of banks
[23:32] were earning 30% equity. Most of them
[23:34] went bankrupt. We never did that much.
[23:37] Okay? But in ' 08 and 09, we were fine
[23:40] and they weren't. And so uh but you want
[23:42] to build a real strong company with real
[23:45] margins, real clients, conservative
[23:47] accounting where you're not relying on
[23:49] leverage. And it's very easy to use
[23:50] leverage to, you know, to jack up
[23:52] returns in any business, you know, and
[23:54] but in in banking, it could be
[23:56] particularly dangerous.
[23:57] >> So it seems like a core
[24:00] part, if not the entirety of this
[24:03] distilled into your operating strategy,
[24:06] is the Fortress balance sheet.
[24:08] When did you first hear about the
[24:10] forestress balance sheet?
[24:12] >> I've been talking I go way back to prim.
[24:14] I used to talk about that you got to be
[24:16] able to survive the tough times early
[24:17] >> 90s probably the 1990s and like I said I
[24:21] grew up my father and I went through
[24:22] those market things and I remember how
[24:25] hard it was on people on Wall Street. Uh
[24:27] but but the fortress balance sheet is
[24:29] that you run a company serving clients
[24:31] well. You have good margins, good
[24:34] liquidity, good capital. I'm as
[24:36] conservative an accountant as you can
[24:37] find. I don't upfront profits when I can
[24:40] spread them over time. And accounting,
[24:41] you know, of course accountants hate it
[24:42] when I say this. You can drive a truck
[24:44] through accounting rules. And accounting
[24:46] itself, you know that certain things are
[24:49] considered expenses, but they're good.
[24:50] They're an investment for the future,
[24:51] but they're called an expense. And then
[24:53] revenues, you know, if I make bad loans,
[24:55] they are bad revenues. They will kill
[24:57] you, but for a while, they look pretty
[24:59] good. So, I it's all those things.
[25:01] margins, clients, you know, in the
[25:02] banking business, the character of the
[25:04] clients you have will reflect in your
[25:06] bank. So, the first thing is who are you
[25:07] doing business with? How you doing
[25:09] business? And uh you know, also making
[25:11] sure your compensation plans aren't
[25:13] paying people for stuff which is stupid
[25:16] or unethical. And you know, uh and you
[25:18] always have to review these things to
[25:19] make sure you have them right because
[25:20] they they change all the time.
[25:22] >> All right, David, catch catch us up to
[25:24] the merger. So you run bank one for four
[25:26] years from Chicago and then in 2004 you
[25:31] merge with JP Morgan Chase in what is
[25:35] termed at the time a merger of equals I
[25:38] think JP Morgan Chase referred to it as
[25:39] that bank one shareholders get 42%
[25:43] of the combined company. I mean I think
[25:45] people don't realize how much of JP
[25:46] Morgan Chase is bank one today. That's
[25:49] why it's a little irritating me when
[25:50] they say you've been running it since I
[25:51] was I was running JP Morgan. I was
[25:52] running 40% of the company for the whole
[25:54] time. [laughter] And uh when I got to
[25:58] Bank One and I'm not working around the
[26:00] clock, I I already knew that a logical
[26:02] strategic merger might be JP Morgan.
[26:05] Okay, I know all these companies and
[26:06] that's the other thing about Fortress
[26:07] balance sheet is you also have real
[26:09] strategies that survive the test of time
[26:11] and you know you're not flipping and
[26:13] flopping. Um, [clears throat] and then
[26:15] I'm sitting there and of course the tape
[26:16] comes JP Morgan Chase to merge. So we're
[26:19] worth like 25 billion. They're now worth
[26:21] like 80 billion or 90 or whatever the
[26:23] number was. I'm like, well, there goes
[26:25] that dream. But four years later, our
[26:27] stock was up to, you know, doubled or
[26:30] something like that. There's actually
[26:31] come in and it was in the target range
[26:34] and I'd been meeting with Bill Harrison,
[26:36] the current chairman of of JP Morgan at
[26:38] the time. We were talking about it. We
[26:41] both knew it made business sense. They
[26:43] were kind of looking for a CEO. Uh so we
[26:45] were we had been talking probably for a
[26:47] year and a half before that
[26:48] >> that they're looking for a CEO. Did they
[26:50] give Bank One shareholders 42% because
[26:53] they were looking for a CEO? So we got
[26:55] the premium, they got the name and the
[26:58] location and I I effectively had kind of
[27:01] control from day one because inside the
[27:03] merge agreement and this is almost
[27:05] unheard of when we get the premium is
[27:07] that to not have me become CEO 18 months
[27:11] later 75% of the board would have to
[27:13] vote me out and the board
[27:15] >> the default was you were going to become
[27:17] >> and the board was eight bank one people
[27:19] and eight JP Morgan people but that was
[27:21] the agreement they got sued for paying
[27:24] too much to buy me. I got sued for not
[27:28] taking enough. [laughter]
[27:30] You get sued, you can't win these.
[27:32] >> I think every shareholder is probably
[27:34] >> But it worked. It worked out.
[27:36] >> Yeah. When you were going through that
[27:38] process and even maybe the couple years
[27:40] before you and Bill were talking, you're
[27:41] starting to think about JP Morgan as a
[27:43] partner. I'm curious, did the brand, did
[27:46] the name JP Morgan factor into your
[27:49] thinking at all? Did you view that
[27:51] >> as an asset? I mean JP Morgan brand is a
[27:53] Tiffany name. I didn't value it in the
[27:56] deal. And what we what I looked at I had
[27:58] given my board I think it's I think the
[28:00] first thing is run your company well and
[28:02] people thought I was going to start
[28:03] doing deals immediately. I was like no
[28:05] we suck. We don't we haven't earned the
[28:06] right to run someone else's company yet.
[28:08] When we're running a good company we can
[28:10] merge with somebody. And but I but the
[28:13] first thing I looked at was business
[28:14] logic and that every business we had a
[28:17] consumer business. They had a consumer
[28:18] business. We had a credit card business.
[28:19] They were both terrible. They had a
[28:21] credit card business. They had a big
[28:22] investment bank. We had a big US
[28:24] corporate bank that needed some of those
[28:26] investment banking service. We both had
[28:28] a wealth management business. I was I
[28:30] knew we could save a lot of cost saves.
[28:32] So the business logic would be
[28:33] impeccable. Then there's the ability to
[28:35] execute like can you actually get it
[28:37] done because you've all seen a lot of
[28:39] deals where they fall apart. They don't
[28:41] have management. They don't consolidate
[28:42] the systems. They have infighting. It
[28:45] kind of happened at city. Uh and so you
[28:47] don't effectuate. And then there's the
[28:49] price. So, I knew we had a Tiffany
[28:51] brand. Uh, but it it didn't value
[28:53] because if everything else didn't work
[28:54] out, I don't think it would have
[28:55] mattered that much.
[28:56] >> Interesting. [clears throat] Okay. So,
[28:58] so
[28:58] >> I'm going to fast forward a couple
[29:00] years. It's 2006. You're officially
[29:02] chairman and CEO of the combined JP
[29:05] Morgan Chase.
[29:05] >> And 2006 on Wall Street is like
[29:08] >> go go go baby. It's like, you know,
[29:10] 1980s all over again.
[29:12] >> I think you had the same incentives as
[29:15] everyone else, but you behaved very
[29:17] differently. Am I missing something? Did
[29:20] you have the same incentives or
[29:21] >> you pulled JP Morgan back hard on the
[29:24] risk side in 2006?
[29:25] >> I did. So there there were cracks out
[29:28] there in 2006. May remember the quants.
[29:30] There started to be a quant problem and
[29:32] late in 2006. We definitely saw subprime
[29:35] getting bad and that's I pulled back on
[29:37] subprime. I I wish I had done more
[29:39] because if you look what I did, you say,
[29:40] "Okay, well you saved half the money,
[29:42] but you would have saved more."
[29:44] >> You still had some losses.
[29:45] >> Yeah. But but we also had I'm going to
[29:48] say less maybe a third of the leverage
[29:51] of the big investment banks
[29:54] and a lot more liquidity. So in 2006 I
[29:57] started to stockpile liquidity and you
[29:59] know looking at the situation I was
[30:01] quite worried the leverage if you you
[30:03] may not remember this but the leverage
[30:06] because of accounting rules and Basel 3
[30:08] Basel one investment banks particularly
[30:10] the banks the big investment banks went
[30:12] from 12 times leverage to 35 times
[30:15] leverage
[30:16] and and it was go- go you know CMOs you
[30:20] know bridge loans the whole thing like
[30:22] in ' 07 the bridgebook of Wall Street
[30:25] was 400 $50 billion. Today it's 40
[30:28] billion. JP Warren can handle the whole
[30:30] 40 billion today, though we're not the
[30:32] 40 billion today. Uh and they were much
[30:34] more leveraged deals and a lot of them
[30:36] fell apart, collapsed and and then of
[30:38] course and that was before you had the
[30:40] collapse in the mortgage markets which
[30:41] really took down a lot of these banks.
[30:43] >> But but you did have the same incentives
[30:46] and you had the same access to
[30:49] information that a lot of these other
[30:50] folks did, but you didn't blow up. What
[30:53] explains this? Because usually behavior
[30:55] follows incentives.
[30:57] >> Yeah. Well, first of all, if you work
[30:58] for me, I would tell you I don't care
[31:00] what the incentive is. Don't do the
[31:02] wrong thing. And and don't do the wrong
[31:04] thing to the client. If you treat
[31:06] yourself, if you're the client, how
[31:07] would you want to be treated? And I I
[31:09] had gotten rid of I mentioned that one
[31:11] risk thing. There were multiple risk
[31:12] things like that. They were being paid
[31:13] to take the risk. All of these
[31:15] investment banks were doing side deals,
[31:17] private deals, three-year deals, five
[31:18] year deals. I got rid of almost all of
[31:20] them.
[31:20] >> This is for comp senior bankers. And so
[31:23] today at JP Morgan Chase, there are no,
[31:25] you know, we do do things, but and I
[31:27] know some of my partners in the room
[31:28] here, but we all know about it. There
[31:30] are no winks, there are no nods, there
[31:32] no side deals, there's almost no one
[31:34] paid on a particular thing because if
[31:37] you're paid on a particular thing, you
[31:38] can do the wrong thing and meanwhile not
[31:40] helping the company, you know, manage it
[31:42] risk or something like that. So we
[31:44] change the incentive programs and I'm
[31:46] quite conscious about incentive programs
[31:47] that they don't create mis, you know,
[31:49] misbehavior. But it's also very
[31:51] important. If you're in a company and
[31:53] you say the incentive program is doing
[31:54] that, you should tell the company this
[31:56] incentive plan is not incenting the
[31:58] right behavior versus via the the
[32:00] customer. And a lot of it was leverage.
[32:02] So you if you look at the leverage in
[32:03] some of these securization books and
[32:05] mortgage books, if you have 30 times
[32:08] leverage and you're getting 20% of the
[32:10] profits, you'll go to 40 times leverage.
[32:13] It's just going to it's literally will
[32:14] add, you know, 25% to your bonus. And so
[32:17] I got rid of the profit pool 20% and the
[32:20] leverage
[32:20] >> and I lost some people too in the
[32:22] meantime.
[32:22] >> It's funny. Yeah. You know JP Morgan as
[32:25] part of the system had the same
[32:26] incentives but you changed the
[32:27] incentives for
[32:28] >> team within the company. Okay. All
[32:30] right. We got to go to 2008.
[32:33] >> March
[32:33] >> March 13th
[32:35] >> 2008.
[32:36] >> Thursday 2008.
[32:37] >> Yeah.
[32:38] >> It's Thursday night. You get a call from
[32:40] Bear Stern's CEO. The stock closed that
[32:44] day at $57 a share. It's like 150 a
[32:47] couple months before. Three days later.
[32:51] God, I remember it like yesterday. I was
[32:52] working on Park Avenue in Wall Street. I
[32:54] remember that night. $2 a share. You're
[32:57] buying Ver. And to tell us the story.
[32:59] >> So, I was at AVA on 47th Street. My
[33:02] parents and my parents favorite
[33:03] restaurant. My whole family was there.
[33:04] It happened to be my birthday. Uh I I
[33:07] don't normally get emergency.
[33:09] >> Happy birthday.
[33:10] >> Yeah. And Allan Schwarz, who was the
[33:12] current CEO, we'd seen their stock go
[33:14] down. I knew they had some real problems
[33:16] because we saw their hedge funds and
[33:18] some of the things that were taking
[33:19] place there. And he said, "Jamie, I need
[33:21] $30 billion tonight before Asia opens."
[33:25] Which I said, "I don't know how to get
[33:26] $30 billion for you." And have you
[33:29] called Pollson? Have you called Tim
[33:31] Gener? Uh, so we all called. I called up
[33:33] the management team. I went back in. I
[33:35] probably had a bite and said goodbye and
[33:37] went back to the office. probably had a
[33:39] hundred people come in that day, that
[33:41] night. They all got dressed. They went
[33:42] back to work. It's emergency. We now
[33:44] rang all bells for emergency. Bear
[33:46] Sterns went bankrupt. Spoke to the Fed
[33:48] about let's just get them to the
[33:50] weekend. We had one day and we needed a
[33:52] Saturday and Sunday and we concocted
[33:55] this loan. So, we couldn't lend the 30
[33:57] billion and the Fed technically couldn't
[33:59] lend the 30 billion, but the Fed can
[34:01] lend to us technically and I can
[34:03] technically use the collateral of beer.
[34:05] So that uh so we got the literally a
[34:07] one-day loan uh and then the next day I
[34:10] had we had thousands of people come in
[34:11] due diligence and we went through every
[34:13] loan, every asset, every balance sheet,
[34:15] all the derivatives, all the lawsuits,
[34:17] all the HR policies, like real due
[34:19] diligence, a two or three day period and
[34:21] bought the company at that night $2 a
[34:24] share. Hank Pollson was telling why are
[34:26] you paying anything for it? I said well
[34:27] I do have to get shareholder votes and
[34:30] uh which became
[34:30] >> because you need bare shareholders to
[34:32] approve. It was a public deal and the
[34:34] worst part of it is I was going to get
[34:35] the lawsuits from the bear holders
[34:37] >> and I knew that
[34:38] >> that you didn't pay enough for
[34:39] >> but but we couldn't let it go bankrupt.
[34:40] It wasn't like an industrial company I
[34:41] could buy in bankruptcy. It would have
[34:43] been gone and the crisis would have just
[34:45] unfolded. So we paid we paid a billion
[34:47] dollars for a company that had been
[34:48] worth uh $20 billion recently. The
[34:51] building we're in now was worth a
[34:53] billion dollars on the balance sheet for
[34:55] zero. And we got the fact we got some
[34:57] very good people and we got some good
[34:59] businesses but it was a extremely
[35:01] painful process. I
[35:02] >> I've seen estimates that in the fullness
[35:04] of time after really dealing with
[35:07] unwinding all the stuff there it cost
[35:09] you 15 to 20 billion you anyway.
[35:13] >> It was the it was the 12 billion we
[35:14] wrote off that didn't cost us. We didn't
[35:16] really pay for it. And then the
[35:17] government sued us on the mortgages
[35:19] which I was quite offended by. Uh,
[35:22] [laughter]
[35:22] and I really was I thought it was
[35:24] >> take this problem and then we'll see.
[35:25] >> This is this is the government when you
[35:28] you know the the whatever government you
[35:30] did a deal with that's not the
[35:31] government down the road decides I don't
[35:33] care. We're going to come after you
[35:35] anyway. So while we kind of saved the
[35:36] system a lot, we bailed a lot of people
[35:38] out. They made us pay $5 billion on the
[35:41] the bad mortgages that bearish tons
[35:43] done. And that's what made me make the
[35:45] statement I wouldn't do it again. I
[35:46] wouldn't put it this way and I don't
[35:48] know how to say this. I wouldn't really
[35:49] trust the government again. Okay.
[35:52] [laughter]
[35:57] >> Would um I got to I got to ask a
[36:00] follow-up question to that. Um
[36:02] [laughter]
[36:03] it is that a
[36:06] structural thing just the way that we're
[36:09] set up with a new administration every
[36:11] four years.
[36:12] >> Yeah. They they don't feel obligated to
[36:14] what the prior administration did. and
[36:17] you know contract even some contracts
[36:19] were violated in this thing which I
[36:21] won't go through uh literally contract I
[36:23] mean it would have been torturous
[36:24] interference that had been company to
[36:26] company but they basically you know
[36:28] since you operate under their laws you
[36:31] know they can basically take you down so
[36:33] you you know I I went to see Eric Holder
[36:36] trying to settle this mortgage stuff
[36:37] which we settled I brought my lead
[36:38] director he expected me to come and be
[36:40] pounding my chest and uh and I went in
[36:43] and said Eric I am here to surrender
[36:47] I cannot fight and I cannot win against
[36:49] the federal government. You know that a
[36:51] criminal indictment can sink my company.
[36:53] I will not do that to my company or my
[36:55] country. I'm here to surrender. Before I
[36:59] surrender, I want you to know the
[37:00] circumstances by which we bought Wamu
[37:02] and Bear Sterns because 80% of what
[37:04] they're asking for related to be and
[37:06] WAMU, not JP Morgan Chase. And I went
[37:09] through the whole thing, you know, uh he
[37:11] said, "Thank you. uh I'll take in
[37:14] consideration but they never gave me the
[37:15] counting so I don't know what they did
[37:17] uh and so it is what it is it was quite
[37:20] painful uh but got to move on
[37:23] >> we'll move on from this we won't keep
[37:24] you
[37:25] >> well we'll move on for the specifics
[37:27] [laughter]
[37:28] David's
[37:29] >> we do I do have one more thing um
[37:31] whether you would have done it again
[37:33] wouldn't have you know very clear it was
[37:36] not a great deal on paper for JP Morgan
[37:40] but as we look at it Now, the
[37:43] reputational value that JP the
[37:46] reputation of JP Morgan now is unlike
[37:48] any other in the industry.
[37:50] >> Part of why you're worth $800 billion is
[37:52] that reputation. A lot of what created
[37:54] that reputation
[37:55] >> was was that weekend.
[37:57] >> Yeah. I you know, if you're Yes. And I
[37:59] know I say I wouldn't trust the
[38:00] government. If the government called me
[38:01] up, they did they did it again. If they
[38:03] called me again and said, "We need your
[38:04] help to save our country." Well, of
[38:05] course, I'm going to I'm a patriot that
[38:07] way. I just I would just try to come up
[38:10] with some ways to avoid the punishment
[38:12] by the next president. [laughter]
[38:14] >> I would come up with something like
[38:16] >> you need you know what you need like uh
[38:18] the version of the merger agreement with
[38:19] JP Morgan Chase where it's like a 75% of
[38:21] Congress needs to [laughter] vote not to
[38:23] sue you. Like the default is you're not
[38:26] going to get sued.
[38:27] >> All right.
[38:28] >> All right. So Bear Sterns happens 6
[38:31] months later you get another phone call.
[38:33] Wamu is going under. You do buy Wamu.
[38:36] Contrary to everything we're talking
[38:37] about with Bearer, Wamu is actually a
[38:40] great acquisition, right?
[38:42] >> Yeah. So, this is a lesson about
[38:43] acquisitions. It's very hard that
[38:45] remember we bought WAMU a week after
[38:47] Leman went bankrupt and and most boards
[38:51] wouldn't have touched that at all
[38:52] >> because the whole system feels like
[38:54] >> the whole system was in trouble. But
[38:56] WAMU put us in California, uh, uh, parts
[38:59] of Nevada, Arizona, not Arizona,
[39:02] Georgia, Florida, which we weren't in.
[39:04] So, think of these really healthy states
[39:07] and they had, you know, 2,300 branches.
[39:09] They were and they h they had huge
[39:11] mortgage problems, but we had looked at
[39:13] it over and over and over. So, we knew
[39:17] their mortgage books called and we wrote
[39:19] off we bought it for
[39:21] >> this was all before.
[39:22] >> We bought it for a $30 billion discount
[39:24] to tangible book value
[39:26] because they had debt and we left the
[39:28] debt behind. And so, and that 30 billion
[39:31] was approximately what the Morris loss
[39:33] was going to be. So, we bought the
[39:34] company. Think if we bought a company
[39:36] clean, we wrote off all that stuff. The
[39:38] books were clean. And then we did
[39:40] something unheard of, too. The next day
[39:42] or two days later, I went in the market,
[39:43] raised another 11 billion of equity.
[39:45] >> Yeah.
[39:45] >> Which I didn't really need. But again,
[39:48] this is my conservatism. Uh I was like,
[39:50] you know what, this can get even worse.
[39:53] And and I don't want to be short capital
[39:55] liquidity. So we, you know, we raised
[39:57] that to make sure our balance sheet was
[39:58] just as strong as it was after WAMU that
[40:00] it was before WAMU.
[40:02] >> And you already had the reputation to
[40:03] pull this off, right? I I'm imagining in
[40:06] the worst month of the financial crisis,
[40:09] who can go out and raise 11 billion of
[40:10] equity.
[40:11] >> Yeah,
[40:12] >> people trust you.
[40:13] >> Well, yeah, we knew a lot of the
[40:14] shareholders and you earn your trust
[40:16] over time with shareholders and, you
[40:18] know, we explained we we gave them a
[40:19] quick little presentation over, you
[40:21] know, uh uh yeah, and a lot of them
[40:23] stepped up and said, "This is great." We
[40:25] also know we can execute it because
[40:26] behind the bear sterns people forget the
[40:28] work is the next day you got 50,000
[40:30] people consolidating you know 5,000
[40:33] applications branches compensation
[40:36] programs uh you know settlement programs
[40:39] you know payment systems it's a lot of
[40:41] work but we obviously have the
[40:43] capability to do that and we have the
[40:44] capability to do wamu I think we
[40:46] finished the wamu consolidations in nine
[40:48] months all of them so that within nine
[40:50] months they were all in the same systems
[40:52] which allows you to start doing a better
[40:53] job in customer service uh and things
[40:55] like that. So this fortress balance
[40:57] sheet strategy and raising this equity
[41:00] capital and you know having additional
[41:01] margin of safety and conservative
[41:03] accounting in retrospect it seems like
[41:05] the obvious right strategy for running a
[41:08] large financial institution. Why wasn't
[41:11] everyone else copying it? H have people
[41:13] changed and does everyone else run their
[41:15] banks like this now? I think people the
[41:18] people are more conservative today. I
[41:19] think regulars are more conservative
[41:20] today. But again, I go back to people
[41:23] get involved in aggressive accounting.
[41:25] Uh they don't look at stressing their
[41:27] own bank in a real way. Uh you know, you
[41:31] saw people take too much interest rate
[41:33] risk, too much credit exposure, too much
[41:34] optionality risk and and or or sometimes
[41:37] it's new products. So if you look at the
[41:39] financial services, very often it's the
[41:41] new products that blow up. It takes a
[41:43] while. They haven't been through a
[41:44] cycle. And you you had that with
[41:46] equities way back in 1929. You had it
[41:48] with options. You had it with equity
[41:51] derivatives. You had it with mortgages.
[41:53] You had it with G. Even Ginnie Mays at
[41:54] one point blew up even though they're
[41:56] government guaranteed.
[41:57] >> Arguably, you had it with quant and with
[41:59] LT.
[42:00] >> It happened with Quant. It happened with
[42:01] leverage lending. And then people then
[42:03] become more rational how they run these
[42:04] balance sheets, how they think through
[42:06] the risk.
[42:06] >> So So I have to ask you, is this private
[42:08] credit today?
[42:09] >> I I don't really think so. I I don't
[42:11] think it's $2 trillion. It's grown
[42:13] rapidly. That's an issue. But what
[42:16] happens the other thing about Mark is
[42:18] there's some very good actors in it who
[42:20] know what they're doing. Customers like
[42:22] the product. So I always say, well, the
[42:23] customers like it and but there also
[42:25] people who don't know what they're doing
[42:26] and it's grown rapidly. So there it may
[42:29] there may be something in there would
[42:30] become a problem one day. I don't think
[42:32] it's systemic. So that two trillion the
[42:34] mortgage market when the time it blew up
[42:36] was I'm going to say n trillion and a
[42:39] trillion dollars was lost. This is you
[42:41] know and it was trillion dollars was
[42:43] also in high trillion dollar back then.
[42:45] >> Yeah. A lot of these private a lot of
[42:46] these private credits are not leveraged
[42:48] like that but doesn't mean there won't
[42:49] be problems but it's it's slightly
[42:51] different but we you got but you look at
[42:52] the whole system there are other things
[42:54] out there that you know are leveraged
[42:56] that you know can cause problems and of
[42:58] course people take secret leverage in
[42:59] ways you don't necessarily see it. What
[43:01] what are some of these in your mind that
[43:03] are potentially problematic today?
[43:05] >> Well, I look I I look at when you look
[43:08] at asset price a rather high. Now, I'm
[43:10] not saying that's bad, but if we if if
[43:13] today pees were 15 as opposed to 23. I
[43:17] say that's a lot less risk, a lot less
[43:19] to fall and you have some upside. I
[43:22] would say at 23 there's not a lot of
[43:24] upside and there's a long way to fall.
[43:25] And that's true with credit spread. So,
[43:27] and we look at we stress test
[43:29] everything. We do like a 100 stress
[43:31] tests a week, you know, and to make sure
[43:33] we can handle a wide variety of things.
[43:35] And then the other thing and the biggest
[43:37] risk to me is cyber. I mean, I I think
[43:39] this cyber stuff is, you know, we we're
[43:42] very good at it. We work with all the
[43:43] government agencies. They would say that
[43:45] Jmore, we spend $800 million a year or
[43:48] something on it. We educate people on
[43:49] it. We just do. But it is you're talking
[43:52] about grids and communications companies
[43:54] and water uh uh and even part of the
[43:57] military establishment. The the
[43:59] protections are not what you need if we
[44:01] ever get any kind of war where cyber is
[44:03] involved and China is very good at it
[44:06] and so is Russia but Russia is mostly
[44:08] criminal which is slightly different.
[44:11] >> All right, I'm going to pull us back to
[44:12] the story. We're going to fast forward
[44:14] to 2023.
[44:15] >> We're not really equipped to talk about
[44:17] Yeah. Russia.
[44:18] Uh,
[44:19] >> it's not what we do at acquired, but but
[44:21] they um
[44:21] >> Silicon Valley Bank.
[44:23] >> Yeah.
[44:24] >> And First Republic both fail. You're
[44:27] there again. Did you see it coming? What
[44:30] lessons did you learn from how 2008 went
[44:33] that you could apply in 2023? Obviously,
[44:35] you bought First Republic.
[44:37] >> Yeah. So, Silicon Valley Bank, you know,
[44:39] they both Silicon Valley Bank for did
[44:41] some very good stuff, but they they both
[44:44] had something something unique that we
[44:45] didn't know at the time. I'm going to
[44:47] call them concentrated deposits, not
[44:49] uninsured because people have misdained
[44:51] that concentrated. And so a lot of
[44:53] venture capital, what happened with
[44:54] Silicon Valley Bank and kind of First
[44:56] Republic is some of these large venture
[44:58] capital companies,
[45:00] call them there, hundreds of them, maybe
[45:01] a thousand, told their constituent
[45:03] clients that they invested in who all
[45:05] bankked in Silicon Valley and First
[45:06] Republic, the banks aren't safe, get
[45:08] out. And they all removed their deposits
[45:11] in Silicon Valley Bank, I think they had
[45:13] 200 billion deposits, 200 billion,
[45:14] 100red billion in one day.
[45:16] And that caused the problem. But they
[45:18] also had other problems. They didn't
[45:20] have proper liquidity. Uh they didn't
[45:22] have their collateral post at the Fed
[45:24] and they had taken too much interest
[45:25] rate exposure. And the interest rate
[45:27] exposure was hidden by accounting. It
[45:29] was called held to maturity. But you
[45:31] don't have to mark even treasuries to
[45:33] market. And I always hated held to
[45:35] maturity because uh but it gives you
[45:37] better regulatory returns and stuff like
[45:39] that. But when that held to maturity the
[45:41] t if you said what's the tangible book
[45:43] value of one of these banks and you said
[45:44] it was 100. Well, all of a sudden it was
[45:46] 50 if you just marked that one thing to
[45:48] market and and there's now here now
[45:50] you're into judgment land. At what point
[45:52] if you saw a bank where just that one
[45:54] mark had the tangible book value dropped
[45:56] to 40 or 30 cents to the dollar would
[45:58] you panic? I would have said that's too
[46:00] much risk and you know the regulators
[46:03] helped us because they said rates are
[46:04] going to stay low forever. So these
[46:06] banks bought a lot of 3% mortgages and
[46:08] when you know 3% mortgage when rates
[46:10] went up to 5% you know worth 60 cents on
[46:13] the dollar or 50 cents and that was it.
[46:16] And so both those had they took too much
[46:18] interest exposure known to management
[46:20] and it was known to the regulators and
[46:22] you know uh and fixable. So you know we
[46:25] we knew about a little bit about Silicon
[46:27] Valley Bank. We were trying to compete
[46:29] in that area. So we learned a lot
[46:30] afterwards about how to do a better job
[46:32] for that ecosystem of venture capital.
[46:34] We have a whole campus in Powalto now.
[46:36] We've hired 500 innovation bankers. We
[46:38] cover venture capital companies. We're
[46:41] not as good as they are yet. We're we're
[46:42] going to get there because we're we're
[46:43] organized slightly differently. And we
[46:45] knew First Republic. We were watching
[46:47] it. I had called Janet Yellen that I
[46:49] said that that company's in trouble and
[46:51] one or two others. If you want to, we'll
[46:53] take a look. We could probably buy it
[46:54] and eliminate the problem. They waited a
[46:57] little bit too long. It was kind of a
[46:58] little melting ice cube. Uh but you
[46:59] could imagine the day we bought it, you
[47:01] never heard about it again. We hedged
[47:03] all their exposures in a couple of days
[47:05] and you know we merged everything in. We
[47:06] wrote everything down and but we did get
[47:09] some good stuff from we actually got
[47:10] some good people. You know the normal
[47:12] thing in acquisition is they're terrible
[47:14] get rid of them or they failed but we
[47:16] also looked at what they did how they
[47:18] dealt with clients maybe clients here.
[47:19] They did a great job with high net worth
[47:21] clients single point of contact you know
[47:24] conscious services. So now if you go
[47:26] down Madison Avenue you see things
[47:27] called JP Morgan Financial Center.
[47:30] That's your first JP Morgan branded
[47:32] consumer effort, right?
[47:33] >> Yes.
[47:34] >> Because it's it's kind of based on that.
[47:36] Then when you walk in there, we know
[47:37] your small business, we know your
[47:38] mortgage, we know your consumer banking,
[47:40] we can get you travel, we can do a whole
[47:42] bunch of different stuff. So very high
[47:44] level uh services. I think we have 20 of
[47:46] them now. But I'd love it. And if it
[47:49] works, you know, in 20 years, we have
[47:50] 300. And so these things are
[47:52] opportunities and I hope it works. You
[47:54] know, you don't always know they're
[47:54] going to work for a fact, but but so far
[47:57] so good.
[47:58] >> All right. So we're we're effectively
[47:59] caught up to today and if we're trying
[48:00] to and now we've got the whole story.
[48:02] We've got a lot of context. Obviously
[48:04] let didn't go into every detail but if
[48:06] we're now trying to answer yes if we're
[48:08] now trying to answer the question how
[48:10] did you separate from the pack? Why did
[48:12] you become a completely different animal
[48:13] than your whole competitive set? What
[48:16] are the things in your mind that led to
[48:18] this success?
[48:19] >> What we do is the same thing that a
[48:20] community bank does other than
[48:22] investment bank global investment
[48:23] banking. Okay. So if you walk into a
[48:26] small community bank, they know your
[48:28] business account. They know your
[48:29] consumer account. They usually have a
[48:31] trust company. They used to m they used
[48:33] to call it trust. They'd manage your
[48:34] private affairs. They'd set up a trust
[48:36] for you and they do stuff like that. And
[48:38] their CRM is up here. They don't need a
[48:40] Salesforce CRM because they know
[48:41] everyone in town. And they didn't do
[48:44] big-time global investment banking. But
[48:47] the strategy, those businesses fit
[48:48] together. They feed each other. And so
[48:50] does investment banking. A lot of our
[48:52] middle market clients use investment
[48:54] banking products. A lot of our consumer
[48:56] clients use some FX. So all of our
[48:58] businesses feed each other. There's no
[49:00] extraneous. We got rid of everything
[49:02] that didn't fit a strategy. And then you
[49:04] start building client businesses and
[49:06] client services, Fortress balance sheet,
[49:09] fortress accounting, all those various
[49:10] things. And and you know I and I've
[49:12] always talked about
[49:14] >> so it's it's it's holding a portfolio of
[49:16] things that actually feed each other.
[49:18] they actually fit. Whereas, you know,
[49:20] City had consumer consumer finance, that
[49:23] didn't fit. Life insurance, that didn't
[49:24] fit. Property C, that didn't they
[49:26] eventually got rid of them all. Sandy
[49:27] just wanted to do more of them. You
[49:29] know, he bought American General, which
[49:30] did uh truck leasing for God's sake. I
[49:33] mean, and you once you get involved
[49:35] these things, it's hard for people to
[49:36] understand the risk in each one of these
[49:38] businesses when But all of ours fit. I
[49:41] don't like hobbies. I don't like things,
[49:42] you know, we made and we've made plenty
[49:43] of mistakes because you you have to try
[49:45] and test things and then you're always
[49:47] investing for the future. That
[49:48] investment is always people, branches,
[49:52] and technology. And that's true whether
[49:54] they're investment banking people or
[49:56] consumer bank people or opening consumer
[49:58] branches or I think Doug Doug Pen is
[50:00] here and Troy Roarback who run the
[50:02] global investment bank but they've
[50:03] opened you know commercial banking
[50:05] branches all over Europe and I think you
[50:08] were telling me I mean it's it's it's
[50:09] going great you know and it's feeding
[50:11] all other parts of the company so just
[50:13] sticking to your knitting constantly
[50:15] investing you know not overreacting to
[50:17] the market you know markets are like
[50:18] accordians and then sometimes you know
[50:20] it's a if you're strong when others
[50:22] aren't you have a chance to buy things
[50:23] you want to buy and then always look at
[50:25] the world from the point of view of the
[50:26] consumer. What do you want? How do you
[50:28] want it? How do you want to get it? Can
[50:30] we provide it to you? Uh uh in a way
[50:32] that makes sense for us too. You know,
[50:34] not going for the last dollar and not
[50:36] nothing like that. And so uh and
[50:38] building teams of people, you know, our
[50:39] people are curious and smart. They have
[50:42] heart. They have salt. They give a damn
[50:44] about uh you know, the guards in the
[50:46] company and the receptionists and uh you
[50:48] know, it's not just about the big- time
[50:50] bankers and people pounding their chest.
[50:52] you know, we don't try not to put up
[50:53] with that. And we have big-time bankers.
[50:56] They are exceptional, you know, and uh
[50:58] but the company, you know, serves the
[51:01] clients and we have uh and I think the
[51:03] clients know that
[51:04] >> when when you really dig in to start
[51:05] analyzing JP Morgan's financials, you
[51:07] kind of see this one thing that jumps
[51:09] right out at you, which is the
[51:10] efficiency ratio. For every dollar that
[51:13] you make compared to your competitors,
[51:16] you get to keep 15 cents more of that
[51:18] dollar as profit. It's not hard to see
[51:21] how that compounds and how that allows
[51:23] reinvestments. And why is your
[51:25] efficiency ratio so much better than
[51:27] competitors? It's it is literally
[51:30] continuously investing and gaining
[51:33] business at the margin and not stopping
[51:35] and not stop starting. And the thing is
[51:38] the thing about margins too is that we
[51:40] we have that margin while investing a
[51:42] lot. It's much easier to have that
[51:44] margin and just you know we can cut
[51:45] billions of dollars of marketing out
[51:47] tomorrow. we can stop opening branches
[51:49] and save a billion dollars next year. We
[51:50] could do a lot of things. Your margins
[51:52] will go up, your growth will go down,
[51:54] your long-term margins will probably get
[51:55] worse. Uh so we kind of look right
[51:57] through the cycle and we look at the
[51:59] actual economics what we do, not the
[52:00] accounting of what we do. Uh and you
[52:03] know, we have, you know, we've built it
[52:04] over time. You know, we have great
[52:06] people and great products and there
[52:08] there's some secret sauce I'm not gonna
[52:09] tell you about. We do investor day and
[52:12] we tell everyone everything and I'm
[52:14] sitting there watching my I never do
[52:16] presentations. I'm watching them do the
[52:18] presentations. I'm saying, "Oh god,
[52:19] we're just giving away too many secrets
[52:20] here." But [laughter] but
[52:22] >> so there's secrets as to why.
[52:24] >> Well, you know, I saw Howard Schultz
[52:25] here before, you know, and I'm not
[52:27] supposed to say that probably.
[52:29] [laughter]
[52:29] >> It's okay.
[52:30] >> But no, but you look what look what he
[52:34] built over the years, you know, the
[52:35] consistency, the curiosity, the heart,
[52:38] the, you know, branch by branch
[52:40] products. It's just always doing that,
[52:42] knowing you're going to make mistakes,
[52:44] but building the culture that just kind
[52:45] of plows through that. And you all know
[52:47] I I do use sport. Sports is a great
[52:49] analogy. If you have a a sport team with
[52:52] a bunch of real jerks on it, are they
[52:53] going to be a great team?
[52:55] Almost never. You know, if a if the team
[52:58] members aren't giving it their their
[53:00] best every day during practice, you look
[53:02] at Tom Brady, every day at practice, he
[53:04] worked hard. You know, if people are not
[53:06] giving their best, how you're going to
[53:07] have a great team. And it's not that
[53:09] different in business. The difference in
[53:10] business, you can BS about it all the
[53:12] time. You can make up stories. But in
[53:14] sports, you see it, you know, on the
[53:15] playing field that do they have the
[53:17] team? Do they play together? They don't
[53:19] even have to be friends. They have to
[53:20] practice, know their teams. And so, I do
[53:22] think companies have that. It's like a
[53:24] sauce that works. You've seen it lots of
[53:26] different companies, you know, not just
[53:27] JP Morgan Chase.
[53:29] >> All right. We've got one last question
[53:31] for you. Uh if you look back to 2008,
[53:36] which was a long time ago now,
[53:37] >> to 2001
[53:38] >> to 2008, all of the other leaders that
[53:43] were involved in that era have long
[53:45] since retired. I mean, I think many
[53:47] folks within JP Morgan Chase have long
[53:49] since retired since then.
[53:52] It seems like you're working as hard as
[53:54] ever and in it as much as ever. Why are
[53:58] you still here? What keeps you going?
[53:59] >> Yeah. Uh, so I want to thank my wife
[54:02] who's here too who suffered through all
[54:04] this with me all these years and
[54:05] probably couldn't have done it. Couldn't
[54:08] have done it without her. Uh, [applause]
[54:12] I don't look I I I don't know, but I do
[54:16] believe [laughter]
[54:17] my my grandparents all Greek immigrants.
[54:19] >> There we go.
[54:20] >> My grandparents were all Greek
[54:21] immigrants who didn't finish high
[54:23] school. Uh, but there's a Greek ethic,
[54:25] you know, which I and you don't even
[54:26] realize you learn it from your parents,
[54:28] you know, from the ground up. And Judy's
[54:29] parents, my wife's parents were the
[54:31] same, which is, you know, have a
[54:33] purpose, you know, have and that it
[54:34] could be art, it could be science, it
[54:36] could be military, it could be business,
[54:38] it could be it could it could be just
[54:39] being a great parent, a great teacher,
[54:41] you know, but have a purpose and then do
[54:44] the best you can, you know, give it give
[54:46] it your all. Don't like be one of those
[54:48] people who's complain all the time, you
[54:49] know, you give it your best and uh and
[54:52] then treat everyone properly. everyone,
[54:55] you know, like I if I and including like
[54:57] if there was a bully beating up on
[54:59] someone, you had to stand up for the
[55:00] someone, you were not allowed to allow a
[55:03] bully to do it. So how you treat people
[55:05] what you do and so in in you know my
[55:07] hierarchy of life, the most important
[55:08] thing is my family uh still is. The
[55:12] second thing is my country because I
[55:14] think this country is the indispensable
[55:16] nation that brought freedom of speech,
[55:18] freedom of religion, freedom of
[55:19] enterprise
[55:20] uh which we have to teach everywhere we
[55:23] go about how important it is. I don't
[55:24] think people fully understand it
[55:26] sometimes. And then my purpose because
[55:28] you know they my family doesn't want me
[55:29] home every day and this is this is my
[55:32] contribution through this company. I can
[55:34] help cities, states, schools, companies,
[55:37] employees, and I I get the biggest kick
[55:39] out of that. And so, uh, that's what I
[55:42] do. And as long as I have the energy,
[55:43] I'm going to do it. I can't imag I'm not
[55:45] I don't play golf. You know,
[55:47] [clears throat]
[55:47] my daughter, one of my daughters said,
[55:50] "Dad, you need some hobbies." And I
[55:52] said, "I do. We hanging out with you,
[55:54] family travel, barbecuing, wine. We now
[55:57] like whisies and I love read. I love
[55:59] history. I think history is the greatest
[56:01] teacher of all time. Hiking. I can't
[56:03] play tennis anymore because my back, but
[56:05] those are my hobbies. I don't buy fancy
[56:07] cars and stuff like that, but this gives
[56:09] me purpose in life beyond family and
[56:12] beyond country. Plus, I think this helps
[56:14] the country. You know, I get to do a lot
[56:16] of things for our country uh that I just
[56:18] think are quite meaningful from this
[56:19] job. And so, when I'm done with this, I
[56:21] don't know, I'll teach and write. I may
[56:22] write a book like Andrew Workin did. Uh
[56:25] I'll do something, but I got to do
[56:26] something. I'm not going to twiddle my
[56:29] thumbs and smell the flowers. Um there
[56:32] are a lot of people who have floated
[56:33] your name for uh political or policy
[56:35] roles over the years. There is only one
[56:38] job that could possibly impact the
[56:40] country in a bigger scale than you're
[56:41] currently doing. Do you agree
[56:43] >> right now? Yeah.
[56:48] >> Well, that's probably a great place to
[56:51] [laughter] be.
[56:53] >> Jamie, thank you so much for joining us.
[56:55] >> David, Ben, these guys are great, by the
[56:57] way. So, [applause] thank you.
[57:01] Jamie Diamond everyone. Thank you.
[57:04] Appreciate it. Thank you.
[57:07] Thank you so much. Thank you.
[57:13] [music]
[57:18] Who got [music] the truth?
[57:21] Is it you? Is it you? Is it you? Who got
[57:23] the truth?
[57:26] Is it you? [music] Is it you? Is it you?
[57:31] Only service now connects every corner
[57:33] of your business. Putting AI to work for
[57:35] people.
[57:36] >> Every corner.
[57:38] >> Every corner. Nick. [music] So Kate in
[57:40] HR. Hey Kate can focus on people, not
[57:44] process. Patty in it is using AI agents
[57:46] to deal with the small stuff so she can
[57:48] work on the big stuff. AI helps Jim
[57:50] [music] solve customer problems before
[57:52] their problems.
[57:53] >> Oh, so we all work better together.
[57:56] >> My work here is done. Excuse me, which
[57:59] way back?
[58:00] >> I started this brand because [music] I
[58:02] started being told no, no to my dreams.
[58:06] >> So, I didn't have any design experience.
[58:08] I didn't have any business experience,
[58:11] but I really [music] had a sort of
[58:12] belief.
[58:15] >> Running a business is really
[58:17] challenging, but I love it.
[58:20] >> This is so wild that I [music] actually
[58:22] from a dream started a business. We're
[58:24] Cheekbone Beauty. This is super ceramic.
[58:26] We [music] have finished that
[58:27] >> East Side Golf and we're powered by
[58:29] Shopify.
[58:30] >> Ladies and gentlemen, welcome back. I'm
[58:34] Andrew Ross Sorcin and this is a late
[58:36] night edition of Dealbook Meets Squatbox
[58:40] Meets Acquired. Please welcome back to
[58:42] the stage Ben and David.
[58:46] Gentlemen, [music]
[58:53] >> uh Andrew,
[58:55] >> hello.
[58:55] >> Hello. Hello. Uh it's so great that
[58:58] you're here. We're we're glad to have
[58:59] you here. But why are you
[59:01] >> Yeah, we we've got this whole
[59:03] >> I'm at the desk here. I'm used to being
[59:05] behind the desk.
[59:06] >> But we've got this like late night talk
[59:08] show with iconic New York company CEOs.
[59:11] Like we're going to be at the desk.
[59:13] >> Yeah. I had heard that you might be
[59:15] doing something with the New York Times
[59:16] and I grew up there, you know, and so I
[59:18] just wanted to help you with, you know,
[59:19] notes, questions, research, whatever you
[59:22] were you were working on.
[59:23] >> Yeah. That's why I I I sat down.
[59:26] >> No, no, I I mean, I think we we got it.
[59:28] Uh we
[59:29] >> we did a whole three-hour episode a few
[59:31] years ago about the New York Times.
[59:32] >> You don't need me that.
[59:34] >> But I do I really appreciate you coming,
[59:35] though. I mean, it means a lot.
[59:37] >> Okay. If you know so much, can we just
[59:39] do a little quiz?
[59:40] >> Yeah, let's do a little quiz.
[59:41] >> Little New York quiz. Uh we'll have
[59:44] everybody participate.
[59:46] Here's a big question for you. Uh what
[59:48] year was the New York Times founded?
[59:51] >> 1851.
[59:52] >> Bingo. Bingo. Bingo.
[59:53] >> It's top of mind.
[59:55] >> Okay, that's one. Question two. Who once
[59:58] defended the New York Times building
[60:02] from the rooftop with a gun?
[60:04] >> Yeah. Adolf Ox.
[60:05] >> Nope. Nope. Nope. Nope. Nope. That was
[60:07] the original co-founder of the paper,
[60:09] Henry Raymond. But Ox gets you style
[60:11] points. He bought the paper, by the way,
[60:13] from Raymond. Okay, this one. I wonder
[60:15] if this whole room is going to know this
[60:16] one. Uh, what iconic New York location
[60:21] is named after the New York Times?
[60:24] >> Oh, Times Square. Of course, we have a
[60:26] billboard there. And then final
[60:27] question, who is the most iconic CEO in
[60:31] the New York Times company's modern
[60:33] history? And that person might be
[60:35] backstage as we speak.
[60:37] >> We know this one.
[60:38] >> Yes, we do. New York City. Please
[60:40] welcome the CEO of the New York Times
[60:43] company, Meredith Copit Levian. Heat.
[60:46] Heat.
[60:49] [music]
[60:56] [music]
[61:04] >> [music]
[61:06] [applause]
[61:07] >> That was fun.
[61:08] >> A huge thank you to Andrew Ross and
[61:10] everybody Andrew Ross. [applause]
[61:13] >> I'll go anywhere Andrew Rosin goes.
[61:15] >> And he is out late for a taping at 6
[61:18] a.m. on CNBC. So,
[61:19] >> got to go get some sleep.
[61:20] >> I think he is. I think he is.
[61:22] >> Well, Meredith, it is great to have you
[61:24] here today. Uh, if there is one acquired
[61:28] episode in the canon that is
[61:30] quintessentially iconically New York,
[61:33] it's the New York Times company, of
[61:35] course. And you guys, you're killing it.
[61:38] Uh, as we talked about in our episode,
[61:39] in 2008, the company was on the brink of
[61:42] death. You had sold your headquarters
[61:44] building. And here, in the few short
[61:47] years since then, you are the largest
[61:50] digital subscription newspaper in the
[61:52] entire world. You are the only
[61:56] standalone global newspaper company
[61:59] left, market cap of almost 10 billion,
[62:02] an all-time high.
[62:03] >> Publicly traded in
[62:04] >> publicly traded. Things are going great.
[62:07] >> Is that a That's
[62:08] >> Is that a question?
[62:09] >> Is that what [laughter] So tonight I
[62:11] mean,
[62:11] >> keep going. Keep going.
[62:13] >> We just You just sit there. We'll just
[62:14] talk about you.
[62:15] >> Uh so tonight, what we want to do, you
[62:16] know, it's been four years since our
[62:17] 2021 episode. We want to ask you about a
[62:20] bunch of things that have happened since
[62:21] then sort of as an update for the
[62:23] acquired audience and the acquired
[62:24] Canon. So, first, how is the
[62:27] subscription business going and what has
[62:29] stayed the same and what's changed since
[62:30] that big 2014 innovation report that
[62:33] changed everything?
[62:34] >> Um, well, thanks for having me. I'm so
[62:36] delighted to be here with you guys. Um,
[62:39] it's going well. It's going well. I
[62:41] think where you left off, we had about 5
[62:44] million subscribers in 2021. We are
[62:47] closing in now on 12 million and the
[62:50] company is growing as you described.
[62:53] It's growing revenue, it's growing
[62:54] profit. I think more importantly it's
[62:56] growing in its journalistic impact. It's
[62:59] growing in its its cultural impact and
[63:01] we really look out and see sort of
[63:04] growth possibility in in all directions.
[63:08] Um every week now 50 to 100 million
[63:11] people are coming to the times website
[63:14] and apps. some 20 million or so people
[63:17] listen to our podcasts and read our
[63:19] newsletters. We've got like 150 million
[63:23] people who've registered with us and
[63:25] counting that number is still growing.
[63:27] Millions of people use it every day. So
[63:30] that all feels like like real growth
[63:33] possibility. Um you ask about 2014. And
[63:37] I'd say that's the year where we set on
[63:39] the course to to kind of a long-term
[63:42] strategy about being essential in
[63:44] people's lives. Back then, print was
[63:48] still the lion share. It was still the
[63:49] dominant engine of the business. And we
[63:52] were we were still doing great at the
[63:55] journalism, but I will say we were
[63:56] getting our clocks cleaned by digitally
[63:59] native upstart journalism companies at
[64:02] building a big audience for that
[64:04] journalism. So I think you asked me
[64:07] what's different now. I would say one
[64:11] print is well the newspaper is well
[64:14] inside of 30% of the business. Um we've
[64:17] got a huge engaged audience as I just
[64:20] described.
[64:21] >> Wait, the physical newspaper is still
[64:23] almost 30% of the business.
[64:24] >> It's well inside. It's probably 25. But
[64:27] yeah. Yeah. And by the way, it's going
[64:29] to be around a long time. People love
[64:30] it. Um, the thing that I think I, you
[64:35] know, thi think you're gonna we're going
[64:37] to talk about, but we've got a much
[64:39] wider product set now in every way. More
[64:42] coverage, more topics, more formats. We
[64:45] show up in people's lives in in new and
[64:47] different ways. And I think maybe the
[64:50] last thing I'll say is culturally we
[64:52] sort of found our way to go from playing
[64:56] defense to playing offense. You know, we
[64:58] we were defined back in 2014 by this big
[65:02] question. Could we transform out of
[65:05] being a newspaper company and I think
[65:07] now we're defined by our ambition for
[65:12] what is all that the New York Times and
[65:14] journalism broadly can be and do in
[65:16] people's lives.
[65:17] >> So what is the strategy then? You've
[65:20] expanded well beyond news. There's
[65:22] games, there's sports, there's the wire
[65:24] cutter,
[65:25] >> cooking cooking, recipes. means it's
[65:28] subscriptions to things beyond news.
[65:30] >> It feels like in a lot of ways you guys
[65:33] have actually recreated what the
[65:36] newspaper was back in the day. Like it
[65:38] wasn't just news when you got a you know
[65:39] stack of newsprint every day or every
[65:41] Sunday delivered. It was lots of things.
[65:43] It was comics. It was shopping. It was
[65:45] classified.
[65:46] >> I would sort of describe it as you are
[65:48] the largest first party content company
[65:52] by subscriber count in the world. I mean
[65:54] what other you're it's it's more than a
[65:56] newspaper now. Am I thinking about that
[65:58] right?
[65:59] >> Yeah. Um the the easiest way to think
[66:02] about it is we are aiming to be the
[66:05] essential subscription for curious
[66:07] people everywhere who want to understand
[66:09] and engage with the world. And there's
[66:12] there's sort of three ways we're going
[66:13] about that. One, we want to be the
[66:15] world's best news destination. Hard
[66:18] stop. Um, two, and you're pushing on
[66:20] this, um, through building and buying,
[66:23] we, you know, have these marketleading
[66:26] lifestyle products and we want those
[66:28] products to help people make the most of
[66:30] their lives and passions. And we have
[66:33] put all that together in like a
[66:36] connected product experience or bundle
[66:39] so that the New York Times is valuable
[66:41] in your life, whatever is going on.
[66:44] >> So, build or buy. I mean, it sounds
[66:46] really good to have all this other
[66:47] stuff. Often these
[66:50] expansions fail at businesses.
[66:52] Acquisitions fail. Oh, we're going to
[66:53] launch a cooking section or a local that
[66:55] just fails.
[66:55] >> Comparison shopping.
[66:57] >> Why Why do you have what five, six,
[66:59] seven expansions now that are working?
[67:01] What's what's
[67:02] >> Well, they've been a combination of
[67:04] building and buying, but I would say um
[67:07] we've in my time at the Times, there are
[67:09] three companies that we've bought that
[67:11] three things we've acquired that have
[67:14] gone really well because they've they
[67:16] hang from that deliberate strategy I
[67:18] just described. The Wire Cutter, which
[67:20] is like a modern-day Consumer Reports,
[67:23] product reviews. um The Athletic, which
[67:27] um has, you know, the to our knowledge
[67:30] the world's largest sports newsroom at
[67:33] 550 journalists and counting. And then a
[67:36] little thing you might have heard of
[67:37] called Wordle, um which we actually
[67:39] acquired the same week as The Athletic,
[67:42] which is very very
[67:44] >> 50 million, single digit million.
[67:46] >> Well, we might have to do our greatest
[67:49] price difference between the two. Let
[67:51] let me say the thing that sort of
[67:53] unifies all of them. These are um these
[67:57] are experiences that sit in giant
[68:00] spaces. Um so there's a big market, you
[68:03] know, for sports, for games, for for
[68:05] shopping advice, and for recipes. Um so
[68:08] that's that's one. Two, I would say
[68:11] there are things where we felt like the
[68:13] Times could do something rare and really
[68:16] valuable. Um I talk about the size of
[68:18] that athletic newsroom. And by the way,
[68:20] the athletic audience is the fastest
[68:22] growing audience on the times because
[68:24] that just like if you're a sports fan,
[68:27] where are you getting your, you know,
[68:28] your really good hardcore in the locker
[68:31] room sports journalism from? And then
[68:33] they're also in spaces where people are
[68:35] doing something all the time. You're
[68:38] shopping people people shop all the
[68:40] time. Wire cutter drove something like a
[68:42] billion dollars of of commerce last
[68:44] year. And the the real magic of all of
[68:46] this is that the whole is kind of more
[68:49] than the sum of the parts. Each one each
[68:52] part of the portfolio and our news
[68:54] coverage kind of feed each other. So,
[68:57] you know, it's just as likely for
[68:59] someone to come in to play a game and
[69:01] then read a story about the war in
[69:03] Ukraine as it is the other way around. H
[69:06] >> we were talking a few weeks ago about
[69:10] the importance of
[69:12] first party owned and operated you
[69:15] consuming New York Times company content
[69:17] on New York Times company owned sites we
[69:20] feel the same way please do that yes
[69:23] [laughter]
[69:23] >> uh in the age of AI
[69:27] >> it's interesting right that you are a
[69:29] human curated company everything that
[69:32] the New York Times does is human curated
[69:34] >> absolutely But a lot of the people in
[69:36] this room, they turn to AI to do a lot
[69:38] of the things that you just described
[69:40] and yet business is going great. How do
[69:42] you think about that?
[69:43] >> Yeah. Well, um, let me say a a few
[69:46] things about the times and about AI. The
[69:49] first one is that we firmly believe that
[69:53] journalism, particularly journalism
[69:55] about, you know, important things going
[69:57] on in the world is first and foremost a
[70:00] human endeavor. It is by humans. It is
[70:02] for humans. you're not going to send you
[70:05] might send a drone, but what they are
[70:07] going to find on the front line of a war
[70:09] versus a human being talking to people
[70:11] who've just been impacted, I think those
[70:13] are just like two different things. Um,
[70:17] so that's one. Two, we um feel really
[70:22] optimistic that AI has the potential to
[70:26] be like a force multiplier to everything
[70:29] we do. And what does that look like? It
[70:32] looks like making our journalism much
[70:34] more accessible to people. Um, I'm a
[70:37] runner and I now take in um, a lot of
[70:41] the New York Times text articles
[70:43] listening to an automated voice read
[70:44] them to me most most mornings and we're
[70:47] just at at the beginning of that. We
[70:49] have journalists who are using AI in
[70:53] some instances to comb through like huge
[70:56] troves of public documents to to get to
[71:00] a story in a in in a better in a better
[71:03] way. And I could go on and on, but the
[71:06] the the idea is AI sort of appended to
[71:12] 3,000 human beings doing journalism,
[71:14] making games, recipes, and so forth.
[71:17] It's the combination of those those
[71:20] things. And the last thing I'll say is
[71:23] I'm very optimistic about AI assuming
[71:27] that you know the journalism we spend a
[71:30] ton of end games and everything else we
[71:32] do spend a ton of money on and work
[71:34] really hard at um through human beings.
[71:39] You know, I believe it's going to be
[71:41] great as long as that doesn't all get
[71:42] misappropriated
[71:44] by the large language model makers. Can
[71:47] we ask you about the Open AI lawsuit?
[71:49] You're
[71:50] >> suing OpenAI at Microsoft for
[71:52] >> training without permission on New York
[71:54] Times content.
[71:57] >> Why?
[71:57] >> Why? Well, what [laughter] why did you
[71:59] why did you decide to file the lawsuit?
[72:02] >> Yeah. Um listen, the first thing to say
[72:06] is that um these companies making large
[72:09] language models are spending hundreds of
[72:12] billions of dollars on compute and
[72:15] energy and on talent. We've seen lots of
[72:19] stories about that in recent days. And
[72:21] so we believe they should also be
[72:22] spending money that equates to fair
[72:25] value exchange on the content um that
[72:28] they have built their models on. So
[72:29] that's that's one. Um [applause]
[72:34] we believe the law is on our side. Um
[72:39] and by the way, not just the side of
[72:41] journalism. This is not just an issue
[72:43] for news organizations, although that is
[72:45] pretty important issue to society. This
[72:48] is an issue for anybody who makes
[72:50] creative work, anyone who makes IP. And
[72:53] I want to say that like America having a
[72:57] flourishing community of creators, IP
[73:00] makers, that's like foundational to our
[73:03] competitiveness, really important to how
[73:05] we we show up in the world. This is a
[73:08] big broad issue. We think the law is on
[73:11] our side and we um have a lawsuit as
[73:15] you've just described and we are also um
[73:19] you know sort of eager to partner with
[73:22] companies when the terms are right and
[73:24] make sense and as we've done we just did
[73:27] a partnership with Amazon and we did
[73:30] that because we saw it as having
[73:31] sustainable fair value exchange and
[73:33] giving the times control over how its
[73:36] journalism and other content would be
[73:38] would be
[73:39] So, there's a thing that a lot of people
[73:42] probably, especially in this audience,
[73:43] have in their mind that wasn't really a
[73:45] thing yet when we did our episode in
[73:47] 2021, which is this perceived anti-tech
[73:50] bias or anti- business bias of the New
[73:52] York Times. When people bring that up to
[73:54] you, you would say, "What?"
[73:56] >> First, I'm not sure a lot of people have
[73:58] that in mind. I'll I'll challenge that
[74:00] that premise, but I will say we don't.
[74:04] It's not a thing. Um the the you know
[74:08] the job of the New York Times is to
[74:11] pursue the truth wherever it may lead
[74:14] and sometimes that's to uncomfortable
[74:17] places. And we do that job kind of first
[74:21] and most by reporting. What is
[74:23] reporting? Reporting is we're going to
[74:25] unearth new facts that we think and
[74:27] others think matter in the world to a
[74:30] lot of people. And it's worth saying
[74:32] because I do get asked about bias all
[74:34] the time on on any topic. It's worth
[74:37] saying we put an enormous amount of
[74:40] effort and care and money and method
[74:43] into trying to reduce bias in every way
[74:46] we can in the process. We have a giant
[74:48] standards operation that really says
[74:51] this is this is an okay source or or
[74:54] this isn't that really says yes, these
[74:57] are verifiable facts or they aren't.
[74:59] Every story at the New York Times is
[75:00] edited by at least two people. I could
[75:03] go on and on about all all the ways we
[75:05] sort of hold ourselves to account. And
[75:07] on tech in particular, I want to say
[75:10] that these many of the tech companies,
[75:14] the big tech companies that shape the
[75:16] information ecosystem have a level of
[75:19] kind of power and influence and the
[75:22] potential to drive profound change in
[75:25] people's lives in a way that governments
[75:27] or or nations might. So we we cover them
[75:30] accordingly. And by the way, we cover
[75:33] them really broadly. We did a package on
[75:36] AI and just like a view from today of
[75:38] what is it going to do in people's
[75:40] lives. And there was as much in there
[75:42] about all the great things AI is going
[75:45] to do. And I do think the more we expose
[75:48] people to reporting, which we do on the
[75:50] daily and in lots of other formats, the
[75:53] more they trust us and the more they see
[75:55] the lengths that people like Andrew
[75:57] Osorin go to to to really help you
[76:00] understand a really I mean just to
[76:03] underscore like the shift that's
[76:04] happened in the last 15 years. I mean
[76:06] since the financial crisis where tech
[76:08] was one industry among many and now is
[76:11] responsible for the majority of the
[76:12] market cap in this country in this
[76:14] world. all trillion dollar
[76:15] >> it's a big it's a big reason why people
[76:16] listen to acquired so like we you know
[76:18] we feel it too um
[76:21] >> on that topic of media evolution of
[76:24] media close to home for us you're home
[76:27] of some of the biggest podcasts in the
[76:29] world
[76:29] >> like how either podcasting specifically
[76:32] or all the different media you're doing
[76:34] beyond the written word like how do you
[76:36] think about delivering journalism today
[76:38] >> yeah um I was once standing I started
[76:41] the times 12 years ago and I was
[76:42] standing with Andrew Russin in a green
[76:44] room. I think I was there as his
[76:45] handler. He must have been like going to
[76:47] talk to an advertiser. And I grabbed him
[76:49] right before he walked on stage and I
[76:51] said, "Don't talk about the paper." Like
[76:54] we're not we're not just a paper
[76:56] company. And I would say that is how we
[76:59] think about and approach like whatever
[77:01] the delivery mechanism is. If it's text,
[77:04] if it's video, if it's audio, we're just
[77:07] thinking, how do we bring our work and
[77:10] engage the widest possible audience and
[77:13] podcasts, the thing that you do have
[77:15] just been great for the times and doing
[77:17] that, we've got lots of hit shows and
[77:20] what they, you know, the daily, the Ezra
[77:22] Klein show, our new show, which is sort
[77:25] of like the new rights answer to the
[77:27] Ezra Klein show, interesting times with
[77:29] Ross Det,
[77:31] which I think is kind kind of similar to
[77:33] you. What are those shows doing for us?
[77:35] One, they are deepening the engagement
[77:38] we have with people who already love the
[77:40] Times. They're making many, many, many
[77:42] new people love the Times. And I think
[77:45] really importantly, they're building
[77:47] they're helping us build a different
[77:49] relationship with the people we're doing
[77:52] this coverage and making these products
[77:54] for. You know, when I meet someone um
[77:57] whose podcast I listen to as I'm doing
[78:00] with you guys, I think you're my running
[78:02] partners because I've spent like hours
[78:04] on a run listening to the two of you
[78:06] talk. And I think it's just a different
[78:08] kind of kind of relationship. Let me say
[78:10] this about the daily when we figured
[78:13] this out early in its life, but it's
[78:15] still the case today. When a reporter
[78:17] goes on the daily and tells the story um
[78:20] that they've just published on the on
[78:22] the homepage in the paper, um they're
[78:25] doing two things. They're talking um
[78:28] they're telling you about the story in a
[78:30] more casual way, almost like a friend
[78:33] guiding you through the news, but
[78:35] they're also exposing you to how that
[78:38] story came to be. And that is
[78:39] fundamentally doing the thing I talked
[78:42] about before. It's trust building. It's
[78:43] showing the people showing the people
[78:45] listening like this is how me at the
[78:48] lengths we went to to present this topic
[78:51] in a fair and like deeply reported way.
[78:53] >> All right.
[78:54] >> Can I say one more thing about podcasts?
[78:56] The banter
[78:57] >> talk about podcast all night.
[78:58] >> The banter is as in many cases I think
[79:01] this about you guys. I think this about
[79:03] hard fork which is our show about AI.
[79:06] It's New York Times reporter Kevin Roose
[79:09] and platformers Casey Newton. You're
[79:12] gonna I learn I'm running a company that
[79:14] has to contend with AI. I listen to
[79:16] every episode and you know what? Like I
[79:19] love their banter. The banter is like
[79:21] entertainment and it makes me take in
[79:23] what they're saying about AI even better
[79:26] because it it's like pushing into
[79:29] entertaining me as it's instructing me.
[79:32] >> That's what y'all are doing.
[79:33] >> We love the banter, too.
[79:34] >> Yeah. We we think about it as
[79:36] conversational storytelling where can
[79:39] you tell a narrative through two people
[79:41] talking?
[79:42] >> That's right. That's right. And the
[79:43] other thing podcast did for the times
[79:46] and you see this now if you go on our
[79:47] app and watch reporter video.
[79:49] >> I think it taught us how to sort of
[79:53] break free of like the tyranny of how a
[79:55] news article had to be presented in a
[79:58] newspaper. you can talk in a much more
[80:01] informal style and I actually think
[80:03] that's how news articles are still
[80:06] incredibly important but that has even
[80:08] spilled into the text news articles that
[80:11] we that the style of getting people
[80:13] information is much wider. All right.
[80:16] So, we have something that we've
[80:17] prepared. If you're open to
[80:18] >> coming back,
[80:19] >> he uh I [laughter] believe he's back in
[80:21] his seat. We can we can [clears throat]
[80:22] check. Uh
[80:23] >> I wonder who you have there. I'm scared.
[80:25] >> We started this conversation talking
[80:26] about games.
[80:28] >> Yeah.
[80:28] >> Uh Wle has taken an enormous amount of
[80:30] my time.
[80:31] >> We would like to take some of your time.
[80:33] >> Listeners, we asked the team at the New
[80:35] York Times to create a custom Wordle
[80:38] themed around something specific to
[80:40] acquired. Are you game?
[80:42] >> I am game. I think I think I brought my
[80:45] glasses. I didn't know if it would get
[80:47] >> I think this is the first live Wordle
[80:49] from radio.
[80:50] >> And I do want to say I would have rather
[80:53] played Connections. I'm [laughter] so
[80:54] much better and faster at it. So much
[80:57] better. I'm not very good at Wordle. My
[80:59] mom smokes me on it every time I
[81:01] >> We'll give you a hint to get started.
[81:03] The word is very deeply related to a
[81:05] canonical acquired episode.
[81:08] >> Okay. All right. [laughter] In in other
[81:11] words, whatever your favorite starter
[81:12] word is a good place to start.
[81:13] >> And can they see what I'm doing?
[81:15] >> I think so. I mean, pretty nifty camera
[81:18] back there.
[81:18] >> There we go. All right.
[81:19] >> All right. All right. I'm using the
[81:21] starter word I always use, which I'm
[81:23] sure twothirds of the room uses.
[81:25] >> All right. How'd you do?
[81:26] >> And that sucked.
[81:28] >> That really sucked. [laughter]
[81:29] >> Sorry.
[81:31] >> Okay. I'm going to go to another word
[81:32] that I told myself I was going to use if
[81:34] you made me do this.
[81:35] >> Great.
[81:38] Oh, it's that's a tough draw.
[81:40] >> And then I'm going to go to a word.
[81:41] Let's see if it's the right number of
[81:42] letters that gets at how I feel about
[81:46] this.
[81:48] >> Hey. [laughter] All right. We'll start
[81:50] giving you some hints. It is a person's
[81:52] last name who is arguably the founder of
[81:56] a company of one of our
[81:57] >> of the company.
[81:58] >> Of the company. Yeah. Yes.
[82:00] >> Okay.
[82:00] >> It is one of the world's largest
[82:02] >> It's nice. It's not Yeah. Keep going.
[82:04] Keep going. is the the predecessor
[82:05] company of one of the world's largest
[82:07] retailers.
[82:10] >> Is the name I think you just gave it to
[82:12] me. Hold on.
[82:16] >> Oh,
[82:19] >> I would never have gotten that. I would
[82:21] never have gotten that without him.
[82:23] >> We had to work.
[82:24] >> Okay. Can we just say go me on Bripe?
[82:28] >> That really helped. All right.
[82:30] >> All right, everyone. Meredith Copit
[82:31] Levier.
[82:32] >> Lots of fun. Thank you. So fun.
[82:36] [music]
[82:39] Thank you so much. Terrific.
[82:42] [music]
[82:49] >> That was fun. [music]
[82:50] >> Great to see Meredith tonight.
[82:51] >> It was It was also really great of the
[82:54] New York Times company to make a whirl
[82:56] for us. Great to get some acquired
[82:58] trivia in there. So, speaking of
[83:01] acquired trivia,
[83:03] before we bring out our next guest, we
[83:06] want to play a little uh game of our own
[83:07] here with some audience participation.
[83:10] So, [cheering]
[83:12] we have a question for all of you here
[83:14] tonight. See if we can we can stump
[83:16] folks in the audience. What is the most
[83:20] listened to episode in Acquired's
[83:23] history? In our 10y year history, which
[83:25] episode?
[83:26] >> Feel free to shout out your answer.
[83:29] Oh, great.
[83:31] >> Uh, I'm looking for someone I know. Is
[83:33] that Is that Christina Cassiopo?
[83:35] >> Hi, Ben. Hi, David.
[83:37] >> Hey, Christina.
[83:38] >> Christina, great to see you.
[83:39] >> For anyone who doesn't know, Christina
[83:41] is the uh co-founder of Vanta and I
[83:43] think a nine-year listener of Acquired.
[83:45] >> Yeah. OG. Thank you.
[83:49] >> All right, Christina.
[83:50] My stripes. Um, is it the Hermes
[83:53] episode?
[83:55] >> That is a very good guess.
[83:58] definitely up there, but it is not
[83:59] currently in the number one spot.
[84:02] >> I'm hearing other folks who might want
[84:04] to guess.
[84:05] >> Let's see.
[84:07] >> There's a hand. Is that Ben Climber?
[84:10] >> Hey, guys.
[84:11] >> Hey, Ben. Good to see you.
[84:13] >> You too, guys. Happy to be here.
[84:15] >> All right. So, Ben, for anybody who
[84:16] doesn't know, was indispensable on the
[84:18] Rolex episode. Uh, he's the founder of
[84:20] Hodinki. He's like a world expert on
[84:22] watches. Good to see you, Ben.
[84:24] >> Thank you, guys. [applause] Thank you.
[84:26] Um, so it's it's it's got to be Rolex,
[84:30] right?
[84:32] >> It's very close.
[84:33] >> Very close. Neck and neck. Ben, I don't
[84:35] think so. I I think it's the episode
[84:38] that I was in. [laughter]
[84:43] >> Ding, ding, ding, ding, ding. [applause]
[84:45] I think it's Starbucks.
[84:50] So far.
[84:52] Wait, wait, wait. Who is that? Is that
[84:54] Jamie saying so far?
[84:57] J Jamie, we'll be reporting numbers to
[84:59] you tomorrow.
[85:00] >> Yeah. Yeah. Yeah. [laughter]
[85:04] >> You're not competitive or anything.
[85:07] >> All right. Well, Howard, yes, you are
[85:10] right. It is our biggest episode ever.
[85:12] The Starbucks episode where Howard was a
[85:14] guest with 1.3 million downloads. Give
[85:16] it up for Howard Schultz, everyone.
[85:19] [cheering and music]
[85:24] >> [applause]
[85:27] >> We'll ask the same question next year
[85:28] and you know we'll see. [laughter]
[85:31] All right. Our final guest for the
[85:34] evening is a CEO who despite us having
[85:38] not yet covered his current company on
[85:40] acquired. I think over the course of his
[85:43] over 60-year career has led more
[85:46] companies in and around the acquired
[85:48] universe than just about any other human
[85:49] being in history. We've got
[85:52] >> Fox,
[85:53] >> Fox,
[85:54] >> ABC,
[85:55] Paramount,
[85:57] Expedia,
[85:58] >> Yep.
[85:59] >> Tinder and Match.com.
[86:00] >> Yep.
[86:01] >> QVC and the Home Shopping Network.
[86:03] >> Ticket Master.
[86:04] >> Ticket Master. I mean, this list is
[86:06] going on.
[86:07] >> He's also one of New York's most
[86:10] legendary citizens who along with his
[86:12] wife Dion von Fenberg has given so much
[86:15] to this city, including the Highline and
[86:17] most recently the Little Island. Please
[86:20] welcome the chairman of IA, the one and
[86:22] only Barry Diller.
[86:27] [music and applause]
[86:30] >> Thank you, Barry. Great [music] to see
[86:32] you.
[86:41] >> Why did she get a pillow and I don't?
[86:44] [laughter]
[86:45] >> She asked for one. She asked for one.
[86:47] >> Well, okay.
[86:47] >> Do you want one? It'll be on my rider
[86:49] next time.
[86:51] >> I think your rider was water.
[86:53] >> Yeah, that's it.
[86:54] >> So, pretty simple.
[86:54] >> Uh,
[86:55] >> you drove yourself here tonight. Is that
[86:57] correct?
[86:57] >> Uhhuh. Yeah. Yeah. Yeah. Of course I
[86:59] did.
[86:59] >> Wow. I
[87:00] >> drive everywhere in New York.
[87:02] >> How did you find parking?
[87:04] >> Uh, I just find some empty space
[87:08] even.
[87:08] >> No,
[87:10] it usually has a fire hydrant
[87:13] or other barriers and I scoot myself in.
[87:17] I guess if you give an island to New
[87:19] York, then do do you get to do you get a
[87:21] special part?
[87:22] >> No, no, no. I get tickets.
[87:24] [laughter]
[87:25] >> I get those tickets.
[87:27] >> Oh, well, very
[87:28] >> someday I'll pay for them. [laughter]
[87:32] >> I think you have had one of the most
[87:34] incredible careers in American history.
[87:36] I mean, you have touched the lives of
[87:38] every single person in this room. Uh,
[87:41] you recently wrote your memoir, Who
[87:43] Knew, which is excellent. The first
[87:46] chapter of your career was in Hollywood.
[87:49] And when you started in in 1961
[87:53] in the mail room at William Morris, this
[87:56] was still like old Hollywood. The studio
[87:58] system,
[87:59] what was it like back then? Feels like
[88:02] 1861, but when I think [laughter] of it
[88:04] now, well, I mean, it we did have
[88:09] typewriters and there was like, you
[88:12] know, there was some tech involved, but
[88:14] it was a it was a time when there were a
[88:16] lot of bigger than-l life personalities.
[88:18] Uh, the kind of old mogul that uh
[88:21] founded Hollywood were still they were
[88:24] kind of on their last feeble-ish legs,
[88:27] but I still got to know a few of them.
[88:29] And so
[88:30] >> Wasserman Sid Shinberg.
[88:32] >> Well, yeah. Even old Dar Daryl Xanic who
[88:36] founded 20th Century Fox and I met him
[88:39] like a few blocks down the road when he
[88:43] was kind of in his doage. He had this
[88:45] huge like 20 foot cigar and I sat in a
[88:49] in a proje in a theater Fox's theater
[88:52] projection room which had like 500 seats
[88:54] and he I was at ABC. I was a young
[88:58] executive at ABC and I was buying movies
[89:00] to show on television. And Xanic, who
[89:03] had uh all of these girlfriends that he
[89:08] could only keep as girlfriends so long
[89:10] as he put them in these rotten, horrible
[89:12] Fox movies. And the only way he could
[89:14] put them in these Fox movies is if I
[89:16] would buy them. [laughter] So
[89:18] >> Oh, great. There I sat with Daryl Xanic
[89:20] and his smoking cigar and me watching uh
[89:24] a scene from the most awful movie you
[89:28] could ever imagine.
[89:30] >> So yeah, I got those guys.
[89:32] >> Wow. Wow. [laughter]
[89:33] >> As I as I was reading your book and
[89:35] thinking about your career, you're one
[89:36] of these rare people that uh started in
[89:39] media and was successful in media and
[89:42] then jumped and became even more
[89:43] successful in technology. I mean, that's
[89:45] a very sort of rare chasm. It's an odd
[89:48] passive.
[89:48] >> Yeah. And when we say you started in
[89:50] media, you started in the mail room at
[89:53] the William Morris Agency, which is not
[89:54] a thing in tech at all. No, tech doesn't
[89:57] have mail rooms.
[89:58] >> There ain't no mail rooms left anywhere.
[90:00] >> But [laughter] at this time, well,
[90:04] probably not. But the great thing it had
[90:07] was it had a file room when there were
[90:09] actually digital files. big room,
[90:13] >> physical files,
[90:14] >> physical big, you know, I don't know,
[90:17] file cabinets, like 50 of them.
[90:19] >> And I basically read from A to Z. I read
[90:23] the entire file room when I starting
[90:25] when I was 19 until I was 22. So I I had
[90:29] because William Morris was the oldest
[90:31] and biggest talent agency. I' been in
[90:33] business 70 years. So I had the entire
[90:35] history of the entertainment business
[90:37] that I got to read. How could you do
[90:39] better than that? This is like you had
[90:41] the the email, you know, archives of of
[90:44] all the executives, right, in Hollywood,
[90:46] >> but not email.
[90:47] >> But I mean, it wasn't email
[90:50] negotiations.
[90:50] >> There was no emails. There was such
[90:52] thing as emails. There was no E. There
[90:54] was mail.
[90:58] And and so I it jumped out at me as I
[91:00] was reading the book because it felt
[91:02] like the thing that David and I have
[91:04] stumbled on with Acquired is immerse
[91:07] yourself in a massive amount of primary
[91:09] research. And the human brain is good at
[91:11] finding patterns in that. And it seems
[91:14] like you learned the entertainment
[91:15] business kind of the same way. You just
[91:17] let all these messages and files wash
[91:20] over you until it kind of clicked. I
[91:22] understand the way this industry works.
[91:23] Is that right?
[91:24] >> Well, yeah. You got to read I mean I got
[91:27] to read literally the history of Elvis
[91:30] Presley from the moment he recorded his
[91:33] first song through his entire career and
[91:37] and every other person in the entire
[91:40] spectrum of entertainment. So you can't
[91:43] get a better foundation. It depends of
[91:46] course what you use it for or whatever.
[91:48] There's no school you could go to that
[91:50] would ever teach you that.
[91:52] >> Yeah. So your your next chapter after
[91:55] the William Morris Agency is ABC.
[91:58] >> Yes.
[91:58] >> And you're working you know this this
[92:00] era 60s and 70s ABC is this crazy talent
[92:04] magnet for a lot of people. Think like
[92:06] Runaridge, Bob Iger. What made ABC this
[92:10] like
[92:11] >> ABC was the number three? There were
[92:13] three networks. They had 100% of the
[92:14] viewing. So about 100 million people
[92:17] divided
[92:20] never divided equally by three. ABC was
[92:23] the was the youngest by and actually at
[92:27] that time probably 20 years or so and it
[92:31] was the least established and so it it
[92:35] was run like a candy store. So if you
[92:37] wanted responsibility you could just
[92:39] take it and you could you you you could
[92:43] do new things or things that were deemed
[92:45] very risky because you had to take
[92:48] chances to get yourself landed. So it
[92:51] was also again serendipitously the
[92:54] greatest luck you could have to be 23
[92:56] years old
[92:58] >> and
[92:58] >> you're a vice president at 23.
[93:00] >> I was a vice president. No, that's
[93:02] really unfair. I mean it even makes it
[93:03] worse. I was at 25 and a half.
[93:05] >> Okay. Okay. Okay.
[93:07] >> That was still the youngest. It was the
[93:09] youngest ever. But yeah,
[93:10] >> but you're in charge of movies at this
[93:14] at ABC at 25 and a half, right?
[93:17] >> Yeah. Well, we started a thing called
[93:19] movie of the week, which no one had ever
[93:22] made original movies for television. Uh,
[93:26] and so we thought that was a good idea
[93:27] and everybody thought it would fail.
[93:29] Thank god or otherwise I would have
[93:30] never given it let me do it. It was
[93:33] truly inside of a network a total
[93:37] startup of building actually a movie up
[93:41] after two years we were making 75 of
[93:44] them a year. So we started with one
[93:47] employee, me, and I got to because I
[93:52] then hired all these people to do all
[93:54] these tasks. I had to learn those tasks
[93:56] as I was doing it. So I got up to
[94:00] understanding. I think it's the best way
[94:02] to learn to be a manager is to actually
[94:05] do the groundwork.
[94:07] And uh and so I got to do that and all
[94:11] the stuff I think I learned about if I
[94:14] ever learned anything people who work
[94:16] with me might uh not totally agree but
[94:20] uh learning how to manage people is
[94:22] because you understand the tasks that
[94:25] need to be done and I got that ability.
[94:28] >> We started making 25 and then it was so
[94:32] successful we added a second and then a
[94:34] third night. So, we were up to making 75
[94:38] of them a year. They cost I mean, it's
[94:41] inconceivable today when a single
[94:43] episode of a one-hour show can cost $10
[94:46] million.
[94:48] We made these movies for about 500
[94:53] 500,000 each.
[94:54] >> Wow. As you sort of learn the the movie
[94:57] side of things, how did Paramount end up
[94:59] coming into the picture for you? I'm a
[95:02] middle level vice president of ABC
[95:07] successful because the stuff I the
[95:08] movies and then the miniseries which we
[95:11] started to do too uh were all fine uh
[95:16] and I kind of got promoted above my
[95:18] level of competence uh because they made
[95:22] me take over all series programming. I
[95:25] didn't like series. They were all static
[95:27] and uh half hour and comedies and hour
[95:31] drama shows, you know, nothing ever
[95:33] happened to the characters because they
[95:34] had to stay in the same age and life
[95:36] that they were in in the storytelling.
[95:40] So I if I the rug would have gotten
[95:45] pulled out of under me even though I had
[95:47] been successful over there because of
[95:49] the serious stuff. And then, you know,
[95:52] the o over the horizon came my rescue in
[95:56] the person of the uh Charles Blueornne
[95:59] who owned a huge industrial conglomerate
[96:03] called G and Western and they owned
[96:05] Paramount and I had gotten to know him
[96:06] because I sold par movies to Paramount
[96:09] >> and that's a whole crazy story. They
[96:10] started Gulf and Western making bumpers
[96:13] for cars and ended up in a 100 different
[96:15] businesses including owning
[96:17] [clears throat] Paramount. He he sought
[96:19] the Puerto Rican sugar. Uh I mean I
[96:23] don't think there was I mean maybe they
[96:25] didn't do grave digging but I mean
[96:26] practically everything else. Well, they
[96:29] did make the Godfather in graves, but
[96:31] they they didn't really do that. But but
[96:34] they had so many business and it was
[96:36] this was a time in the 50s60s where
[96:40] conglomerates
[96:42] it and and Goff and Western was actually
[96:45] I think the largest and Charlie who at
[96:49] that time was in his 40s,
[96:52] maybe late 30s, early 40s.
[96:54] >> So he was young too.
[96:56] >> Yeah. and he had done this I mean in
[96:59] like 10 years he built this thing up
[97:01] anyway
[97:02] he had wanted me to come to work for
[97:04] Paramount and I never wanted to uh work
[97:07] there because I didn't like the
[97:09] management of Paramount and so I kept
[97:12] saying no to him and one day he ordered
[97:14] me up to his office and he said okay I'm
[97:17] going to make you chairman of Paramount
[97:18] I said Charlie this is insane I'm a vice
[97:21] president of ABC in television Paramount
[97:24] is a movie company. You can't do that.
[97:28] He said, "Oh, yes, I can."
[97:29] >> And that would make you the legendary
[97:31] Bob Evans's boss.
[97:33] >> Yeah. Uh, and he I said, "Mada." He
[97:37] said, "No, no, you're doing and actually
[97:40] I thought I went to Leonard Golden who
[97:44] was the, uh, chairman founder of ABC,
[97:48] uh, who had once actually worked as a
[97:51] kind of line person at Paramount and
[97:54] told him this and said, you know, I'm
[97:55] thinking, Leonard, of not doing it." He
[97:57] said, "If you're that stupid, I'll fire
[97:59] you." Uh, [laughter]
[98:02] so
[98:02] >> but you weren't really I mean you had
[98:04] the opportunity to run a movie studio,
[98:08] one of the five major movie studios.
[98:10] >> Yeah.
[98:10] >> In your 30s. This has never happened
[98:11] before.
[98:12] >> Uh, yeah, that's true. And and for the
[98:16] first two years, I kind of failed
[98:17] because I had to figure out how to do it
[98:19] the way I wanted to do it. And it was
[98:22] very trying. And and that rug really
[98:24] came close to pulling me out of it. And
[98:29] then we released a movie called Saturday
[98:31] Night Fever. And right after that,
[98:34] Greece.
[98:35] >> And And that was John Travolta's first
[98:37] movie, right? Saturday Night Fever.
[98:38] Saturday Night Fever was John Travolta's
[98:41] >> Yeah. Yeah. John Travolta came from
[98:43] television uh from a television series
[98:45] called Welcome Back Carter. And we put
[98:48] him in this movie and people said we
[98:51] were crazy. How can we put a television
[98:52] you television people the movie people
[98:55] were such snobs they kind of peed on the
[98:57] people in television and they thought
[99:00] how can you put this this this
[99:04] television comedy guy into this
[99:08] you know movie this big movie it wasn't
[99:10] that big a movie actually in terms of
[99:11] whatever but it was a real theatrical
[99:14] movie and the night first night we
[99:17] previewed it not previewed it we did we
[99:19] did a kind of semi little premiere here,
[99:21] the old Grman's Chinese Theater on
[99:23] Hollywood Boulevard, this famous old
[99:25] theater. And at about and he invited
[99:28] basically Hollywood to come because we
[99:30] were really proud of this movie. It was
[99:31] kind of my last gasp and I was proud of
[99:34] it although I certainly needed it to
[99:36] work and it was supposed to start at 8
[99:39] and at 7:45
[99:41] there was about 40% of the audience
[99:44] capacity was there. I mean it was like
[99:47] more than half empty. And the old
[99:49] publicity guy from Parent came over to
[99:51] me and he said, 'Well, you know, you put
[99:53] this Travolta and that kid just doesn't
[99:55] put asses in the seats.
[99:58] And I thought, "Oh god." And 10 days
[100:01] later, we opened it and there were lines
[100:03] around the block.
[100:04] >> Wow. And the thing that people didn't
[100:07] understand was the Hollywood snobs
[100:09] wouldn't come see John Travolta, but
[100:12] America was happy to line up because the
[100:14] movie got great reviews.
[100:15] >> Yeah. Hm. So you you're at Paramount,
[100:19] you're turning it around. You then make
[100:22] The Godfather 2, the original Star Trek
[100:24] movie. Saturday Night Mention is you
[100:26] Saturday Night Fever, as you mentioned,
[100:28] Greece, Indiana Jones. I mean, you go on
[100:30] a run.
[100:32] Paramount becomes the number one studio.
[100:34] Why did it work?
[100:35] >> Well, um, it's an assemblage. You know,
[100:38] that's the bimbo thing. You know, there
[100:40] are so many people to thank. It was
[100:42] basically me. No,
[100:45] it's not true.
[100:49] >> Diller, everyone.
[100:50] >> No, it is not true. It worked because I
[100:54] think we brought a different we brought
[100:57] a you know in the television business
[100:59] you develop material and you work on it
[101:02] for a long time. uh and you do this kind
[101:05] of ratio of development process where
[101:07] you may have
[101:09] uh 30 40 projects and you pick just a
[101:12] few. The movie business didn't work that
[101:15] way at that time. It was basically
[101:16] packages that had been assembled by
[101:19] basically uh agents who put uh stars
[101:23] together with a star director whatever
[101:24] and brought them to the movie company.
[101:27] And we turned that and just started
[101:29] developing material. I mean, Saturday
[101:31] night fever came from a New York
[101:32] magazine article called the ad something
[101:35] adventures of a Saturday night
[101:36] something. Totally made up, by the way.
[101:38] Didn't really exist. It was fiction by
[101:41] Nick Cohen, a good writer. And we devel
[101:44] we bought that magazine article and then
[101:46] we developed the script. And we ended up
[101:48] probably having 90 or so projects in
[101:51] various stages of development. and you
[101:55] curating that development for getting
[101:56] into the rhythm of that just helped us
[101:59] beat the odds.
[102:01] >> So, at some point you you kind of become
[102:03] loose in the seat at Paramount. You're
[102:04] like, I want to I I I'm itching to do
[102:08] something new and you think that that
[102:09] new thing is a fourth TV network to
[102:12] rival CBS, NBC, and ABC, but it gets
[102:15] killed at Paramount. It didn't get well
[102:19] there was some little mini recession I
[102:21] think around 7273
[102:23] I don't know but somewhere in there and
[102:26] so G and Western pulled back kind of the
[102:29] fin it wasn't all that much then but
[102:32] pulled back the financing so yeah we
[102:34] couldn't do it
[102:35] >> you end up instead partnering with
[102:39] Rubert Murdoch and founding Fox
[102:43] >> as a television
[102:44] >> I went to Fox and then Uh, Rupert
[102:47] followed buying an interest in Fox. Uh,
[102:50] really basically a few months after I
[102:53] joined Fox.
[102:54] >> What did you see?
[102:55] >> I I I was very lucky. I inherited him.
[102:59] >> Say more about that.
[103:01] >> What What's the more part?
[103:03] >> Uh, today he's a very controversial
[103:06] figure.
[103:07] >> That is not really how you describe him
[103:09] in your book. You really describe him as
[103:11] he's this electric ball of energy.
[103:13] >> Oh, no. No. Rupert Murdoch is
[103:16] Let us separate for those people who do
[103:18] not as I don't like Fox News but uh as a
[103:23] as one of the great entrepreneurial
[103:27] gamblers who from a tiny little
[103:32] small town newspaper in Adelaide,
[103:35] Australia
[103:37] took over when newspapers were the thing
[103:41] the entire country of Australia and then
[103:44] moved to the UK and did that. Uh, and
[103:48] Rupert loved as he he he actually loved
[103:51] betting the company that I mean he was
[103:55] he he he was is the perfect
[103:59] gambling entrepreneur taking huge risk
[104:03] to do things that usually were against
[104:05] the establishment.
[104:07] Uh
[104:08] and and also he was if you have to work
[104:13] for anybody I I I would absolutely say
[104:16] work for him because he gave you all the
[104:20] authority and responsibility you wanted.
[104:22] He never made a single operating
[104:24] decision at Fox. We had one disagreement
[104:27] in eight years of working together. Uh
[104:31] first of all I
[104:34] what he was what he's was able to create
[104:36] on three continents I think it's three
[104:39] um thank you
[104:40] >> uh four India too
[104:42] >> fourth
[104:43] >> uh yeah star in India
[104:45] >> we did a big deep dive on uh IPL cricket
[104:48] a few months ago and he played a huge
[104:50] role in TV in India. Oh yes, yes. Oh,
[104:53] thank you. I didn't even I've got I
[104:54] learned something tonight. India is a
[104:56] continent.
[104:57] >> Well, in Asia, but
[104:59] >> thank you. Okay, I get it. Anyway, yeah.
[105:03] >> Uh this is this is this is not in our
[105:05] script, but I'm actually pretty
[105:06] interested the do you believe in the
[105:09] management strategy of betting the
[105:11] company or do you believe that when
[105:13] you're running a successful business?
[105:14] >> Absolutely.
[105:14] >> Never. [laughter]
[105:15] >> I absolutely
[105:16] >> you want to work for RER but you don't
[105:17] want to run a company like that.
[105:19] >> I don't got those guts. I actually think
[105:21] that the only thing I think the only
[105:23] thing I think you don't do is bet the
[105:26] company. I mean, you can take all sorts
[105:27] of risks.
[105:28] >> You can do all sorts of things that have
[105:31] that that have not god knows if you
[105:33] don't do those, nothing will happen. But
[105:35] to actually bet the company on a single
[105:37] thing, I I think that is the thing to
[105:40] absolutely avoid unless
[105:44] you're in this case Rupert Murdoch
[105:48] >> or unless you have no other options. I
[105:50] mean, it's it's it's it's this like
[105:52] addictive gamblers thing to be betting
[105:53] the company when you're already at your
[105:55] biggest when your back's way against the
[105:56] wall and you sort of have
[105:57] >> Well, no, that's different. that that
[106:00] we're talking about a company that's
[106:01] doing okay and you decide to take that
[106:05] good company that's doing okay and
[106:07] because you want to do something new
[106:08] over here, you place a bet on it that if
[106:12] it fails, it drags that good company
[106:15] with it underneath and that's not a good
[106:18] thing. Don't do that
[106:21] >> deal. How despite that though you were
[106:24] inspired by Rupert to become an
[106:27] entrepreneur and to go be a principal of
[106:29] your own business. I mean again you were
[106:32] head of Fox studio and television
[106:35] network
[106:36] >> and you
[106:37] >> your next step
[106:38] >> your next step was to Westchester,
[106:40] Pennsylvania, my hometown by the way
[106:43] >> which is not you know New York or LA
[106:45] >> not the Gardens to go by.
[106:48] It was because I wanted to I'd worked
[106:52] for companies all my life and and and if
[106:55] you work for a company and you you have
[106:59] this delusion that it belongs to you and
[107:01] you should have that you should feel
[107:03] that the company belongs to you but in
[107:05] fact it does not and so I got this thing
[107:10] in my head which was can I be
[107:13] independent of this I'd been a
[107:14] corporatist for I was 49 years old And
[107:18] so I'd been working for 30 years and
[107:22] could I be on my own? Could I not be
[107:25] part of a mother church and I got this
[107:29] thing in my head of you either are or
[107:30] you're not was but kind of a binary and
[107:33] I thought it wasn't by the way that I
[107:36] wanted to do it. I was fat and happy. Uh
[107:38] >> you were very wealthy at this point. You
[107:40] had done extremely well.
[107:41] >> Yeah. Yeah. Things were fine. And um
[107:44] [laughter]
[107:44] and I thought uh well you either are
[107:48] capable of being an in independent and
[107:52] creating something on your own or you're
[107:54] not. And as much as I wanted to stay at
[107:58] Fox, I couldn't accept that I was not.
[108:01] And it kind of it literally forced me
[108:03] out the door.
[108:05] >> And so you have to give up this like I'm
[108:08] a somebody in the world. I'll tell you
[108:09] the one thing I did
[108:10] >> big organization and big budgets and I
[108:12] >> the one thing I did that really helped
[108:14] me sorry but I can't help interrupting
[108:16] you
[108:18] um thank you the one thing I did is I
[108:22] began to think
[108:25] am I not going to go do this because I
[108:28] will now have to stand in line at an
[108:31] airport
[108:33] instead of going on this private plane
[108:35] that we had
[108:37] is that really it Am I is my sense so
[108:41] crummy that I'm going to make this
[108:44] decision about my life because I can't
[108:48] stand the idea of not having my own
[108:51] plane which doesn't belong to me anyway
[108:53] belongs to somebody else
[108:55] and I couldn't that one like I said uh I
[108:58] can't do that I mean I have to I have to
[109:01] brave that world so how does that sound
[109:03] everybody [laughter]
[109:06] by the way it didn't last long but
[109:07] that's another Yeah. Well,
[109:11] >> I can tell you nobody in Westchester,
[109:12] Pennsylvania had a private plane. Uh,
[109:15] >> all right. So, what you
[109:16] >> was an amazing business.
[109:17] >> Walk us through what you did. Why did I
[109:19] go there?
[109:19] >> Yeah. How did you find QVC? This is an
[109:21] amazing story.
[109:22] >> What happened is is that my wife Dion
[109:24] von Fenberg uh is a dress designer and
[109:28] uh and yeah. [applause]
[109:31] Hallelujah. Yes. So Dion calls me and
[109:34] she says, "This is uh I'm I'm at Fox."
[109:37] And she said, "No, no, sorry. I'd left."
[109:40] And I had no idea what I wanted to do. I
[109:42] just didn't want to repeat myself. I
[109:43] didn't want to run another movie
[109:44] company. I'd already run two. Uh and I
[109:48] didn't want I just didn't I didn't
[109:50] wasn't saying I wouldn't do uh movies
[109:54] and television stuff like that, but I
[109:56] just didn't want to I wanted to be open
[109:58] to stuff. So, I got in my car and I
[109:59] drove across the US just cuz I'd never
[110:02] uh been in the middle of it and I wanted
[110:03] to see it. And as I was on this road
[110:07] trip, Deion called me, said, "You have
[110:08] to go to Westchester, Pennsylvania, and
[110:10] see QVC." I said, "What is QVC?" She
[110:13] said, "It's a home shopping network." I
[110:14] said, "I'm not going to a home shopping
[110:15] network. Leave me alone." She said, "No,
[110:17] no, you have to go see this." And so, I
[110:21] went there. And it was it was this
[110:26] primitive convergence of televisions and
[110:29] telephones and computers working
[110:30] together. It it it was the first time
[110:35] and I saw on this little
[110:39] uh five times as big as the desk stage
[110:42] thing where product would come up and on
[110:45] a green screen at the time computer
[110:48] screen. uh the calls that came in when a
[110:52] product was put up and people would call
[110:54] in the the the screen would show it
[110:57] rising and then they would fall and
[110:58] rising and falling it and it was an
[111:01] epiphany. I that word is often overused
[111:04] but for me I was struck I was struck by
[111:08] it because I'd only known screens to be
[111:11] used for telling stories
[111:14] >> not for interacting for commerce I they
[111:16] were screens you know a screen you tell
[111:17] a story on it
[111:19] >> I had no clue they could be interactive
[111:21] until I got to QVC and that was
[111:23] primitive interactivity
[111:26] and when I saw it I was I I was it was
[111:31] it was an epiphany and and and then
[111:35] again the serendipitously
[111:38] uh two months later I got the
[111:41] opportunity to buy into it and I did it
[111:45] and of course everyone in the New York
[111:48] and certainly Hollywood community
[111:50] thought I had lost my mind. [laughter]
[111:53] They said that he's going to
[111:55] Westchester, Pennsylvania to a home
[111:57] shopping network, this most successful
[111:59] person and whatever.
[112:01] >> And uh yeah, I did that. And and this is
[112:05] in 93,
[112:06] >> right? For everyone who's listening,
[112:08] it's like QVC, but QVC at the time was
[112:11] about to catch this crazy wave and
[112:13] become like the IT company. It did do
[112:16] that. But what it did for me was this is
[112:20] 93
[112:22] getting to understand uh some technology
[112:26] and some of this connectivity and the
[112:29] possibilities of that
[112:31] >> two years before in '95 the internet
[112:34] started to get used by normal folk
[112:36] >> just put me in this position of knowing
[112:39] stuff before anyone else and that was
[112:41] invaluable. And what so IA the company
[112:45] that you would later found would end up
[112:49] uh buying, selling, starting or selling
[112:51] off over 150 companies including
[112:53] Expedia, Trip Advisors, Angie, Angie's
[112:56] List, Vimeo, Ticket Master, Tinder,
[112:57] Match.com.
[113:00] I mean,
[113:01] >> yeah,
[113:02] >> you started in the mail room at William
[113:03] Morris.
[113:05] >> Okay.
[113:07] >> You are like media and text Forest Gump.
[113:11] >> [laughter]
[113:13] >> I think I'm a little dumber than Forest,
[113:15] but that's okay. [laughter]
[113:18] >> We mean it in the best way. The Okay, we
[113:20] have one last question for you.
[113:21] >> Yes, sir. given that you have been at
[113:24] the top of both of these industries and
[113:26] you you write about in the book the
[113:28] state that the media and movie industry
[113:30] is in now and how it's dominated by tech
[113:33] companies
[113:33] >> and I think you talk about how they're a
[113:35] a much worse business that they are in
[113:37] your than they were in your time and b a
[113:39] lot less creative and a lot less fun.
[113:42] Why is it that the studios were
[113:44] resilient for the better part of a
[113:45] century to technology disruption, but
[113:48] now they're all owned by tech companies
[113:50] and have those characteristics you
[113:51] described?
[113:53] >> Look, what happened was the the movie
[113:55] business for 100 oh no 75 years.
[113:59] anything that came along whether it was
[114:03] tech things like the VCR uh and video
[114:06] cassettes and things everything cable
[114:08] television everything that came along
[114:10] they basically bought in themselves. So
[114:14] they remained for a very long time
[114:18] uh the most important companies in quote
[114:22] media and then along came Netflix
[114:27] uh a tech company and Netflix
[114:31] truly if you say one there's one entity
[114:35] that controls the media entertainment
[114:38] business today and it is Netflix. They
[114:40] have won. No one is ever going to beat
[114:43] them. And then Amazon comes along with
[114:46] Prime and then Apple and Amazon. How do
[114:50] you Amazon's business model, which is to
[114:55] get you to subscribe to Prime and buy a
[114:59] bunch of stuff. They give you some
[115:01] video. Now, if you're in that's their
[115:04] business model. If you're in the
[115:06] entertainment business, your business
[115:07] model is create hits. And they don't
[115:09] really care if you have a hit or not.
[115:11] They just want more toasters sold etc.
[115:15] So and these three companies have a
[115:19] hundred times at least the resources of
[115:21] these old movie companies. So the whole
[115:25] hedgeimony has now shifted to tech. tech
[115:28] now totally controls media
[115:32] >> and and the net result is that or or if
[115:35] I could simplify this down, it's that
[115:38] movie production is just not that big a
[115:40] business and is being and TV production
[115:42] and is being used as a loss leader
[115:44] >> to offer something to consumers for
[115:46] other tech businesses.
[115:47] >> Look, no, not at Netflix, it's not a
[115:49] loss leader, but at Netflix you
[115:51] subscribe to the service.
[115:54] >> No one,
[115:54] >> it's not about the individual piece of
[115:55] content. one movie is going to mean very
[115:59] much as so long as you're satisfied with
[116:01] the service and you subscribe. That's
[116:03] again a completely different business
[116:05] model than making hits.
[116:08] >> Yep. All right. With parting words, what
[116:11] is a piece of advice you would give to
[116:12] all the entrepreneurs in the audience
[116:14] today?
[116:15] >> A piece of advice
[116:17] >> straight from Barry Diller.
[116:18] >> Be curious. I don't know. I got no piece
[116:20] of advice, [laughter]
[116:22] >> but I wish everyone the best.
[116:25] Everyone Dylan,
[116:29] [music]
[116:33] >> thank you so much. [applause]
[116:38] [music]
[116:44] >> Well, that was a great way to end the
[116:45] night.
[116:46] >> What a night, David.
[116:47] >> What a night it was. Well, everyone,
[116:49] when we started Acquired 10 years ago,
[116:51] if you told us we would be playing Radio
[116:53] City Music Hall, I don't think in our
[116:55] wildest wildest dreams we could have
[116:57] dreamed this big.
[116:58] >> No, it was a tech podcast with Yeah,
[117:01] [cheering]
[117:01] come on.
[117:03] >> This has been amazing.
[117:05] >> So, thank you so much to all of you for
[117:07] coming tonight and to listening to our
[117:09] podcast over the years. It means so
[117:10] much. Thank you so much to Jamie
[117:12] Diamond, Andrew Ross, Sorcin, Medith
[117:14] Copet, Levian, and Barry Diller. Thanks
[117:16] also to our audience participants
[117:18] Christina Cassiopo, Ben Kimber, Howard
[117:21] Schultz, and surprisingly Jamie Diamond.
[117:23] Again,
[117:25] thank you to our hosts JP Morgan, to
[117:27] Hermes for dressing us. And most
[117:29] importantly, thank you to the many,
[117:30] many, many people on the JP Morgan team
[117:32] who gave their days, nights, weekends
[117:34] for this. Thank you to our production
[117:36] crew. There are hundreds of people who
[117:38] put on tonight for everyone. Come on
[117:40] out.
[117:42] [music]
[117:47] 1 1 2 3
[117:52] [music]
[117:54] down. Thank you, Mike.
[117:58] [music]
[117:59] And most importantly, thank you, Mike
[118:02] Taylor. Take it [music] all, Mike.
[118:09] Heat.
[118:14] [music]
[118:20] [music]
[118:28] [music]
[118:28] Heat.
[118:33] [music]
[118:47] >> [music]
[118:56] [music]
[119:00] >> Dude, they did it.
[119:04] What's your line of the night?
[119:07] >> Barry Diller saying it was all me. Yes.
[119:09] [laughter]
[119:11] >> Or or Jamie spoiling that Howard was
[119:13] here. We had this thing. He's like, I
[119:15] think Howard Schultz is here.
[119:16] >> And Andrew Ross Orchid.
[119:18] >> No surprises.
[119:20] >> I can't believe.
[119:21] >> Thanks so much, man. Really appreciate
[119:22] it.
[119:24] >> Oh, thanks.
[119:25] >> So great.
[119:26] >> Thanks.
[119:27] >> I can't believe we just played Radio
[119:28] City,
[119:29] >> man.
[119:30] >> Surreal. The world is a wonderful place.
[119:32] >> Afterparty.
[119:33] >> Let's do it.
[119:35] >> So, is Jamie Diamond going to run for
[119:37] president?
[119:38] >> We'll see.